



ECB hikes 75bps as expected; Scraps forward guidance
The tone set by the removal of forward guidance and the lack of information regarding QT led the markets to believe this was a dovish hike.
Share this:
The ECB hiked rates by 75 bps to bring the deposit rate to 2%, as widely expected. This is the highest level for the key rate since 2009. The decision was not unanimous however, as 3 officials only wanted to hike rates by 50bps. In addition, the statement noted that members would take a meeting by meeting approach to rate decisions and dropped the text stating that it would raise rates over “the next several meetings”. The statement said that it “expects to raise rates further, to ensure the timely return of inflation to its 2% medium-term inflation target”. Regarding inflation, the statement said that “Inflation remains far too high and will stay above the target for an extended period.” The latest reading of the Euro Area inflation for September was 9.9% YoY, its highest ever, vs a prior reading of 9.1% YoY. October’s CPI will be released on Monday with an expectation of 9.6% YoY.
In the press conference that followed, Christine Lagarde explained that QT was not discussed at this meeting, disappointing some traders who took this as a dovish clue. She said that it will be on the agenda at the December meeting, however no start date will be announced. She also said that economic activity likely slowed significantly in Q3 and is likely to slow further in Q4 and Q1 2023. Regarding the economic outlook, she said that risks are clearly to the downside and regarding inflation, risks are clearly to the upside.
The big mover on the day as a result of the ECB meeting and the subsequent press conference was the 2-year German Bund yield, which fell nearly 10% on the day from a high of 2.036% down to 1.768%.

Source: Tradingview, Stone X
The lower rates dragged the Euro down with them. EUR/USD has been in a downwards sloping channel since February. However, on Tuesday, the pair moved higher out of the channel and then back above parity for the first time since September 20th. As traders looked at today’s ECB actions as a “dovish hike”, EUR/USD reversed from a high of 1.0080 and fell to a low of 0.9959. (At the time we go print, EUR/USD is still making new daily lows). First support on the daily timeframe is a confluence of support at the top downward sloping trendline of the long-term channel and the 50-Day Moving Average near 0.9889. Just below there, support is at an upward sloping trendline from the lows of September 28th near 0.9770 and then the September 28th lows at 0.9536. However, if he confluence of support holds, the first resistance is at the highs from September 12th at 1.0198 and then the 38.2% Fibonacci retracement level from the highs of February 10th to the lows of September 28th at 1.0284. Above there, price can move to a zone of resistance between 1.0349 and 1.0369.

Source: Tradingview, Stone X
The ECB hiked rates on Thursday by 75bps, as expected. However, the tone set by the removal of forward guidance and the lack of information regarding QT led the markets to believe this was a dovish hike. Will the ECB continue to hike rates? The first clue may come on Monday when the preliminary look at the October CPI will be released!
The ECB hiked rates by 75 bps to bring the deposit rate to 2%, as widely expected. This is the highest level for the key rate since 2009. The decision was not unanimous however, as 3 officials only wanted to hike rates by 50bps. In addition, the statement noted that members would take a meeting by meeting approach to rate decisions and dropped the text stating that it would raise rates over “the next several meetings”. The statement said that it “expects to raise rates further, to ensure the timely return of inflation to its 2% medium-term inflation target”. Regarding inflation, the statement said that “Inflation remains far too high and will stay above the target for an extended period.” The latest reading of the Euro Area inflation for September was 9.9% YoY, its highest ever, vs a prior reading of 9.1% YoY. October’s CPI will be released on Monday with an expectation of 9.6% YoY.
Everything you need to know about the ECB
In the press conference that followed, Christine Lagarde explained that QT was not discussed at this meeting, disappointing some traders who took this as a dovish clue. She said that it will be on the agenda at the December meeting, however no start date will be announced. She also said that economic activity likely slowed significantly in Q3 and is likely to slow further in Q4 and Q1 2023. Regarding the economic outlook, she said that risks are clearly to the downside and regarding inflation, risks are clearly to the upside.
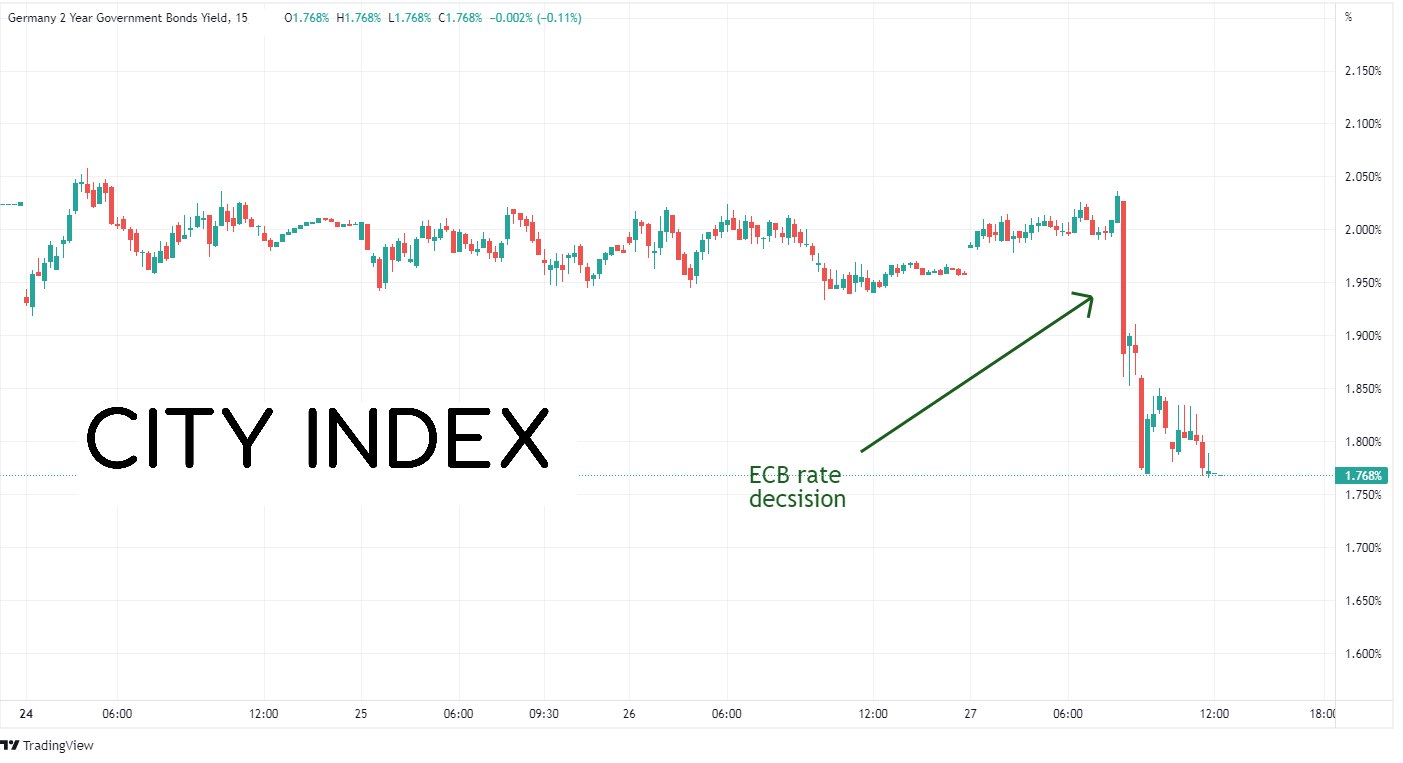
The big mover on the day as a result of the ECB meeting and the subsequent press conference was the 2-year German Bund yield, which fell nearly 10% on the day from a high of 2.036% down to 1.768%.
Source: Tradingview, Stone X
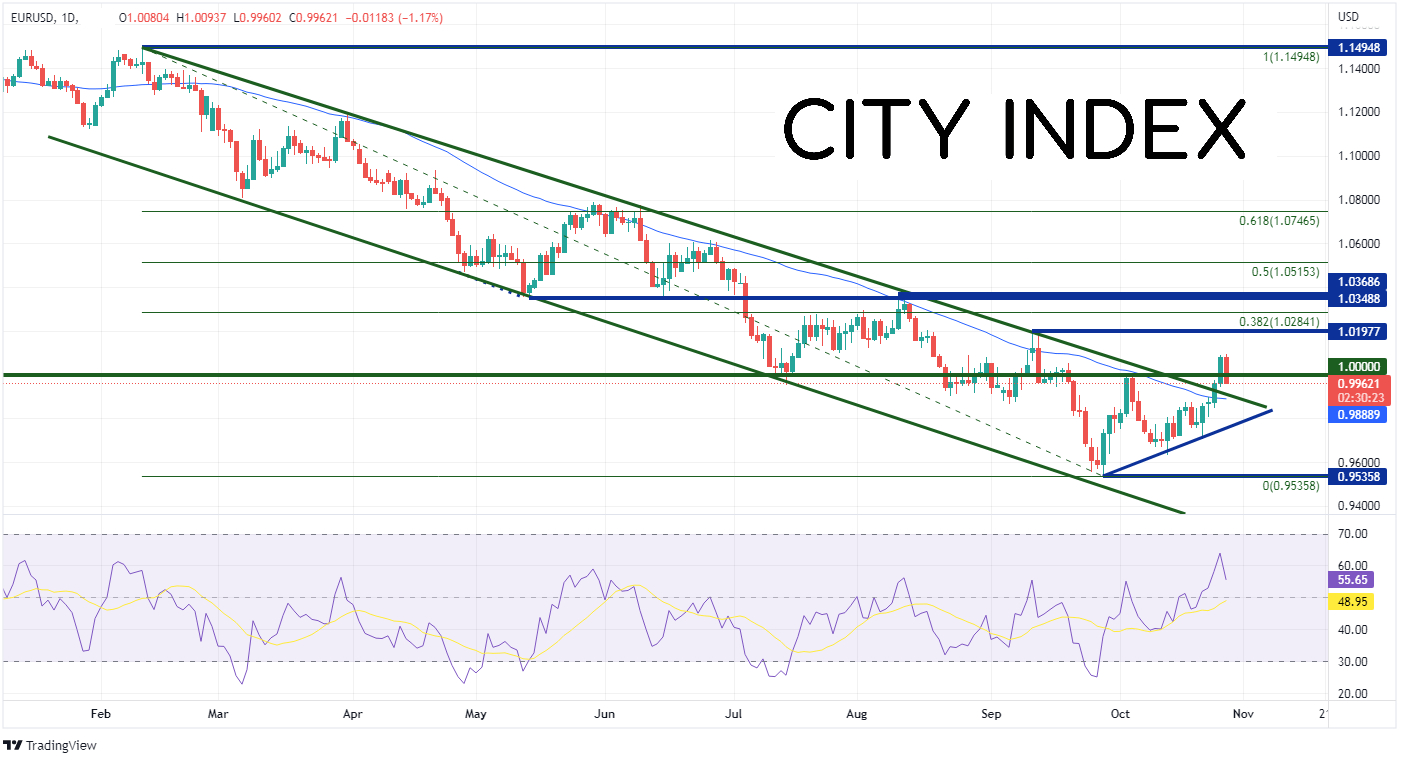
The lower rates dragged the Euro down with them. EUR/USD has been in a downwards sloping channel since February. However, on Tuesday, the pair moved higher out of the channel and then back above parity for the first time since September 20th. As traders looked at today’s ECB actions as a “dovish hike”, EUR/USD reversed from a high of 1.0080 and fell to a low of 0.9959. (At the time we go print, EUR/USD is still making new daily lows). First support on the daily timeframe is a confluence of support at the top downward sloping trendline of the long-term channel and the 50-Day Moving Average near 0.9889. Just below there, support is at an upward sloping trendline from the lows of September 28th near 0.9770 and then the September 28th lows at 0.9536. However, if he confluence of support holds, the first resistance is at the highs from September 12th at 1.0198 and then the 38.2% Fibonacci retracement level from the highs of February 10th to the lows of September 28th at 1.0284. Above there, price can move to a zone of resistance between 1.0349 and 1.0369.
Source: Tradingview, Stone X
Trade EUR/USD now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
The ECB hiked rates on Thursday by 75bps, as expected. However, the tone set by the removal of forward guidance and the lack of information regarding QT led the markets to believe this was a dovish hike. Will the ECB continue to hike rates? The first clue may come on Monday when the preliminary look at the October CPI will be released!
Learn more about forex trading opportunities.
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.