



Europe Points Higher As US Stimulus Is Back On UK GDP Disappoints
US stimulus optimism is overshadowing disappointing UK GDP data and rising covid numbers.
Share this:
A strong finish on Wall Street boosted Asian markets to an almost 2.5 year high and is lifting European markets on the open. US stimulus optimism is overshadowing disappointing UK GDP data and rising covid numbers.
A U-turn by Trump and talk of progress by House Speaker Nancy Pelosi in negotiations towards securing a large-scale fiscal stimulus package is driving a risk on rally. The improving mood in the market is boosting demand for riskier assets such as stocks, whilst dragging on demand for the US Dollar.
Recent data is highlighting the stalling nature of the US recovery. Yesterday’s US jobless claims showed that 840K Americans signed up for unemployment benefit for the first time. This was only 9K down from the previous week and 20k higher than forecast. The labour market recovery is running out of steam and requires additional stimulus for the recovery to continue.
Adding to the risk on mood, the market is increasingly pricing in a Democratic win by Joe Biden. Whilst typically Democrats are considered less market friendly than Republicans, Democrats are supportive of a huge stimulus package. So even if covid relief aid doesn’t get agreed by the November 3rd election with Biden increasingly looking to take the keys to the White House, the prospect of a huge deal thereafter is adding to the upbeat mood.
UK Economic Growth Slows Considerably
UK GDP grew at just 2.1% in August compared to July. This was down from 6.6% growth in July and missed forecasts of 4.6%. This is a surprisingly weak reading and suggests that the economy is doing worse than feared. The British economy only managed relatively weak growth compared to the previous month despite the government’s continued furlough programme and Brits gorging themselves on the Chancellor’s Eat Out To Help Out scheme. The rebound was clearly already running out of steam in August which doesn’t bode well for the coming months
With the resurgence of covid infections there is a good chance that the economic rebound from April’s record -20.4% will slow further. Lockdown restrictions are being tightened and more restrictive measures could still be applied over the coming weeks and months as the number of cases continue to surge. Add into the mix the replacement of the furlough scheme with a less generous successor means unemployment is also expected to rise. All in all, we are looking towards particularly and dark challenging Autumn and Winter months.
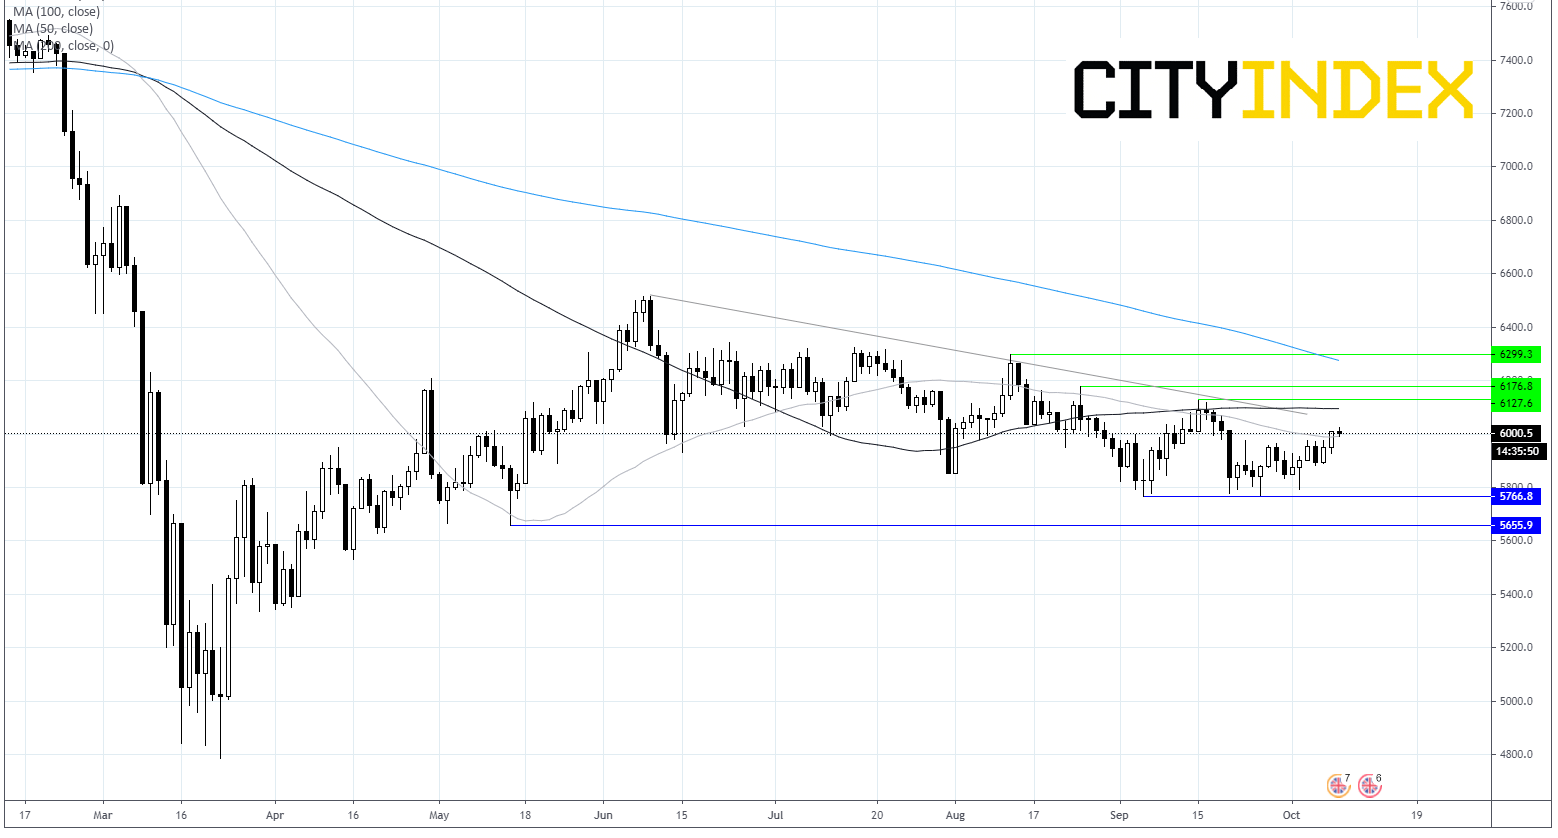
The Pound has given up earlier gains versus the broadly weaker dollar and is turning negative in reaction to the depressing statistics. The FTSE is holding mild gains.
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.