



Europe Points Higher After US Big Tech Surges NatWest Tumbles Into Loss
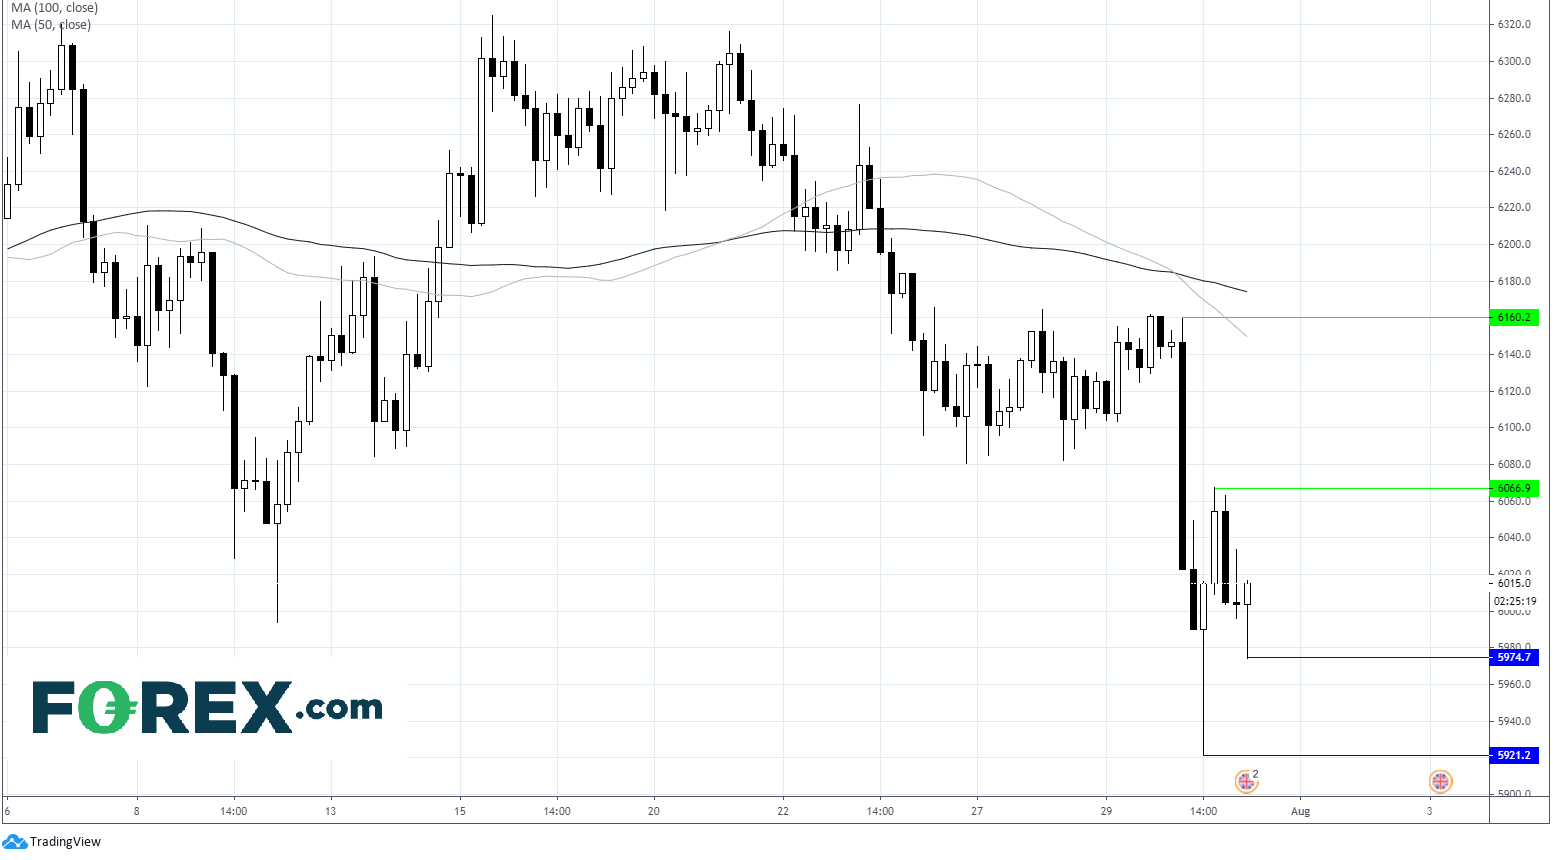
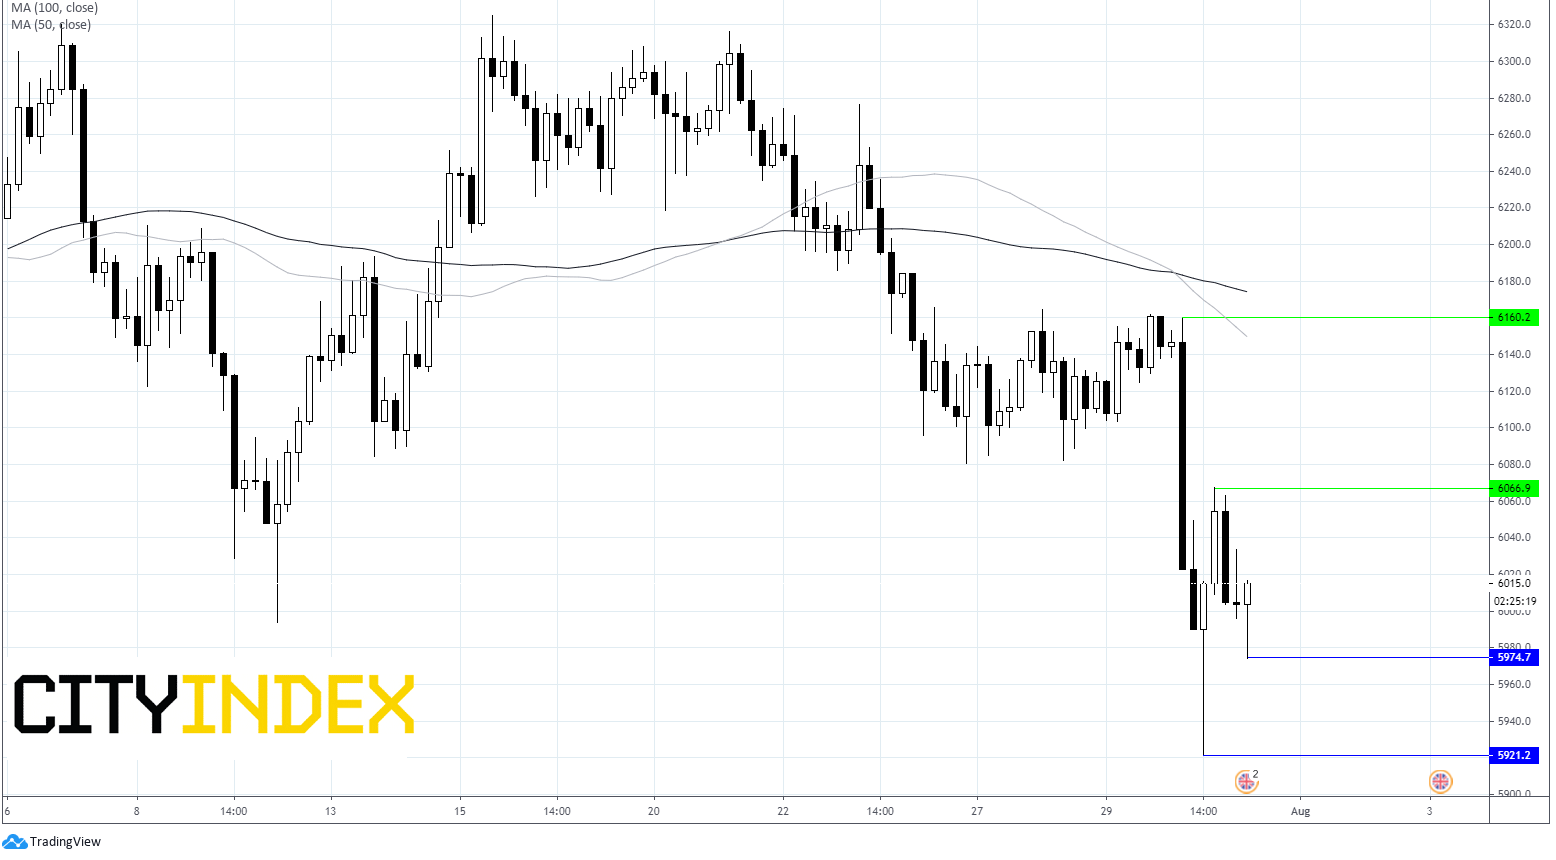
European bourses are pointing to a mildly higher start as investors continue digesting data and earnings from the previous session. The US Dollar is on track for its worst monthly performance in a decade.
Share this:
European bourses are pointing to a mildly higher start as investors continue digesting data and earnings from the previous session. The US Dollar is on track for its worst monthly performance in a decade.
US economic growth plunges and recovery is looking shaky
The US economy contracted by -9.5% qoq in the second quarter or 32.9% on an annualised basis, the deepest decline since at least the Great Depression as lock down measures saw consumer demand and business investment evaporate.
However, what is perhaps more concerning is that more recent data, as highlight by Federal Reserve Chair Jerome Powell, has shown that the pace of the recovery is slowing. Rising coronavirus infections are curbing consumption sending the economy downhill. Consumer confidence is fading, and Initial jobless claims showed that the recovery in the US labour market is stalling. This, in addition to Trumps suggestion of delaying the Presidential elections has sent the dollar to fresh 2-year lows.
Big tech crushes forecasts
Whilst the Dow and the S&P closed lower the Nasdaq rallied after blowout results from the Faangs. Apple, Amazon, Facebook and Alphabet (Netflix reported earlier in the month) reported earnings or revenue that crushed analysts’ forecasts. The numbers confirm what investors had been thinking that not only are these stocks weathering the coronavirus pandemic, they are positively thriving in it.
Whilst the Dow and the S&P closed lower the Nasdaq rallied after blowout results from the Faangs. Apple, Amazon, Facebook and Alphabet (Netflix reported earlier in the month) reported earnings or revenue that crushed analysts’ forecasts. The numbers confirm what investors had been thinking that not only are these stocks weathering the coronavirus pandemic, they are positively thriving in it.
China’s manufacturing recovery gains momentum
Upbeat data from China is also helping the mood. PMI data showed that manufacturing activity grew for a 5th straight month, expanding at a faster pace than forecast, indicating that the recovery in the world’s second largest economy is gaining momentum, some well needed good news!
Upbeat data from China is also helping the mood. PMI data showed that manufacturing activity grew for a 5th straight month, expanding at a faster pace than forecast, indicating that the recovery in the world’s second largest economy is gaining momentum, some well needed good news!
2nd wave fears see localised UK lockdowns
Fears are growing of a second wave in Europe. UK Health Secretary Matt Hancock has rolled back reopening measures in parts of Manchester, Lancaster and Yorkshire owing to an increased transmission rate. 4.5 million people will see lockdown conditions tightened. For now, the markets are managing to shrug this off. However, this is definitely something to monitors. The Pound is trading at fresh 4.5 months highs versus the USD on Dollar weakness. However, sterling is slipping lower versus the Euro.
Fears are growing of a second wave in Europe. UK Health Secretary Matt Hancock has rolled back reopening measures in parts of Manchester, Lancaster and Yorkshire owing to an increased transmission rate. 4.5 million people will see lockdown conditions tightened. For now, the markets are managing to shrug this off. However, this is definitely something to monitors. The Pound is trading at fresh 4.5 months highs versus the USD on Dollar weakness. However, sterling is slipping lower versus the Euro.
NatWest reports larger bad loan provision than expected
NatWest reported H1 results, tumbling into a loss after setting aside £2.1 billion for bad loan provisions, more than the £1.7 billion forecast. NatWest has thousands of small companies as customers, making the bank particularly vulnerable to souring loans as the coronavirus crisis continues The bank reported £770 million pre-tax loss compared to £2.7 billion profit the previous year.
NatWest reported H1 results, tumbling into a loss after setting aside £2.1 billion for bad loan provisions, more than the £1.7 billion forecast. NatWest has thousands of small companies as customers, making the bank particularly vulnerable to souring loans as the coronavirus crisis continues The bank reported £770 million pre-tax loss compared to £2.7 billion profit the previous year.
Eurozone GDP in focus
After German GDP laid bare the impact of the coronavirus lockdown in Q2, the Eurozone is set to do so today. Expectations are for a -12% qoq contraction. However, with the recovery in the Eurozone appearing to be on track, the data may be shrugged off.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.