




FTSE Turns Positive
European bourses are heading lower in early trade on Monday as investors pause for breath after a phenomenal rally across the month of November. Some European benchmark indices have surged over 20% higher. The FTSE, which has reversed earlier losses is outperforming its peers.
Share this:
European bourses are heading lower in early trade on Monday as investors pause for breath after a phenomenal rally across the month of November. Some European benchmark indices have surged over 20% higher. The FTSE, which has reversed earlier losses
Vaccine optimism has driven risk appetite and stock markets higher across November. Over the past month Pfizer, Moderna and AstraZeneca have all revealed upbeat results from their clinical trials. A vaccine is the quickest and surest way for global growth to return to pre-pandemic levels.
News that the UK regulators could approve the Pfizer vaccine in the coming days is keeping optimism surrounding UK stocks buoyant. The FTSE is outperforming its European peers, pushing into positive territory.
JD Sports is a clear winner, topping the as investors cheer the athleisure retailer stepping back from talks with Debenhams. JD Sports jumps 6.7%, even as trouble on the high street brews.
Oil drops 1%, oil majors decline
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Gold has lost its shine
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
Coming up
Looking ahead, UK mortgage approvals will keep house builders in focus. Approvals have been particularly strong across recent months as prospective buyers look to take advantage of the government’s stamp duty holiday scheme, which is set to run until March.
German inflation data is also due later. Expectations are for inflation to remain subdued in disinflation as the Eurozone’s largest economy extends its lockdown until 20th December.
FTSE Chart
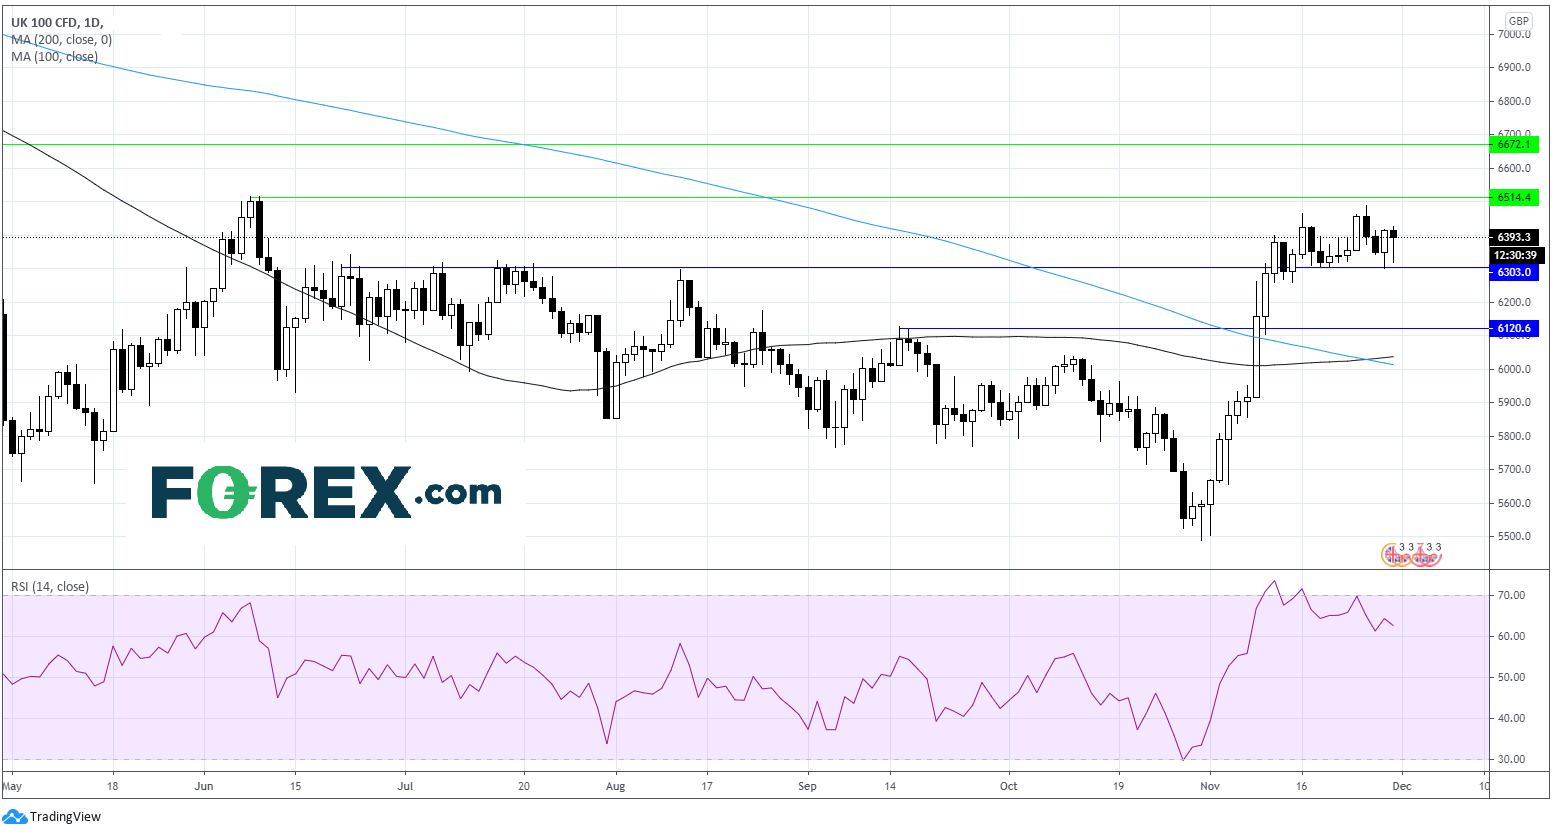
The FTSE continues to consolidate in the horizontal channel 6300 – 6515. The index rebounded off the lower band of the channel at the end of last week and is heading back towards the upper band at 6515. A break above this level could see the FTSE advance to 6670 a level last seen in March. On the flip side immediate a break through 6300 could open the door to horizontal support at 6120 prior to 200 day moving average and psychological support at 6000.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.