




Market Brief GBPUSD Hits a 30Month Low
See a summary of the top market themes and trends from today's US trading session!
Share this:


- FX: The Japanese yen was the strongest major currency, while British pound was the weakest, taking GBP/USD through 1.2100 to its lowest close in more than 30 months.
- President Trump was (of course) tweeting today, stating that the US doesn’t have to devalue the dollar, but that he’d like to see the Fed cut interest rates by 1.00%. Initial fears about the US government banning Huawei were assuaged by news that Federal authorities are still accepting applications for certain non-sensitive companies to deal with the firm.
- Commodities: Oil prices rallied nearly 4% today to finish just below the week’s opening levels. Gold was flat on the day.
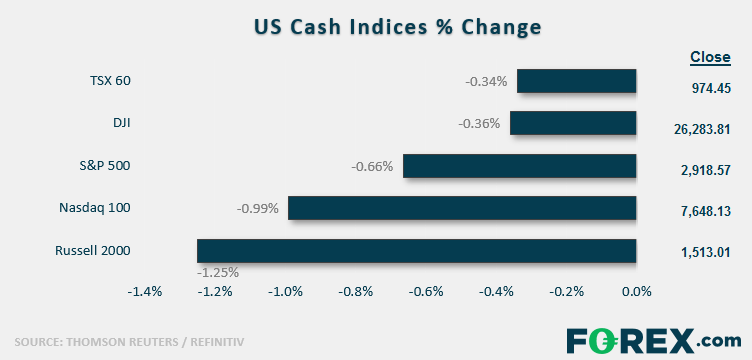
- US indices fought back from early losses but still closed lower on the day and down slightly on the week overall
- Health Care (XLV) was the strongest sector on the day, while Communication Services (XLC) brought up the rear.
- See the key economic data and market trends we’ll be watching in the coming week!
- Stocks on the Move:
- Uber (UBER) ultimately closed down -1%, despite slightly disappointing earnings after the bell yesterday. Lyft (LYFT) outperformed its rival, tacking on 1% today.
- Advance Micro Devices (AMD) surged 16% today, completely erasing yesterday’s big drop.
- Overstock.com (OSTK) surged nearly 20% after the online retailer reported strong earnings.
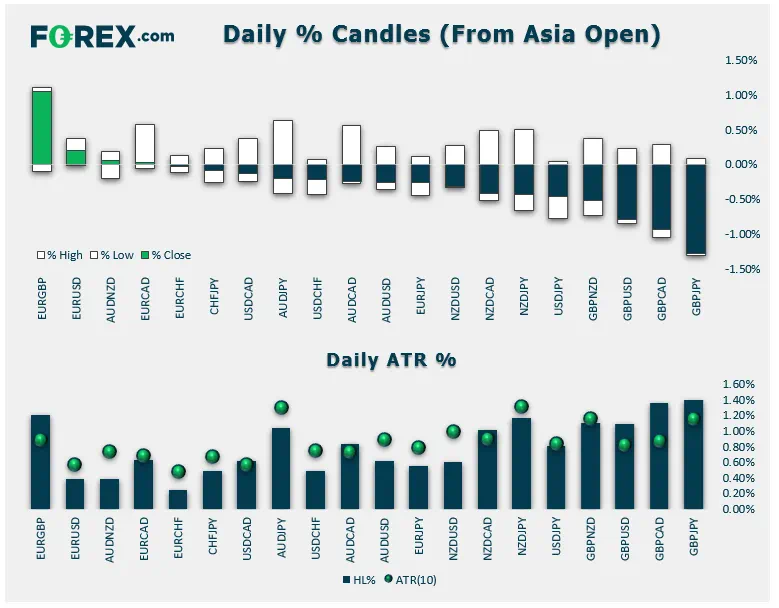
- FX: The Japanese yen was the strongest major currency, while British pound was the weakest, taking GBP/USD through 1.2100 to its lowest close in more than 30 months.
- President Trump was (of course) tweeting today, stating that the US doesn’t have to devalue the dollar, but that he’d like to see the Fed cut interest rates by 1.00%. Initial fears about the US government banning Huawei were assuaged by news that Federal authorities are still accepting applications for certain non-sensitive companies to deal with the firm.
- Commodities: Oil prices rallied nearly 4% today to finish just below the week’s opening levels. Gold was flat on the day.
- US indices fought back from early losses but still closed lower on the day and down slightly on the week overall
- Health Care (XLV) was the strongest sector on the day, while Communication Services (XLC) brought up the rear.
- See the key economic data and market trends we’ll be watching in the coming week!
- Stocks on the Move:
- Uber (UBER) ultimately closed down -1%, despite slightly disappointing earnings after the bell yesterday. Lyft (LYFT) outperformed its rival, tacking on 1% today.
- Advance Micro Devices (AMD) surged 16% today, completely erasing yesterday’s big drop.
- Overstock.com (OSTK) surged nearly 20% after the online retailer reported strong earnings.


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.