



Nasdaq 100 analysis: Risk off as oil rises but yields dip
Crude oil prices have risen in excess of 3% on worries Israel is preparing for a ground invasion of Gaza, raising geopolitical risks in the region. Thursday’s publication of hotter-than-expected data raised the prospects of interest rates remaining high for longer. This narrative is finding further support from rising oil prices. The focus will also turn to company earnings, with banks set to kick start the reporting season today.
Share this:
- Nasdaq 100 analysis: For how long can big techs hold up the market?
- Crude oil on the rise again, raises stagflation worries
- Banks set to kick off reporting season
- Nasdaq 100 technical levels to watch
After the sizeable sell-off on Thursday for stocks and bond markets, there has been some downside follow-through in European markets and US index futures. Crude oil prices have risen in excess of 3% on worries Israel is preparing for a ground invasion of Gaza, raising geopolitical risks in the region. Thursday’s publication of hotter-than-expected data raised the prospects of interest rates remaining high for longer. This narrative is finding further support from rising oil prices. The focus will also turn to company earnings, with banks set to kick start the reporting season today. We will also have consumer sentiment data in the afternoon.
Nasdaq 100 analysis: For how long can big techs hold up the market?
While the Nasdaq 100 is lower today, it has been able to hold its own much better than many other global indices of late. The big technology stocks have been able to hold up the market, while small- and medium-caps have sold off more profoundly. Some investors clearly view technology behemoths as haven assets, which may explain their outperformance. But with overstretched valuations, coupled with growing worries about the health of the global economy and the renewed rise in government bond yields on Thursday (though they have fallen back due to haven flows into bonds), I am not so sure how long they will be able to hold up the market.
Crude oil on the rise again, raises stagflation worries
There are fears that the escalation of the war between Israel and Hamas, could draw Iran into the picture, possibly other oil-producing countries too in the region. This could further exacerbate supply worries, sending oil prices above $100 a barrel. A sustained rise in oil prices will hurt the global economy even more, and this is clearly not good for stock markets with already-high valuations.
As well as raised geopolitical risks, oil prices are continuing to find good support on the back of the ongoing supply cuts by the OPEC and allies. The renewed rise in oil prices today, if sustained, could stoke inflationary worries further and make stagflation even worse for oil-importing countries in the Eurozone, Japan and China, among others. This comes as borrowing costs have skyrocketed across the developed economies. If crude oil were to rise even further, then this could further hurt the global economy, which is not something that would appease the stock market bulls.
Banks set to kick off reporting season
You can read our preview for bank earnings HERE, written by my colleague Joshua Warner.
You can read our preview for bank earnings HERE, written by my colleague Joshua Warner.
According to Mr Warner, “We think early signs that investment banking has bottomed-out will be the key themes at Morgan Stanley and Goldman Sachs, with the latter also likely to draw attention as its tries to offload its consumer business. Citigroup’s massive restructuring, which is yet to win the confidence of the markets, will also remain under the spotlight although a proper update isn’t expected until later this year. Wells Fargo, which is focused on more traditional banking activities and still hamstrung by limits on how large it can grow, is also divesting assets to improve efficiency and redirect resources to core activities.”
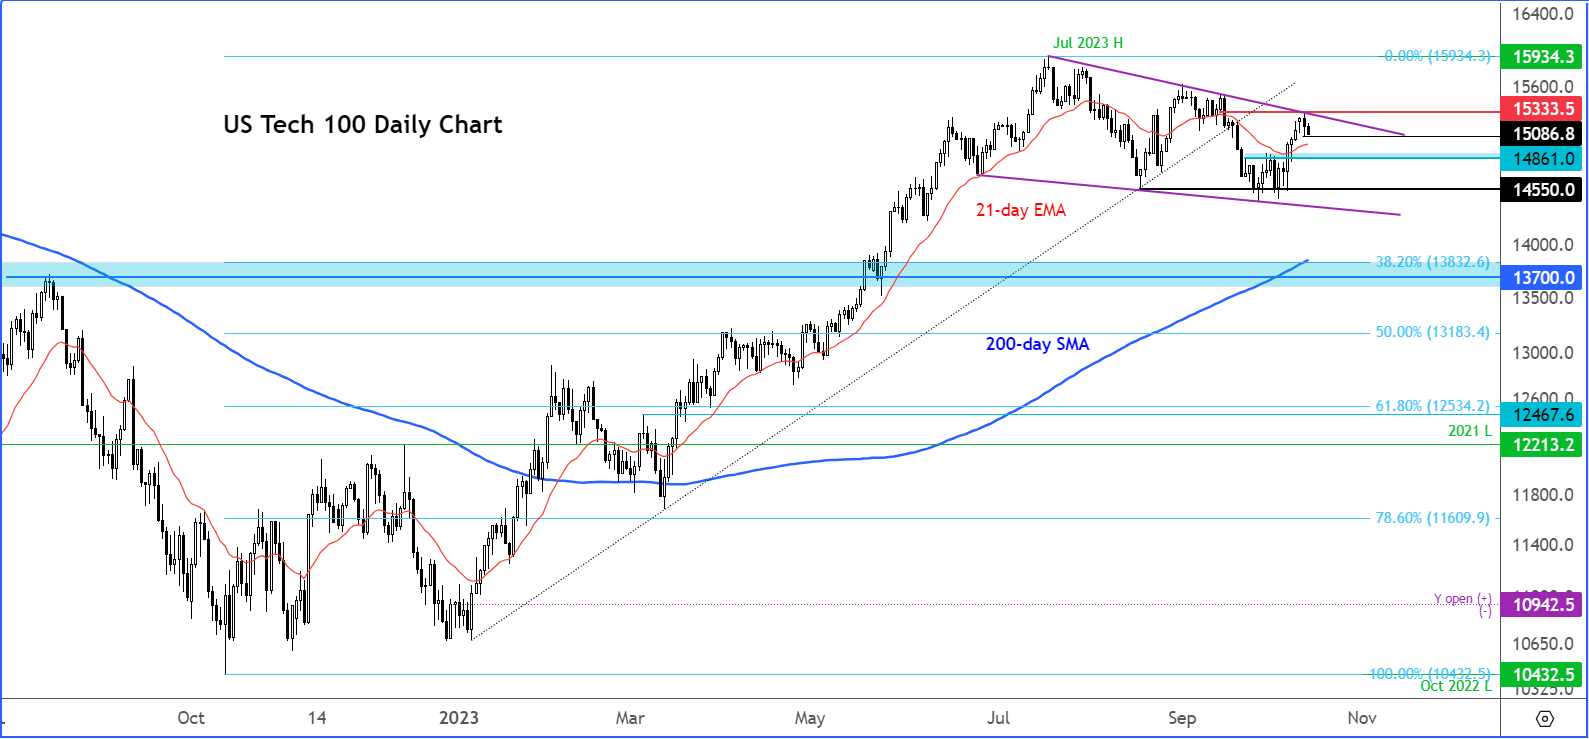
Nasdaq 100 analysis: Technical levels to watch
Source: TradingView.com
After Thursday’s sell-off, we got a bounce late in the session that ensured the Nasdaq would close off its worst levels. But at the time of writing, the Nasdaq 100 futures had turned lower again, pointing to a lower open on Wall Street.
The key level to watch is Thursday’s low at 14086, Thursday’s low. If the market decides to trade below this level, then watch to see if there’s any downside commitment, in light of the sizeable recovery in the last couple of weeks.
If there’s commitment below Thursday’s low, then that would put the next support area around 14860-14900 into focus next. Subsequent downside target is near the consolidation low around 14550, which is some distance away but could get there if short term support levels break down one after another.
Otherwise, if there’s no real commitment by the bears to hold the index below Thursday’s low, then we could see yet another Friday rally.
All told, the risks appear skewed to the downside after yesterday’s sizeable drop in all major global indices. There’s also question marks over the validity of the long-term bullish trend given heightened macro risks and the technical damage many individual stocks (apart from the big tech companies) and indeed indices have incurred. The small-cap Russell index, for example, appears significantly weaker than the Nasdaq.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.