



US open: Futures rise with midterm elections in focus
Stocks are rising with all eyes on the midterm elections. Is a gridlock government coming?
Share this:

US futures
Dow futures +0.2% at 32916
S&P futures +0.2% at 3816
Nasdaq futures +0.4% at 11029
In Europe
FTSE +0.09% at 7306
Dax +0.41% at 13590
Gridlock in Washington?
US stocks are pointing to modest gains on the open, extending the winning run for stocks into a third straight day as investors look ahead to the crucial midterm elections.
The latest polls suggest that the Republican party is likely to take back with House of Representatives and could potentially take back the Senate as well. Let’s not forget that Americans will be heading to the polls at a time when inflation is at multi-decade highs and a recession is looming.
Should Republicans take control of Congress, or at least the House of Representatives, it would result in gridlock in Washington, making it much harder for President Biden to push through his agenda, which includes antitrust regulations on big tech and social spending programmes, which could add to the inflationary environment.
With additional spending risks moderated, the Fed may need to do less to rein in inflation, with is good news for stocks. Additionally, historically speaking, the S&P500 has booked high annualised returns when there is a Democrat in the White House, and Republicans take control of Congress.
The results could be in quickly in the case of a massive wave of Republican support. However, there is also a realistic chance that results won’t be known until tomorrow or later in the week.
Aside from the midterm elections, the economic calendar is quiet. The main focus will be on Thursday’s CPI inflation data, which could provide fresh clues as to the likely move by the Fed in December.
Corporate news:
Lyft trades 19% lower and is flirting with all-time lows after the passenger numbers missed expectations, fueling fears that it is losing market share to larger rivals,
Disney is due to report Q4 earnings after the close. The theme parks and entertainment segment is expected to see revenue jump 39%. Disney+ streaming figures are also likely to impress, rising by 9.3 million.
Tesla is rising pre-market, rising from a yearly low as investors questioned whether Elon Musk would need to sell shares as Twitter losses mount.
Where next for the Dow Jones?
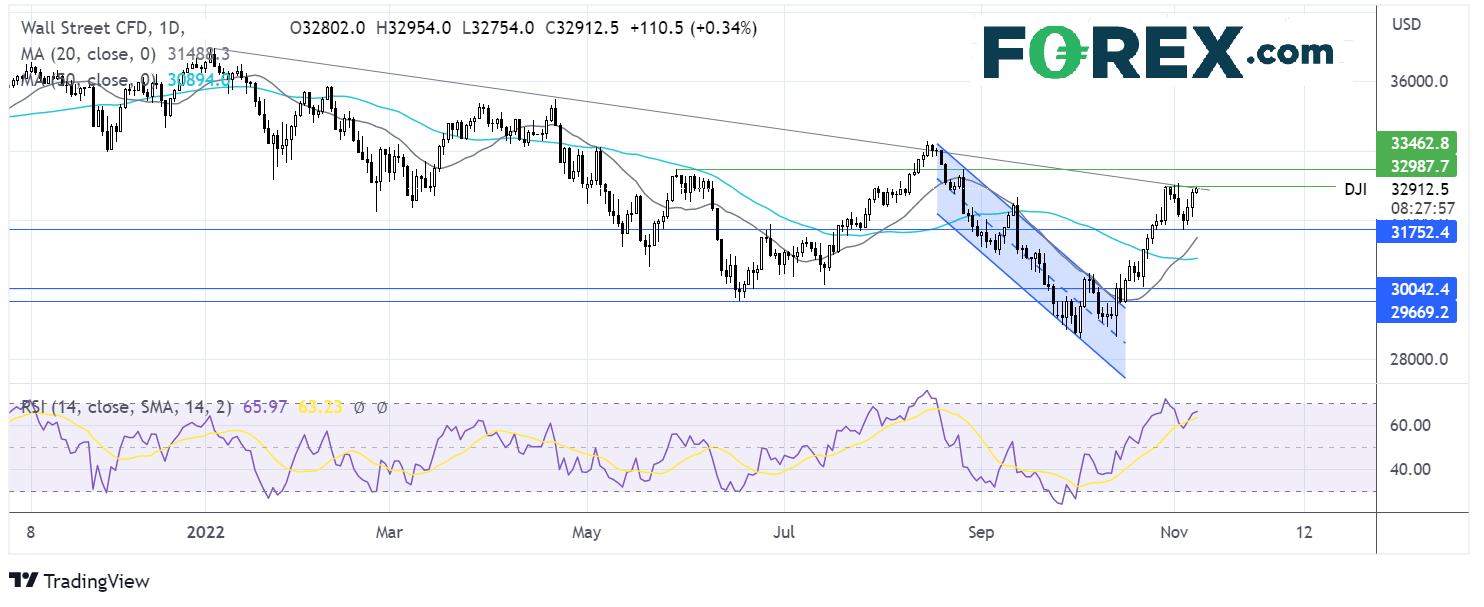
The Dow Jones is pushing higher, targeting 33,000, last week’s high, the round number and the falling trendline resistance. The RSI is over 50, and the 20 sma has crossed over the 50 sma, keeping buyers optimistic of further upside. Buyers will look for a rise over 33,000 to create a higher high before bringing 33460, the August 26 high, into focus. Sellers will look for a move below 317100 to expose the 20 sma at 31300 and the 50 sma at 30850.
FX markets – USD rises GBP falls
The USD is rising after several days of losses as attention turns to the midterm elections and political uncertainty. A gridlock in Washington could be USD-negative if fewer spending programmes are passed.
EURUSD falling on USD strength, despite retail sales coming in as expected. Sales rose 0.4% MoM in September after falling -0.3% in August. Even so, with inflation at a record high, this is unlikely to be a turning point in consumption.
GBPUSD is falling, paring some of yesterday’s strong gains. Talk of cooperation with Europe and hopes of a gas deal with the US lifted sterling yesterday. Today, the bleak outlook is once again dragging on the pound.
GBP/USD -0.62% at 1.1456
EUR/USD -0.2% at 0.9980
Oil jumps on China optimism.
Oil prices are moving mildly lower on Tuesday as recession worries and concerns over COVID in China hurt the demand outlook.
The COVID picture in China lacks clarity. On the one hand, optimism appears to be growing and rumours are swirling that China could be looking to end its strict zero-COVID policy. On the other hand, the Chinese health authority doubled down on its commitment to zero COVID over the weekend.
Meanwhile, cases number are at a six-month high, which means broader lockdown measures could be implemented. The fear of COVID restrictions widening is hurting the demand outlook, pulling oil prices lower.
API stockpile data is due later today.
WTI crude trades -0.74% at $90.20
Brent trades -0.65% at $97.72
Looking ahead
21:30 API crude oil stockpiles
US futures
Dow futures +0.2% at 32916
S&P futures +0.2% at 3816
Nasdaq futures +0.4% at 11029
In Europe
FTSE +0.09% at 7306
Dax +0.41% at 13590
Learn more about trading indices
Gridlock in Washington?
US stocks are pointing to modest gains on the open, extending the winning run for stocks into a third straight day as investors look ahead to the crucial midterm elections.
The latest polls suggest that the Republican party is likely to take back with House of Representatives and could potentially take back the Senate as well. Let’s not forget that Americans will be heading to the polls at a time when inflation is at multi-decade highs and a recession is looming.
Should Republicans take control of Congress, or at least the House of Representatives, it would result in gridlock in Washington, making it much harder for President Biden to push through his agenda, which includes antitrust regulations on big tech and social spending programmes, which could add to the inflationary environment.
With additional spending risks moderated, the Fed may need to do less to rein in inflation, with is good news for stocks. Additionally, historically speaking, the S&P500 has booked high annualised returns when there is a Democrat in the White House, and Republicans take control of Congress.
The results could be in quickly in the case of a massive wave of Republican support. However, there is also a realistic chance that results won’t be known until tomorrow or later in the week.
Aside from the midterm elections, the economic calendar is quiet. The main focus will be on Thursday’s CPI inflation data, which could provide fresh clues as to the likely move by the Fed in December.
Corporate news:
Lyft trades 19% lower and is flirting with all-time lows after the passenger numbers missed expectations, fueling fears that it is losing market share to larger rivals,
Disney is due to report Q4 earnings after the close. The theme parks and entertainment segment is expected to see revenue jump 39%. Disney+ streaming figures are also likely to impress, rising by 9.3 million.
Tesla is rising pre-market, rising from a yearly low as investors questioned whether Elon Musk would need to sell shares as Twitter losses mount.
Where next for the Dow Jones?
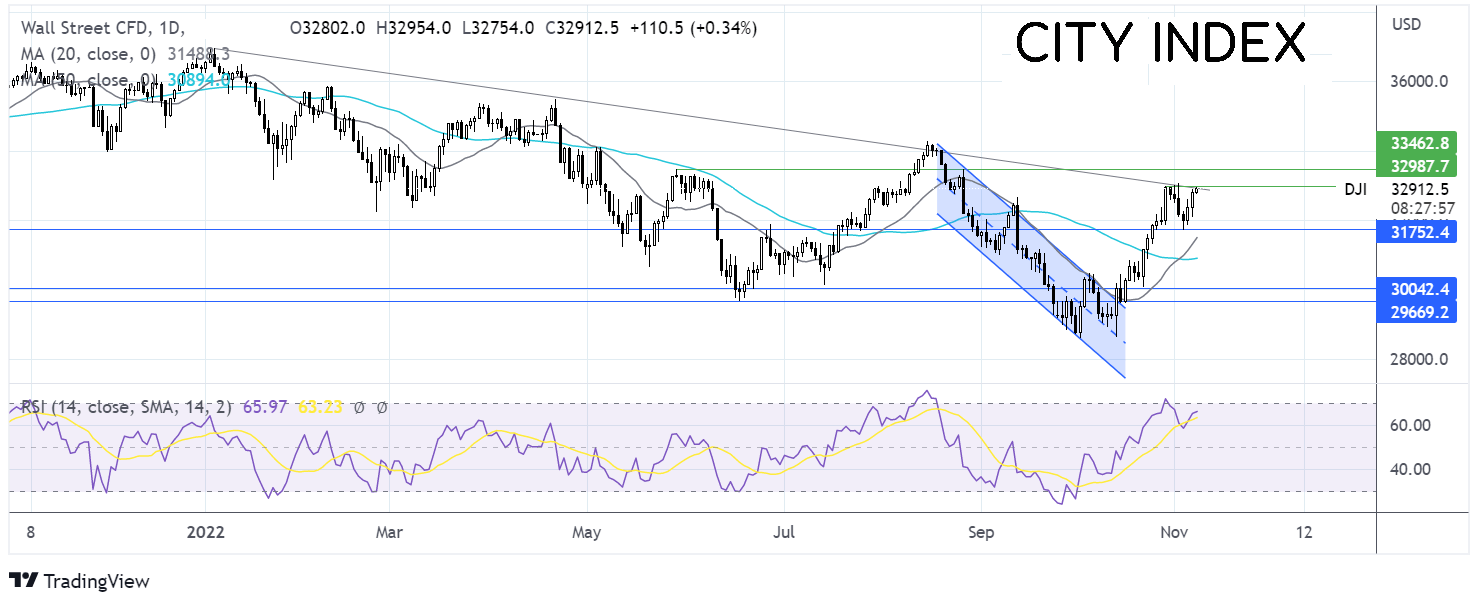
The Dow Jones is pushing higher, targeting 33,000, last week’s high, the round number and the falling trendline resistance. The RSI is over 50, and the 20 sma has crossed over the 50 sma, keeping buyers optimistic of further upside. Buyers will look for a rise over 33,000 to create a higher high before bringing 33460, the August 26 high, into focus. Sellers will look for a move below 317100 to expose the 20 sma at 31300 and the 50 sma at 30850.
FX markets – USD rises GBP falls
The USD is rising after several days of losses as attention turns to the midterm elections and political uncertainty. A gridlock in Washington could be USD-negative if fewer spending programmes are passed.
EURUSD falling on USD strength, despite retail sales coming in as expected. Sales rose 0.4% MoM in September after falling -0.3% in August. Even so, with inflation at a record high, this is unlikely to be a turning point in consumption.
GBPUSD is falling, paring some of yesterday’s strong gains. Talk of cooperation with Europe and hopes of a gas deal with the US lifted sterling yesterday. Today, the bleak outlook is once again dragging on the pound.
GBP/USD -0.62% at 1.1456
EUR/USD -0.2% at 0.9980
Oil jumps on China optimism.
Oil prices are moving mildly lower on Tuesday as recession worries and concerns over COVID in China hurt the demand outlook.
The COVID picture in China lacks clarity. On the one hand, optimism appears to be growing and rumours are swirling that China could be looking to end its strict zero-COVID policy. On the other hand, the Chinese health authority doubled down on its commitment to zero COVID over the weekend.
Meanwhile, cases number are at a six-month high, which means broader lockdown measures could be implemented. The fear of COVID restrictions widening is hurting the demand outlook, pulling oil prices lower.
API stockpile data is due later today.
WTI crude trades -0.74% at $90.20
Brent trades -0.65% at $97.72
Learn more about trading oil here.
Looking ahead
21:30 API crude oil stockpiles
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.