



US open: Stocks fall on Powell's comments GDP up next
After strong gains in the previous session, stocks are falling in the continued fallout from the Fed rate decision. US GDP data is due next.
Share this:

U
S futures
Dow futures +0.50% at 31910
S&P futures +0.93% at 3916
Nasdaq futures +1.5% at 12269
In Europe
FTSE -0.21% at 7360
Dax +0.01% at 13190
Euro Stoxx +0.12% at 3610
Meta disappoints, Apple Amazon to report after the close
US stocks are set to lower as investors continue to digest the latest Federal Reserve interest rate decision and look ahead to the US GDP data.
Yesterday the Fed hiked rates by 75 basis points, which was expected. However, Jerome Powell declined to provide guidance on the size of the next rate hike, given the amount of uncertainty in the economic outlook.
The Fed funds priced in a more dovish outlook following the press conference, with the market expecting a 50 basis point hike in September rather than 75 bps.
There is still plenty of economic data to get through between now and then, with two jobs reports and two inflation reports. So a lot could happen.
Attention now turns to the US GDP reading, which is expected to show that the US economy rebounded in Q2 by 0.4% annually after falling -1.6% in Q1. Two-quarters of contraction would mean that the US economy is already in contraction.
In corporate news:
Meta is falling lower after missing both revenue and earnings forecasts. This marked the first year-on-year revenue decline for the social media company. Meta reported EPS of $2.46 against forecasts of $2.54 on revenue of $28.8 billion on revenue of $28.9 billion.
Apple and Amazon are set to report after the close.
Where next for the S&P500?
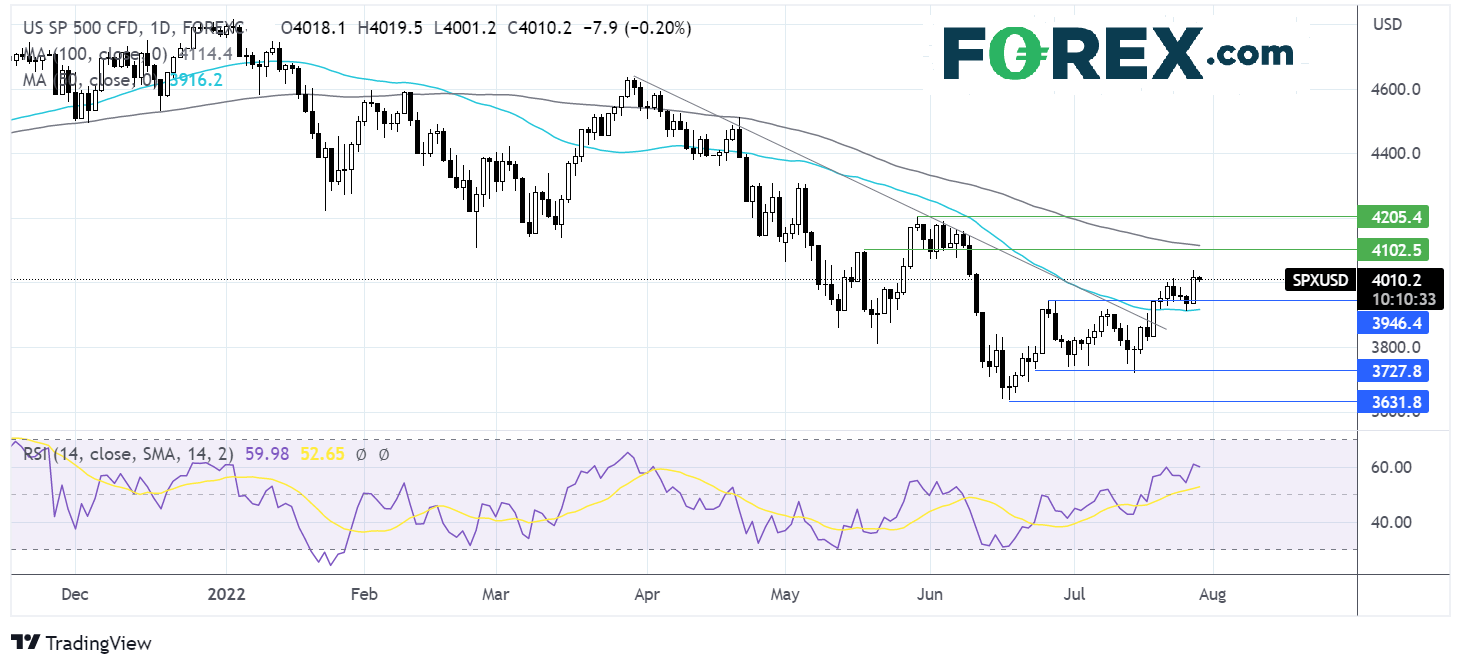
The S&P500 extended its rebound from the 2022 low of 3636. The index has risen above its 50 sma, which, combined with the bullish RSI, suggests that more upside could be on the cards. Buyers will need to rise over 4040, yesterday’s high, in order to look towards 4100 round number and expose the 100 sma at 4120. On the flip side, support can be seen at 3940, the June 27 high, and at 3910 the 50 sma, a break below here could open the door to 3735, the July low.
FX markets – USD rises, EUR falls
The initial selloff in the USD following the Fed rate decision has stalled, and the USD is rebounding higher.
EURUSD is falling after dismal eurozone consumer confidence, which tumbled by more than expected in July to -27, down from -23.8. The fall in sentiment comes as recession fears rise and amid growing concerns over the energy picture. Attention now turns to German inflation data, which is expected to ease slightly to 8.1% YoY in July, down from 8.2%.
GBP/USD is falling amid rising concerns over the health of the UK economy. The latest survey from RICS showed that the commercial real estate sector is entering or may already be in a downturn. No high-impacting UK data is due to be released, so attention turns to the BoE meeting next week.
GBP/USD -0.2% at 1.21230
EUR/USD -0.43% at 1.0150
Oil rises after inventories drop.
Oil prices are rising, extending gains from the previous session, boosting hopes of a less aggressive Federal Reserve and falling inventories.
Recession fears eased after the market interpreted the tone of the Fed at the latest Federal Reserve meeting as being slightly more dovish.
Oil prices had fallen in recent weeks on bets that aggressive Fed tightening would tip the economy into recession, hurting the demand outlook. With aggressive Fed bets being reined in the demand outlook has improved.
Separately stockpile data showed that inventories fell by 4.5 million barrels last week, more than the 1 million barrels forecast.
WTI crude trades +1.7% at $98.48
Brent trades +1.86% at $103.64
Looking ahead
13:00 German inflation
13:30 USD GDP
13:30 US initial jobless claims
US futures
Dow futures +0.50% at 31910
S&P futures +0.93% at 3916
Nasdaq futures +1.5% at 12269
In Europe
FTSE -0.21% at 7360
Dax +0.01% at 13190
Euro Stoxx +0.12% at 3610
Learn more about trading indices
Meta disappoints, Apple Amazon to report after the close
US stocks are set to lower as investors continue to digest the latest Federal Reserve interest rate decision and look ahead to the US GDP data.
Yesterday the Fed hiked rates by 75 basis points, which was expected. However, Jerome Powell declined to provide guidance on the size of the next rate hike, given the amount of uncertainty in the economic outlook.
The Fed funds priced in a more dovish outlook following the press conference, with the market expecting a 50 basis point hike in September rather than 75 bps.
There is still plenty of economic data to get through between now and then, with two jobs reports and two inflation reports. So a lot could happen.
Attention now turns to the US GDP reading, which is expected to show that the US economy rebounded in Q2 by 0.4% annually after falling -1.6% in Q1. Two-quarters of contraction would mean that the US economy is already in contraction.
In corporate news:
Meta is falling lower after missing both revenue and earnings forecasts. This marked the first year-on-year revenue decline for the social media company. Meta reported EPS of $2.46 against forecasts of $2.54 on revenue of $28.8 billion on revenue of $28.9 billion.
Apple and Amazon are set to report after the close.
Where next for the S&P500?
The S&P500 extended its rebound from the 2022 low of 3636. The index has risen above its 50 sma, which, combined with the bullish RSI, suggests that more upside could be on the cards. Buyers will need to rise over 4040, yesterday’s high, in order to look towards 4100 round number and expose the 100 sma at 4120. On the flip side, support can be seen at 3940, the June 27 high, and at 3910 the 50 sma, a break below here could open the door to 3735, the July low.

FX markets – USD rises, EUR falls
The initial selloff in the USD following the Fed rate decision has stalled, and the USD is rebounding higher.
EURUSD is falling after dismal eurozone consumer confidence, which tumbled by more than expected in July to -27, down from -23.8. The fall in sentiment comes as recession fears rise and amid growing concerns over the energy picture. Attention now turns to German inflation data, which is expected to ease slightly to 8.1% YoY in July, down from 8.2%.
GBP/USD is falling amid rising concerns over the health of the UK economy. The latest survey from RICS showed that the commercial real estate sector is entering or may already be in a downturn. No high-impacting UK data is due to be released, so attention turns to the BoE meeting next week.
GBP/USD -0.2% at 1.21230
EUR/USD -0.43% at 1.0150
Oil rises after inventories drop.
Oil prices are rising, extending gains from the previous session, boosting hopes of a less aggressive Federal Reserve and falling inventories.
Recession fears eased after the market interpreted the tone of the Fed at the latest Federal Reserve meeting as being slightly more dovish.
Oil prices had fallen in recent weeks on bets that aggressive Fed tightening would tip the economy into recession, hurting the demand outlook. With aggressive Fed bets being reined in the demand outlook has improved.
Separately stockpile data showed that inventories fell by 4.5 million barrels last week, more than the 1 million barrels forecast.
WTI crude trades +1.7% at $98.48
Brent trades +1.86% at $103.64
Learn more about trading oil here.
Looking ahead
13:00 German inflation
13:30 USD GDP
13:30 US initial jobless claims
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.