



US open: Stocks rise ahead of ISM services data
Stocks rise after three weeks of losses. US ISM non-manufacturing data up next.
Share this:

US futures
Dow futures +0.42% at 31510
S&P futures +0.4% at 3948
Nasdaq futures +0.43% at 12167
In Europe
FTSE +0.34% at 73283
Dax +0.2% at 12960
Euro Stoxx -1.7% at 3670
A positive start after weeks of losses
US stocks are set to open higher after the Labor Day long weekend. The upbeat mood is well needed after three straight weeks of declines.
Stocks have been under pressure over the last month as Jerome Powell and Fed adopted a more hawkish stance, warning that the Fed will hike rates and keep them elevated to stamp out inflation.
The Federal Reserve is due to meet again later this month, and the market is pricing in a 68% probability of a 75 basis point rate hike; this is down slightly from 74% last week, following the non-farm payroll report.
While the NFP saw 315k jobs added, it also saw the participation rate rise, which should help ease the very tight labor market bringing wage growth down.
Looking ahead, attention will be on the release of the ISM non-manufacturing PMI data, which is expected to show a slight slowdown in growth to 55.5 from 56.7 in July. A strong report would be in contrast to the S&P Global US
Corporate news:
CVS rises pre-market after agreeing to buy Signify Health for $8 billion in cash. This will enable one of the largest healthcare companies to provide healthcare in patients’ homes.
Where next for the S&P500?
FX markets – USD rises, EUR falls
The USD is rising, tracking treasury yields higher. The USD rallied to a 2-year high in the previous session and is holding those gains ahead of the US data shortly.
EUR/USD is edging lower after German factory orders fell by more than expected in July, dropping -1.1%, after falling -0.4% in the previous month. This marked the 6th straight month that industrial orders declined. Concerns over energy security continued to weigh on the EUR.
GBP/USD has rebounded from yesterday’s 2.5-year low, boosted by reports of an energy bailout. The new PM Liz Truss drafts a £130 billion plan to freeze energy prices for 18 months and drafts a £40 billion energy support plan for businesses. These supportive measures could enable the BoE to hike rates more aggressively, which is lifting the pound.
GBP/USD +0.5% at 1.1575
EUR/USD -0.04% at 0.9923
Oil falls on demand concerns
Oil is falling, snapping a three-day winning run. Oil heads back towards August lows as demand fears return, overshadowing concerns over the surprising supply cut from OPEC+ in the previous session.
New COVID lockdowns in China add to rising concerns over high inflation and more aggressive rate hikes in Europe and the US.
Yesterday OPEC+ cut output by 100k bpd, reversing the decision to raise output by the same amount in September.
WTI crude trades -2.6% at $86.96
Brent trades -2.3% at $92.70
Looking ahead
14:45 US services PMI
15:00 US ISM services PMI
US futures
Dow futures +0.42% at 31510
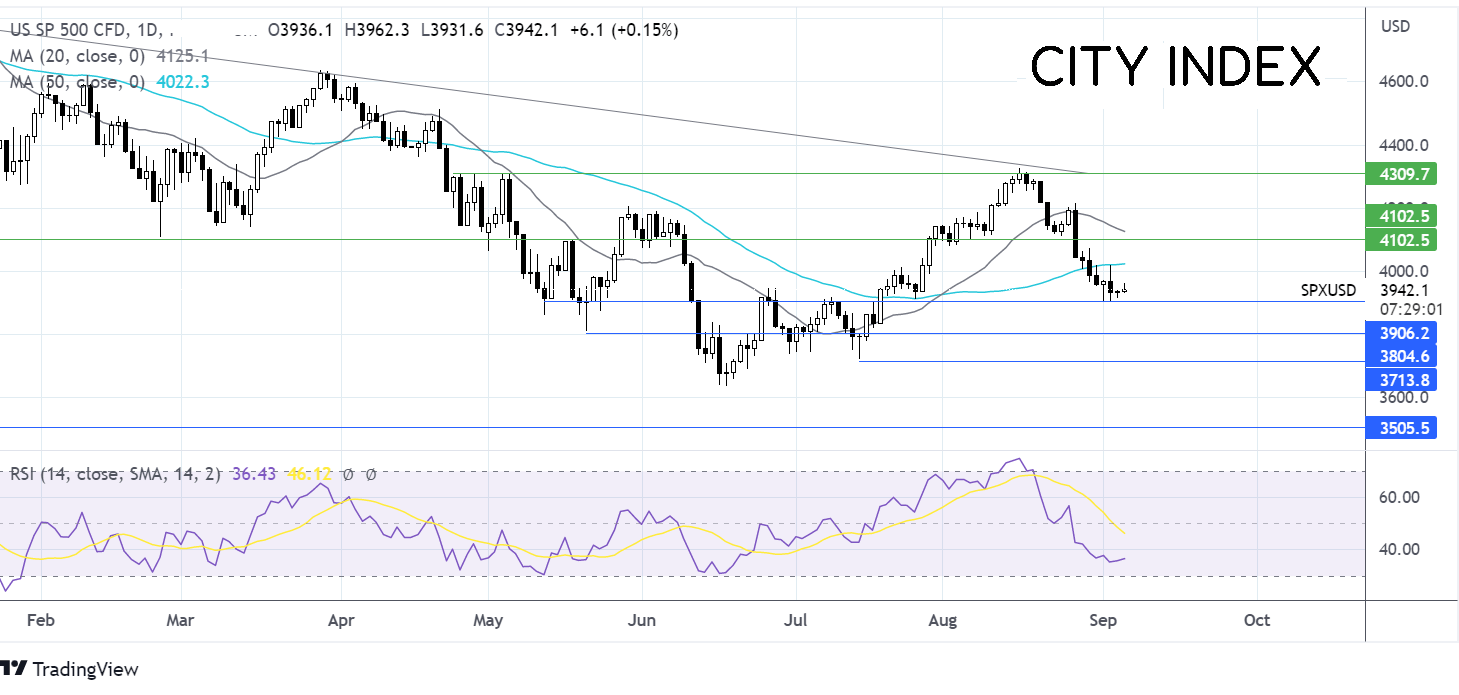
S&P futures +0.4% at 3948
Nasdaq futures +0.43% at 12167
In Europe
FTSE +0.34% at 73283
Dax +0.2% at 12960
Euro Stoxx -1.7% at 3670
A positive start after weeks of losses
US stocks are set to open higher after the Labor Day long weekend. The upbeat mood is well needed after three straight weeks of declines.
Stocks have been under pressure over the last month as Jerome Powell and Fed adopted a more hawkish stance, warning that the Fed will hike rates and keep them elevated to stamp out inflation.
The Federal Reserve is due to meet again later this month, and the market is pricing in a 68% probability of a 75 basis point rate hike; this is down slightly from 74% last week, following the non-farm payroll report.
While the NFP saw 315k jobs added, it also saw the participation rate rise, which should help ease the very tight labor market bringing wage growth down.
Looking ahead, attention will be on the release of the ISM non-manufacturing PMI data, which is expected to show a slight slowdown in growth to 55.5 from 56.7 in July. A strong report would be in contrast to the S&P Global US
Corporate news:
CVS rises pre-market after agreeing to buy Signify Health for $8 billion in cash. This will enable one of the largest healthcare companies to provide healthcare in patients’ homes.
Where next for the S&P500?
FX markets – USD rises, EUR falls
The USD is rising, tracking treasury yields higher. The USD rallied to a 2-year high in the previous session and is holding those gains ahead of the US data shortly.
EUR/USD is edging lower after German factory orders fell by more than expected in July, dropping -1.1%, after falling -0.4% in the previous month. This marked the 6th straight month that industrial orders declined. Concerns over energy security continued to weigh on the EUR.
GBP/USD has rebounded from yesterday’s 2.5-year low, boosted by reports of an energy bailout. The new PM Liz Truss drafts a £130 billion plan to freeze energy prices for 18 months and drafts a £40 billion energy support plan for businesses. These supportive measures could enable the BoE to hike rates more aggressively, which is lifting the pound.
GBP/USD +0.5% at 1.1575
EUR/USD -0.04% at 0.9923
Oil falls on demand concerns
Oil is falling, snapping a three-day winning run. Oil heads back towards August lows as demand fears return, overshadowing concerns over the surprising supply cut from OPEC+ in the previous session.
New COVID lockdowns in China add to rising concerns over high inflation and more aggressive rate hikes in Europe and the US.
Yesterday OPEC+ cut output by 100k bpd, reversing the decision to raise output by the same amount in September.
WTI crude trades -2.6% at $86.96
Brent trades -2.3% at $92.70
Learn more about trading oil here.
Looking ahead
14:45 US services PMI
15:00 US ISM services PMI
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.