



US open: Stocks rise snapping a 5-day losing run
Stocks rise as he market mood improves for now. USD eases lower.
Share this:

US futures
Dow futures +1% at 29578
S&P futures +1.3% at 3700
Nasdaq futures +1.5% at 11430
In Europe
FTSE +0.7% at 7043
Dax +0.8% at 12330
Market mood improves for now
US stocks are heading higher after steep losses over the past week, which saw the Dow Jones join the S&P500 and the Nasdaq in bear market territory.
Stocks have sold off sharply as the Fed has hiked interest rates aggressively and indicated that there are plenty more to come. Recession fears are growing, which is making stock picking that much harder. Whilst stocks are edging higher, this is more a pause in the market selloff rather than the start of anything more positive.
The fundamentals remain the same, and a recession is looking increasingly more likely. When the likes of Goldman Sachs downgrade global shares to underweight for over three months, we can expect the final quarter of the year to be a shocker.
Blackrock has adopted a similar stance, saying that the recession isn’t priced in yet. A soft landing is looking increasingly unlikely.
The sharp selloff in bonds historically points to a selloff in equities. With bond yields so high with ess relative risk, there appears little incentive to buy equities.
Looking ahead, US consumer confidence will be in focus. Expectations are for a tick higher in morale to 104 in September, after rising in August.
Corporate news:
Tesla rises pre-market as management push to deliver as many electric vehicles as possible before the of the third quarter.
Where next for the Dow Jones?
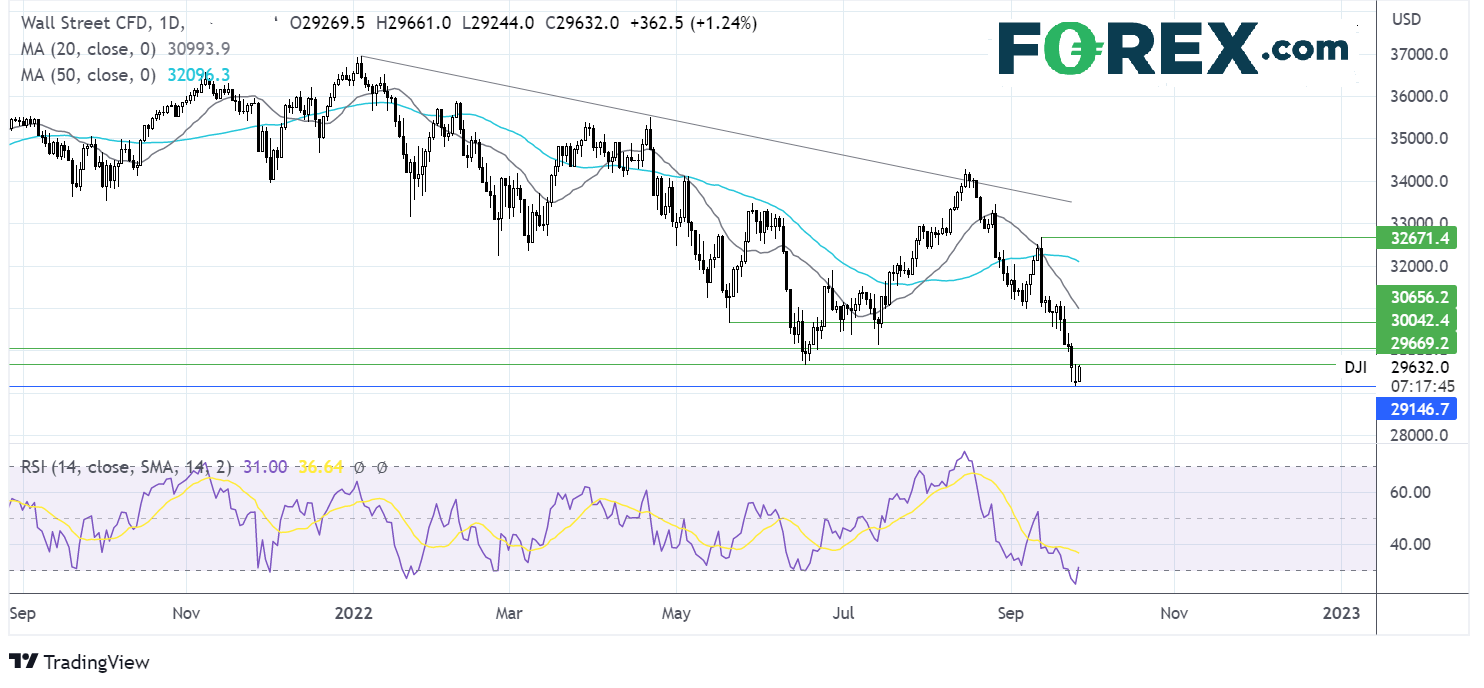
The Dow Jones has found a floor at 12660, yesterday’s low, and is attempting to rise. The move higher is pulling the RSI out of oversold territory. Buyers would need to rise above resistance at 29600, the June low, to attract 30000 psychological level. It would take a move over 30660 to negate the near term selloff. Meanwhile, sellers will look for a move below 29150, the 2022 low to extend the bearish trend.
FX markets – USD eases, GBP rebounds
The USD is easing back from a 20-year high reached in the previous session as risk sentiment improves, increasing safe have outflows. Bulls are pausing for breath after the greenback rose to a fresh 20-year high yesterday.
EUR/USD is rising, boosted by the improved market mood. Data has been in short supply. The euro falls away from session highs after reports of sabotage on the Nord Stream pipeline, which sends European gas prices higher.
GBPUSD rises from an all-time low after the Treasury and the BoE attempted to calm the selloff. Both entities acknowledged the turmoil in the market, but neither was prepared to take action. As a result, the rally in the pound could be limited.
GBP/USD +1% at 1.08
EUR/USD +0.35% at 0.9640
Oil rebounds from 9-months.
Oil prices rose from a 9-month low, helped higher by the softening in the US dollar amid the hurricane in the Gulf of Mexico and as attention turns to next week’s OPEC+ meeting.
The supply side of the equation is in focus now, lending support to the price. BP and Chevron have shut production at offshore platforms in the Gulf of Mexico as Hurricane Ian approaches. Furthermore, the recent decline in the price of oil could mean that OPEC+ is more likely to intervene and cut production again.
API crude oil stockpiles are expected to rise by 300,000 barrels. The data is due later.
WTI crude trades +1.67% at $77.70
Brent trades +1.6% at $84.50
Looking ahead
15:00 US Consumer confidence
21:30 API oil stockpiles
US futures
Dow futures +1% at 29578
S&P futures +1.3% at 3700
Nasdaq futures +1.5% at 11430
In Europe
FTSE +0.7% at 7043
Dax +0.8% at 12330
Learn more about trading indices
Market mood improves for now
US stocks are heading higher after steep losses over the past week, which saw the Dow Jones join the S&P500 and the Nasdaq in bear market territory.
Stocks have sold off sharply as the Fed has hiked interest rates aggressively and indicated that there are plenty more to come. Recession fears are growing, which is making stock picking that much harder. Whilst stocks are edging higher, this is more a pause in the market selloff rather than the start of anything more positive.
The fundamentals remain the same, and a recession is looking increasingly more likely. When the likes of Goldman Sachs downgrade global shares to underweight for over three months, we can expect the final quarter of the year to be a shocker.
Blackrock has adopted a similar stance, saying that the recession isn’t priced in yet. A soft landing is looking increasingly unlikely.
The sharp selloff in bonds historically points to a selloff in equities. With bond yields so high with ess relative risk, there appears little incentive to buy equities.
Looking ahead, US consumer confidence will be in focus. Expectations are for a tick higher in morale to 104 in September, after rising in August.
Corporate news:
Tesla rises pre-market as management push to deliver as many electric vehicles as possible before the of the third quarter.
Where next for the Dow Jones?
The Dow Jones has found a floor at 12660, yesterday’s low, and is attempting to rise. The move higher is pulling the RSI out of oversold territory. Buyers would need to rise above resistance at 29600, the June low, to attract 30000 psychological level. It would take a move over 30660 to negate the near term selloff. Meanwhile, sellers will look for a move below 29150, the 2022 low to extend the bearish trend.

FX markets – USD eases, GBP rebounds
The USD is easing back from a 20-year high reached in the previous session as risk sentiment improves, increasing safe have outflows. Bulls are pausing for breath after the greenback rose to a fresh 20-year high yesterday.
EUR/USD is rising, boosted by the improved market mood. Data has been in short supply. The euro falls away from session highs after reports of sabotage on the Nord Stream pipeline, which sends European gas prices higher.
GBPUSD rises from an all-time low after the Treasury and the BoE attempted to calm the selloff. Both entities acknowledged the turmoil in the market, but neither was prepared to take action. As a result, the rally in the pound could be limited.
GBP/USD +1% at 1.08
EUR/USD +0.35% at 0.9640
Oil rebounds from 9-months.
Oil prices rose from a 9-month low, helped higher by the softening in the US dollar amid the hurricane in the Gulf of Mexico and as attention turns to next week’s OPEC+ meeting.
The supply side of the equation is in focus now, lending support to the price. BP and Chevron have shut production at offshore platforms in the Gulf of Mexico as Hurricane Ian approaches. Furthermore, the recent decline in the price of oil could mean that OPEC+ is more likely to intervene and cut production again.
API crude oil stockpiles are expected to rise by 300,000 barrels. The data is due later.
WTI crude trades +1.67% at $77.70
Brent trades +1.6% at $84.50
Learn more about trading oil here.
Looking ahead
15:00 US Consumer confidence
21:30 API oil stockpiles
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.


Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.