




Vaccine Hopes Earnings Optimism Boost Stocks
Europe points to a strong start boosted by coronavirus treatment hopes and cautious optimism ahead of US earning season, which kicks off this week.
Share this:
Asian stocks advanced overnight and Europe is looking towards a strong start out of the blocks on Monday, boosted by coronavirus treatment hopes and cautious optimism ahead of US earning season, which kicks off this week.
Drug news lifts sentiment
On Friday, covid drug news sent stocks rallying into the weekend. A study on Remdesivir showed that the drug reduced coronavirus fatalities by 62%. Boosting sentiment further Pfizer and BioNTech announced hat their vaccine could be approved by the FDA as soon as December. A vaccine is the quickest and surest way for the economy to bounce back to pre-corona levels, which explains why the market is so sensitive to any vaccine news flow.
Low bar for earning season
The mood remains upbeat as the new week kicks off and US earning season moves into focus. Given that in April and some of May the US was in full scale lock down, second quarter results bore the brunt of the coronavirus crisis. However, expectations for all except the stay at home stocks are very low. With the bar set so low, the chances of better than forecast results improves.
JP Morgan, Citigroup and Wells Fargo are first to set the scene with Goldman Sachs, Netflix and Johnson & Johnson helping to give further insights as to the coronavirus impact later in the week. Earnings will test optimism which has driven the rebound from March lows.
Rising US covid cases overshadowed
Cautious optimism surrounding earnings season and vaccine hopes is overshadowing rising covid numbers, particularly in the US. On Sunday Florida experienced a record number of daily covid-19 cases, whilst the US continues to see daily increases of around 60,000. Whilst coronavirus cases are surging, the markets aren’t considering the increase to be sufficient to force lockdown restrictions to be placed back on the economy.
Whilst riskier currencies and assets such as equities and are in favour, the US Dollar is once again trading on the back foot as investors shun its safe haven properties.
The economic calendar is quiet today, with just a speech from BoE Andrew Bailey. However, tomorrow sees a sharp pick up in data releases with UK GDP expected to be a highlight. After contracting -20.4% whilst lockdown was in full flow, economic growth is expected to show some signs of recovery in May as lockdown measures started to ease.
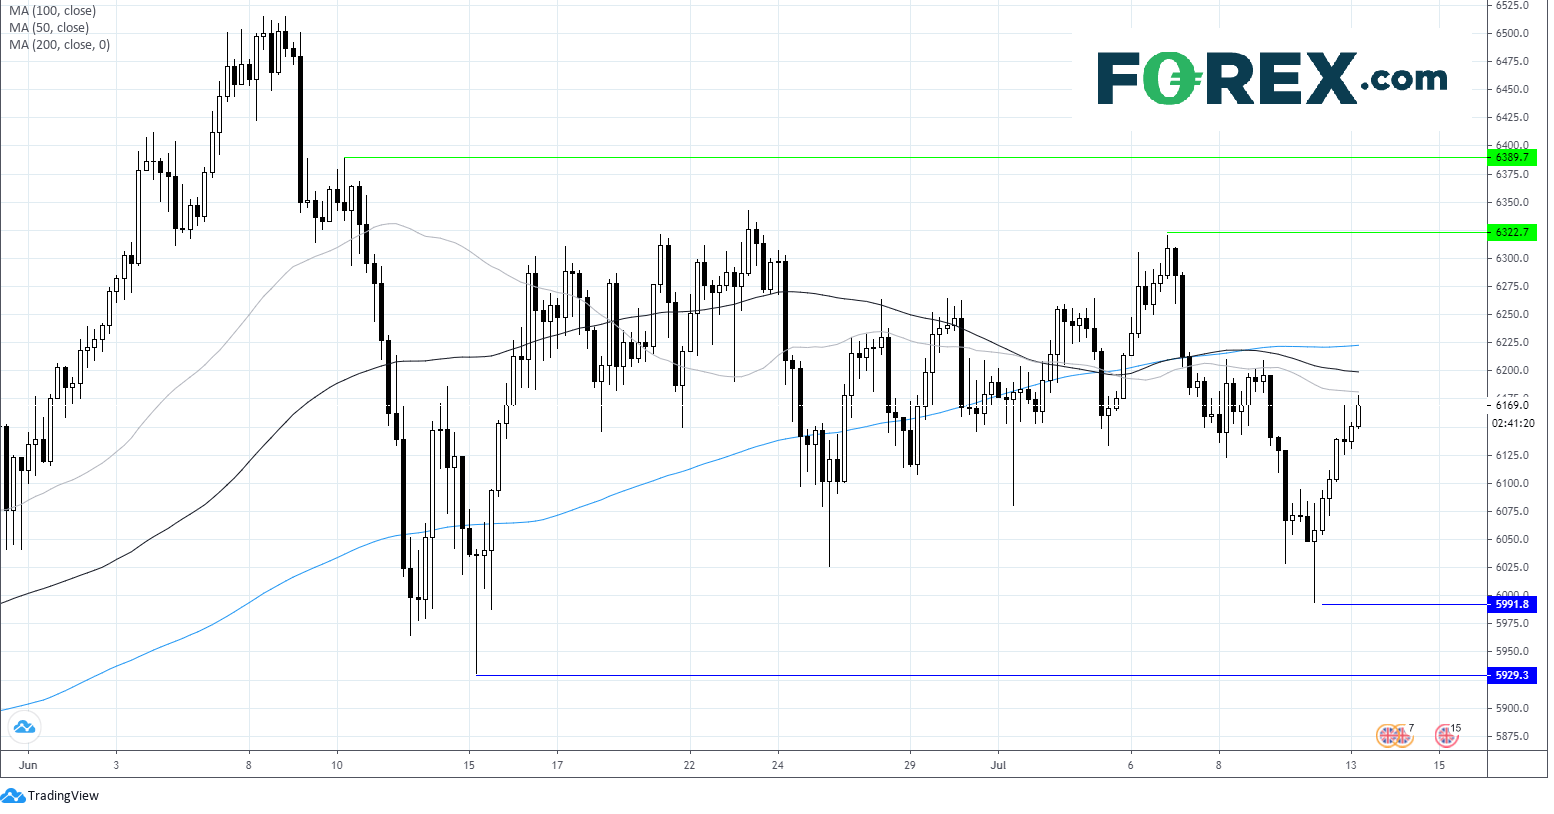
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.