







Weekly COT Report Sterling Traders The Least Bearish In Three Months
A summary of the weekly Commitment of Traders Report (COT) from CFTC to show market positioning among large speculators.
Share this:

As of Tuesday 8th October:
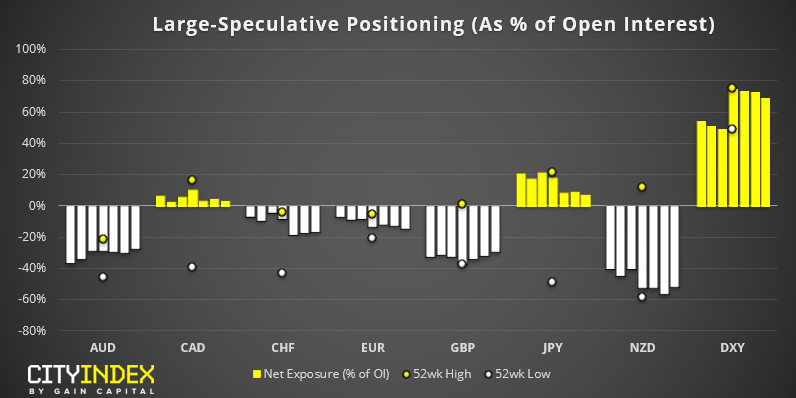
- Traders increased net-long exposure for a 4th consecutive week by $0.8 billion.
- The Euro saw the largest weekly change among FX majors, seeing net-short exposure increase by 9.4k contracts.
- Large speculators were their least bearish on the British pound in 3 months.
- Large speculators were their least bullish on the Japanese yen in 2 months.
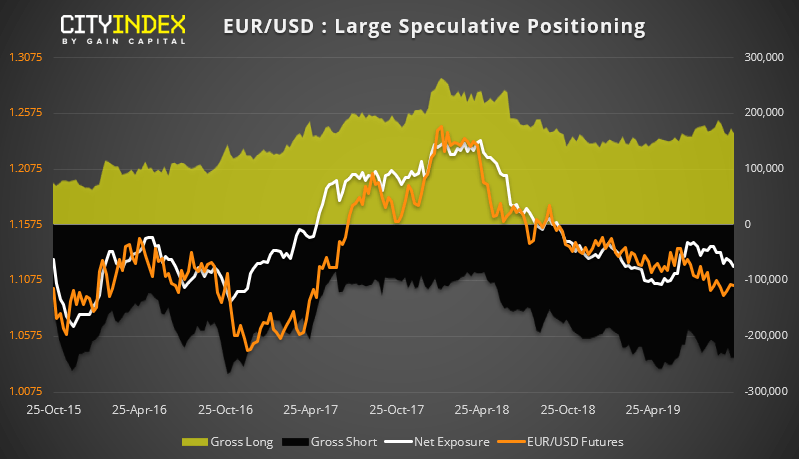
EUR: Net-short exposure dropped to its most bearish level in 4-months. Gross short exposure remains near a 4-month high, although last week’s increase of bearishness was a function of both longs and shorts closing out. Yet, whilst positioning doesn’t scream a sentiment extreme, EUR/USD rallied nearly 1% between Tuesday’s close (when the report was compiled) and Friday’s high on progress with US-China trade talks. So, is the low in? Perhaps, but I’m not currently convinced from this alone. There’s still a long way to go on trade talks and traders remains net-short on the Euro. So until we see a material pick-up with gross longs and closure of shorts, it’s probably better to assume the trend remains bearish.
GBP: Over the past three weeks we’ve seen gross longs increase and gross shorts decreased; albeit by a small amount but it has allowed net-short exposure to fall to a 3-month low. Given the 4% rally on cable over Thursday and Friday on Brexit developments, we’d expect net-short exposure to fall notably, assuming traders still think there’s chance of a deal before 31st of October. And looking at the cycles of net-short exposure, it’s plausible that the low was in around mid-August.
As of Tuesday 8th October:
- WTI Traders reduced net-long exposure to a 4-month low.
- Bullish positioning on Palladium was at its highest level in 8-months.
- Net-short exposure to copper was at its most bearish level in 8-weeks.
- Only minor adjustments to gold positioning sees net-long exposure remain stubbornly high.
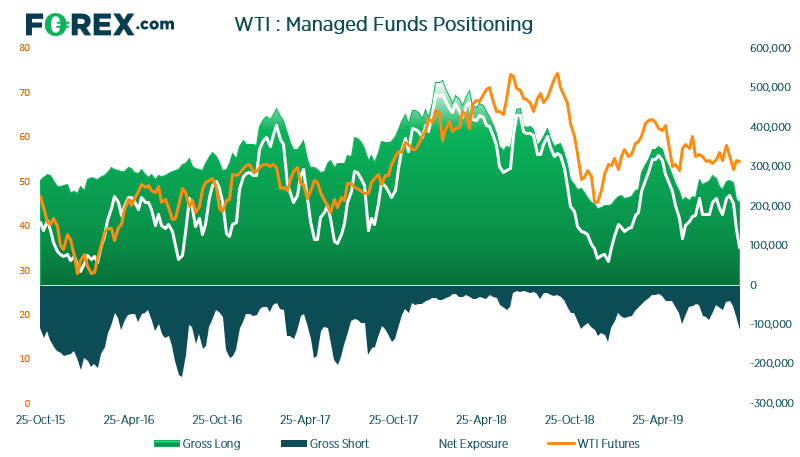
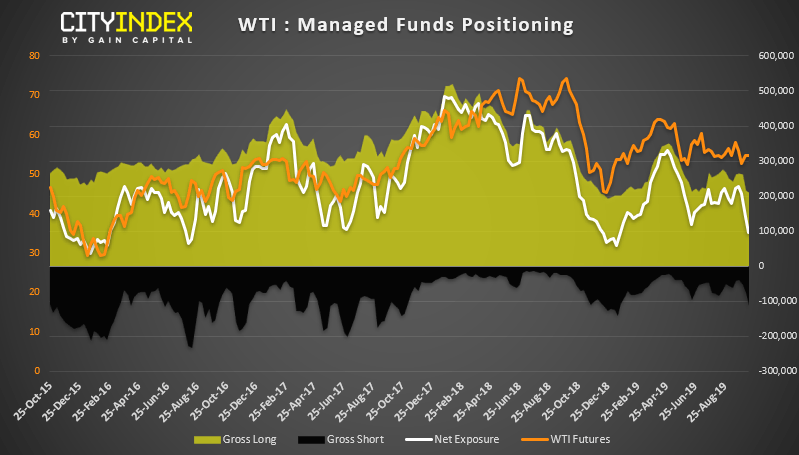
WTI: Net-long exposure declined for a fourth consecutive week, taking bullish exposure for large speculators to their least bullish in 4-months. However, managed funds (pictured above) saw bullish net-long exposure fall to a 9-month low. Gross shorts are at their most bearish level since January, adding +36.9k contracts last week alone (or over +75k over the past three weeks) so some funds may have been squeezed following the missile attack on an Iranian oil tanker on Friday. Yet with volatility remaining relatively low following the attack, some funds may see the bounce as a reason to add to shorts unless geopolitical tensions rise, or we see another supply shock to make prices truly rally.
Related analysis:
Commencing Phase One of US-China Trade Deal
Week Ahead: US-China Trade and Brexit Optimism Aftermath
WTI Breaks Above 54 Following Missile Attack On Iranian Oil Vessel
As of Tuesday 8th October:
- Traders increased net-long exposure for a 4th consecutive week by $0.8 billion.
- The Euro saw the largest weekly change among FX majors, seeing net-short exposure increase by 9.4k contracts.
- Large speculators were their least bearish on the British pound in 3 months.
- Large speculators were their least bullish on the Japanese yen in 2 months.
EUR: Net-short exposure dropped to its most bearish level in 4-months. Gross short exposure remains near a 4-month high, although last week’s increase of bearishness was a function of both longs and shorts closing out. Yet, whilst positioning doesn’t scream a sentiment extreme, EUR/USD rallied nearly 1% between Tuesday’s close (when the report was compiled) and Friday’s high on progress with US-China trade talks. So, is the low in? Perhaps, but I’m not currently convinced from this alone. There’s still a long way to go on trade talks and traders remains net-short on the Euro. So until we see a material pick-up with gross longs and closure of shorts, it’s probably better to assume the trend remains bearish.
GBP: Over the past three weeks we’ve seen gross longs increase and gross shorts decreased; albeit by a small amount but it has allowed net-short exposure to fall to a 3-month low. Given the 4% rally on cable over Thursday and Friday on Brexit developments, we’d expect net-short exposure to fall notably, assuming traders still think there’s chance of a deal before 31st of October. And looking at the cycles of net-short exposure, it’s plausible that the low was in around mid-August.
As of Tuesday 8th October:
- WTI Traders reduced net-long exposure to a 4-month low.
- Bullish positioning on Palladium was at its highest level in 8-months.
- Net-short exposure to copper was at its most bearish level in 8-weeks.
- Only minor adjustments to gold positioning sees net-long exposure remain stubbornly high.
WTI: Net-long exposure declined for a fourth consecutive week, taking bullish exposure for large speculators to their least bullish in 4-months. However, managed funds (pictured above) saw bullish net-long exposure fall to a 9-month low. Gross shorts are at their most bearish level since January, adding +36.9k contracts last week alone (or over +75k over the past three weeks) so some funds may have been squeezed following the missile attack on an Iranian oil tanker on Friday. Yet with volatility remaining relatively low following the attack, some funds may see the bounce as a reason to add to shorts unless geopolitical tensions rise, or we see another supply shock to make prices truly rally.
Related analysis:
Commencing Phase One of US-China Trade Deal
Week Ahead: US-China Trade and Brexit Optimism Aftermath
WTI Breaks Above 54 Following Missile Attack On Iranian Oil Vessel
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.