



Weekly Equities Outlook: Alphabet, Tesla, Intel
US earnings season turns towards tech.
Share this:
Alphabet Q2 Earnings Preview
Google parent Alphabet is due to report Q2 2026 earnings after the market closes on July 22, with investors focusing on three key themes: Google Cloud growth, AI spending, and the progress of Gemini.
Wall Street expects revenue of $116.8 billion, up 21% year-on-year, broadly matching the pace of growth seen in Q1. Earnings per share are forecast to come in at $2.87, representing 24.2% annual growth.
Google Cloud remains Alphabet's primary growth engine and is expected to be the main driver of investor sentiment. Cloud revenue grew 63% in Q1, while the backlog almost doubled from the previous quarter to more than $460 billion, highlighting robust demand for cloud computing and AI services. Investors will be looking for signs that this momentum is continuing. Ultimately, the key question is whether AI is generating enough growth in Google Cloud to justify Alphabet's aggressive investment strategy.
AI spending will also remain firmly in focus. Alphabet has been investing heavily in data centres and AI infrastructure to support future growth. Capital expenditure more than doubled year-on-year to $35.7 billion in the first quarter, and management expects to invest between $180 billion and $190 billion during 2026. While these investments are designed to strengthen Alphabet's competitive position, they have also weighed on free cash flow, leaving investors looking for evidence that they are beginning to generate meaningful returns. Positive commentary around the company's AI strategy could support the share price, while another step up in capital expenditure may unsettle investors.
Gemini will be another major talking point. Google's AI platform has made solid progress over the past two quarters, narrowing the gap with OpenAI and Anthropic. Gemini's mobile user base rose 295% year-on-year to 118 million users, while ChatGPT remains the market leader with 441 million daily active users, although growth has largely plateaued since May. Investors will be looking for further signs that Gemini 3.5 Pro is gaining traction and helping Google capture AI market share.
Overall, analysts maintain a positive view on Alphabet. The stock carries a Strong Buy consensus rating, with 29 Buy recommendations and 5 Holds over the past three months. The average analyst price target stands at $435, implying around 17.5% upside from current levels.
How to Trade Alphabet Earnings
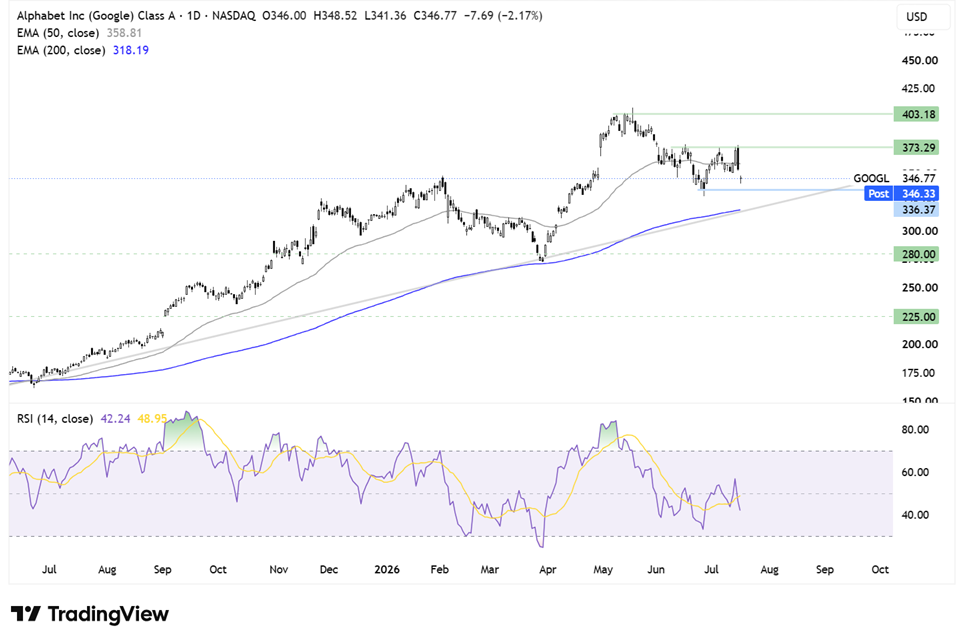
Alphabet continues to trade above its 200-day EMA and long-term rising trendline, keeping the broader trend constructive. However, after failing to hold above the $400 record high, the share price has pulled back and now trades below the 50-day EMA, suggesting the near-term technical picture has weakened.
With the RSI below 50, sellers will look for a move towards $340, the June low. A break below this level would expose the 200-day EMA and rising trendline support around $317.
On the upside, buyers would first need to reclaim the 50-day EMA near $360. A move above this level would bring $373, the July and June 15 swing highs, into focus before attention turns back to the $400 record high.
Tesla Q2 Earnings Preview
Tesla is due to report Q2 earnings after the market closes on July 22.
Wall Street expects revenue of $25.31 billion and earnings per share of $0.50.
Tesla has already reported stronger-than-expected Q2 deliveries of 480,126 vehicles, comfortably beating consensus forecasts by around 18%. The key question now is whether those stronger deliveries translated into revenue growth without sacrificing profitability.
The delivery beat comes at a time when Tesla's core EV business has faced growing concerns over slowing demand and intensifying competition. However, the stronger delivery figures suggest those concerns may have been overstated.
Margins could prove to be the key swing factor for the earnings report. Investors remain concerned that aggressive price cuts and incentives used to stimulate demand may have squeezed profitability. Gross margin deterioration has been one of Tesla's biggest headwinds in recent quarters, meaning weaker margins could offset the positive impact of stronger deliveries.
Beyond the core automotive business, Tesla's longer-term growth story continues to broaden.
The rollout of its robotaxi service continues, with operations expanding into Miami, while its energy storage division is steadily emerging as another high-margin growth business. Progress on Full Self-Driving and Optimus also continues to support the longer-term investment case, highlighting that Tesla's future increasingly extends beyond electric vehicles alone.
Wall Street's consensus rating remains Hold. If Tesla delivers healthy margins alongside encouraging updates on its emerging growth businesses, the shares could respond positively. However, disappointing margins or renewed concerns surrounding valuation could weigh on the stock.
How to Trade Tesla Earnings
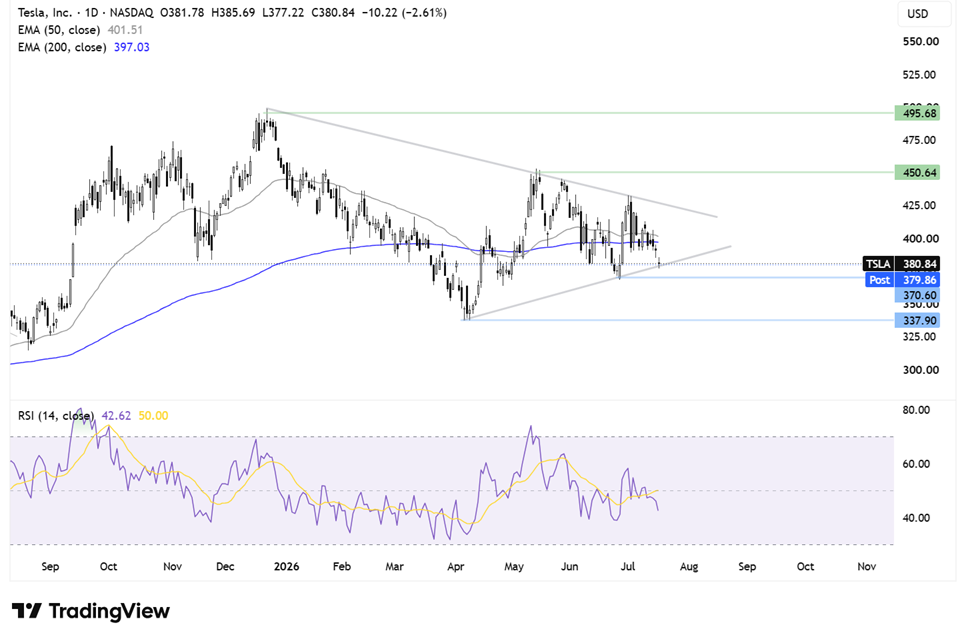
Tesla continues to trade within a symmetrical triangle pattern.
The share price failed at falling trendline resistance around $425 before pulling back, breaking below both the 50-day and 200-day EMAs and testing the rising trendline support.
A break below this support would expose the June low at $368, opening the door towards the 2026 low at $337.
Should the trendline hold, buyers would first need to reclaim the 200-day EMA around $400. A move above this level would bring the falling trendline resistance near $427 into focus before attention turns towards $450.
Intel Q2 Earnings Preview
Intel is due to report Q2 earnings after the market closes on July 23.
Wall Street expects earnings per share of $0.10, compared with a loss of $0.26 a year earlier. Revenue is forecast to rise to $14.41 billion, representing 12% annual growth.
The key driver this quarter is expected to be Intel's Data Center and AI business, which is forecast to deliver its strongest sequential revenue growth in a decade as AI-related demand continues to accelerate.
While Nvidia dominates the AI GPU market, growing AI workloads also require high-performance CPUs, networking infrastructure and advanced packaging, areas where Intel is also well positioned.
Custom AI processors represent another important growth opportunity. Intel's custom AI chip business has now surpassed $1 billion in annual revenue, providing another avenue for future expansion.
However, supply constraints remain a potential headwind. Although demand appears robust, manufacturing capacity limitations and inventory shortages could restrict near-term revenue growth.
How to Trade Intel Earnings
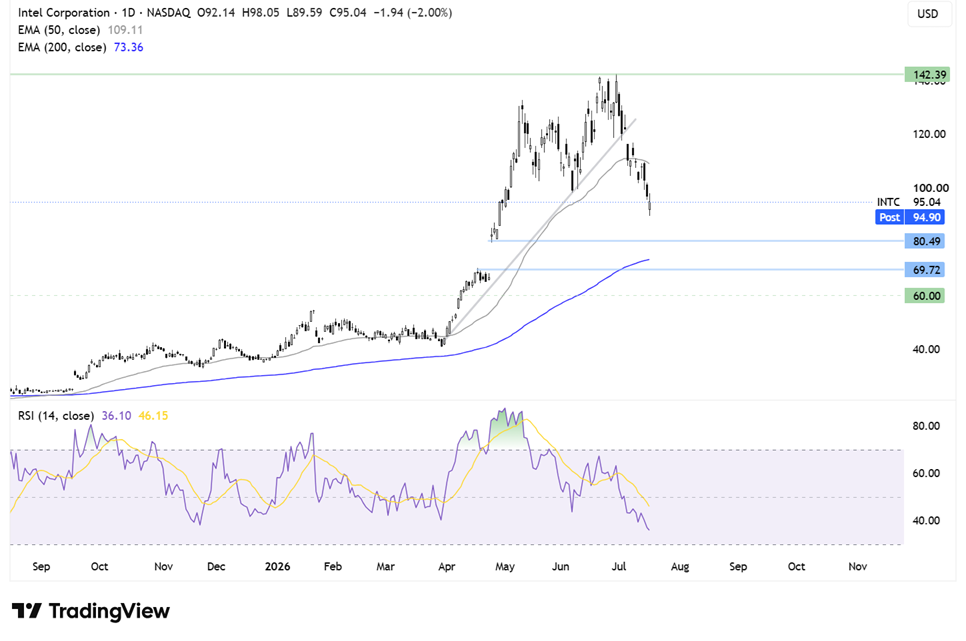
Intel failed to hold above its record high around $142 before pulling back sharply, breaking below its rising trendline and the 50-day EMA to a low of $89.50.
With the RSI below 50, the technical picture continues to favour sellers.
A break below $80, the April 27 low, would expose the 200-day EMA at $73.30, before bringing the $70 support level into focus.
To improve the outlook, buyers would first need to reclaim the 50-day EMA, with a move back above the broken trendline helping to signal that bullish momentum is returning.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Weekly Equities Forecast: Costco, JD Sports & Strategy
Earnings Costco, JD Sports report earnings and crypto stocks are in focus with after Friday's SEC announcement which boosted BTC.
Weekly Equities Outlook: JPMorgan, Next and BP
JPMorgan in focus with the Fed rate decision. Next keeps consumer discretionary under the spotlight with the BoE rate decision. BP and energy stocks supported by elevated oil prices.
Weekly Equities Outlook: Oracle, Adobe, Macy’s
Oracle, Adobe and Macy's report this week.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.