



Will the ECB get the supercharged EUR under control - test
The ECB is due to make its monetary policy announcement on Thursday 10th December. at 12:45 GMT. After Christine Lagarde already pre-committed to additional easing in the October meeting, the ECB could struggle to keep the EUR in check.
Share this:

The ECB is due to make its monetary policy announcement on Thursday 10th December at 12:45 GMT.
Expectations are running high after Christine Lagarde already pre-committed to additional easing in the October meeting. €500 billion in QE purchases and extremely generous loans to banks are widely expected and priced in. Sinking to the Euro could take a lot more.
Why ease?
In light of second national lockdowns in the likes of France and Germany the reasons for easing monetary policy further are clear; growth appears to be struggling in the final quarter. PMIs have pointed to resilience in the manufacturing sector however, the service sector has tumbled deep into contraction over the quarter. The composite PMI which gauges business activity across the service & manufacturing sector has also contracted each month since September.
In light of second national lockdowns in the likes of France and Germany the reasons for easing monetary policy further are clear; growth appears to be struggling in the final quarter. PMIs have pointed to resilience in the manufacturing sector however, the service sector has tumbled deep into contraction over the quarter. The composite PMI which gauges business activity across the service & manufacturing sector has also contracted each month since September.
The ECB’s previous forecast of 3% QoQ growth in Q4 now looks overly optimistic. A significant downward revision is expected. That said the latest vaccine developments could see an upward revision to H2 GDP 2021.
Lackluster inflation has been a headache for the ECB and is expected to remain weak going forwards, which is only aggravated further by the supercharged Euro.
EUR strength in focus
With the EUR pushing higher even though the ECB are set to ease it could be difficult for the central to reverse the current EUR/USD uptrend despite. The bearish bias on the US Dollar is proving to be too strong. In fact there could be a bigger risk of the ECB under delivering in the press conference by way of a weak forward guidance past December, which could well lift the common currency.
The meeting comes as the Euro has been hovering around 32 month highs. However, the trade weighted EUR trades around its 2009 peak. A strong currency can not only restrict economic growth but can also hold back inflation and with disinflation of -0.3% the ECB could do without a strong Euro.
With the EUR pushing higher even though the ECB are set to ease it could be difficult for the central to reverse the current EUR/USD uptrend despite. The bearish bias on the US Dollar is proving to be too strong. In fact there could be a bigger risk of the ECB under delivering in the press conference by way of a weak forward guidance past December, which could well lift the common currency.
The meeting comes as the Euro has been hovering around 32 month highs. However, the trade weighted EUR trades around its 2009 peak. A strong currency can not only restrict economic growth but can also hold back inflation and with disinflation of -0.3% the ECB could do without a strong Euro.
Over-delivering?
If the central bank is looking to pull down the Euro an above consensus QE purchase of €750 billion or even a rate cut could do the job. However recent commentary suggests that the ECB isn’t there yet.
Let’s not forget that a deep divide between the ECB doves and hawks is likely to prevent the central bank from over delivering.
Market reaction
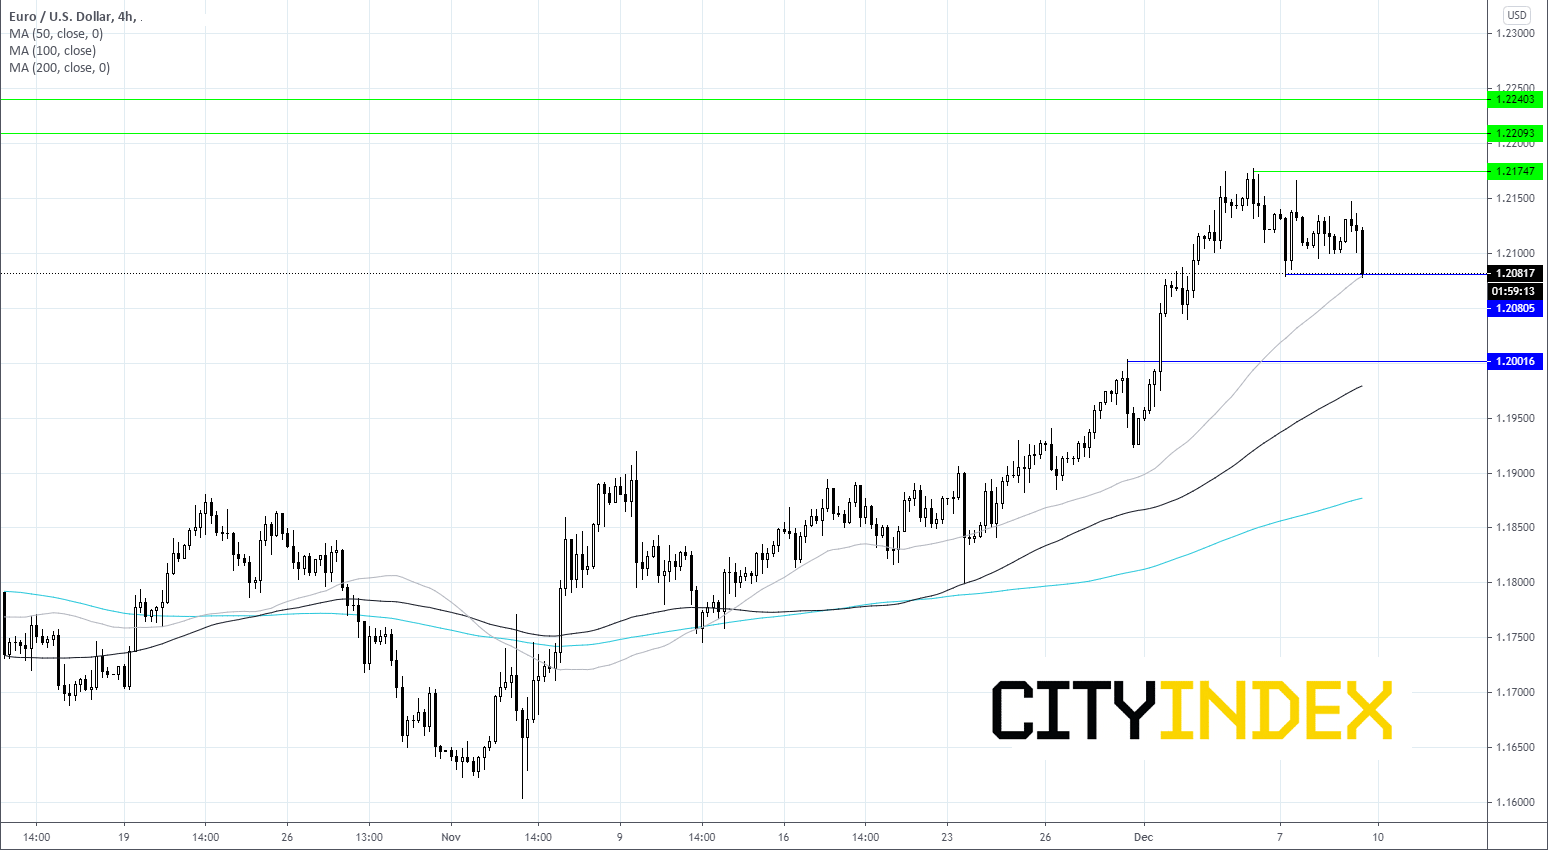
If the market is disappointed by what he ECB brings then the Euro could push higher. Any spike higher could struggle at $1.2175 resistance, a break beyond here could bring $1.2210 into the picture.
However, if Lagarde gets her way and manages to overdeliver near term support can be seen at $1.2080 50 sma & horizontal support prior to $1.20 round number.
The ECB is due to make its monetary policy announcement on Thursday 10th December at 12:45 GMT.
Expectations are running high after Christine Lagarde already pre-committed to additional easing in the October meeting. €500 billion in QE purchases and extremely generous loans to banks are widely expected and priced in. Sinking to the Euro could take a lot more.
Why ease?
In light of second national lockdowns in the likes of France and Germany the reasons for easing monetary policy further are clear; growth appears to be struggling in the final quarter. PMIs have pointed to resilience in the manufacturing sector however, the service sector has tumbled deep into contraction over the quarter. The composite PMI which gauges business activity across the service & manufacturing sector has also contracted each month since September.
In light of second national lockdowns in the likes of France and Germany the reasons for easing monetary policy further are clear; growth appears to be struggling in the final quarter. PMIs have pointed to resilience in the manufacturing sector however, the service sector has tumbled deep into contraction over the quarter. The composite PMI which gauges business activity across the service & manufacturing sector has also contracted each month since September.
The ECB’s previous forecast of 3% QoQ growth in Q4 now looks overly optimistic. A significant downward revision is expected. That said the latest vaccine developments could see an upward revision to H2 GDP 2021.
Lackluster inflation has been a headache for the ECB and is expected to remain weak going forwards, which is only aggravated further by the supercharged Euro.
EUR strength in focus
With the EUR pushing higher even though the ECB are set to ease it could be difficult for the central to reverse the current EUR/USD uptrend despite. The bearish bias on the US Dollar is proving to be too strong. In fact there could be a bigger risk of the ECB under delivering in the press conference by way of a weak forward guidance past December, which could well lift the common currency.
The meeting comes as the Euro has been hovering around 32 month highs. However, the trade weighted EUR trades around its 2009 peak. A strong currency can not only restrict economic growth but can also hold back inflation and with disinflation of -0.3% the ECB could do without a strong Euro.
With the EUR pushing higher even though the ECB are set to ease it could be difficult for the central to reverse the current EUR/USD uptrend despite. The bearish bias on the US Dollar is proving to be too strong. In fact there could be a bigger risk of the ECB under delivering in the press conference by way of a weak forward guidance past December, which could well lift the common currency.
The meeting comes as the Euro has been hovering around 32 month highs. However, the trade weighted EUR trades around its 2009 peak. A strong currency can not only restrict economic growth but can also hold back inflation and with disinflation of -0.3% the ECB could do without a strong Euro.
Over-delivering?
If the central bank is looking to pull down the Euro an above consensus QE purchase of €750 billion or even a rate cut could do the job. However recent commentary suggests that the ECB isn’t there yet.
Let’s not forget that a deep divide between the ECB doves and hawks is likely to prevent the central bank from over delivering.
Market reaction
If the market is disappointed by what he ECB brings then the Euro could push higher. Any spike higher could struggle at $1.2175 resistance, a break beyond here could bring $1.2210 into the picture.
However, if Lagarde gets her way and manages to overdeliver near term support can be seen at $1.2080 50 sma & horizontal support prior to $1.20 round number.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions

EUR/USD Forecast: Euro Extends Losses Ahead of Fed Rate Decision
The euro has started to face a more challenging period in the short term. The EUR/USD pair has already declined by nearly 0.81% over the last four trading sessions, a move that has begun to reinforce a meaningful bearish bias in favor of the U.S. dollar.
EUR/USD Analysis: Euro Attempts to Recover Following the ECB Decision
Today's session has been particularly relevant for the euro's performance in the short term. After the EUR/USD registered a decline of nearly 0.3% during the session, the European currency has managed to recover a large part of its losses.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.