




ISM services could guide global sentiment: The Week Ahead
It has been another volatile week for traders thanks to weaker US economic data, a dovish Fed and a refreshingly hawkish Bank of Japan. ISM services is a key event from the US next week, but apart from that it is mainly second-tier data from the APAC region. And that means appetite for risk might be the main driver for markets next week. But given the larger moves already seen, we may need to lower out expectations for volatility unless a fresh catalyst arrives.
Share this:

It has been another volatile week for traders thanks to weaker US economic data, a dovish Fed and a refreshingly hawkish Bank of Japan. ISM services is a key event from the US next week. We have some second-tier data from the APAC region such as the RBA meeting, NZ inflation expectations and China PMIs, but nothing that is likely to move markets to the same degree as the last two weeks. And that means appetite for risk might be the main driver for markets next week. But given the larger moves already seen, we may need to lower out expectations for volatility unless a fresh catalyst arrives.
The Week Ahead: Calendar
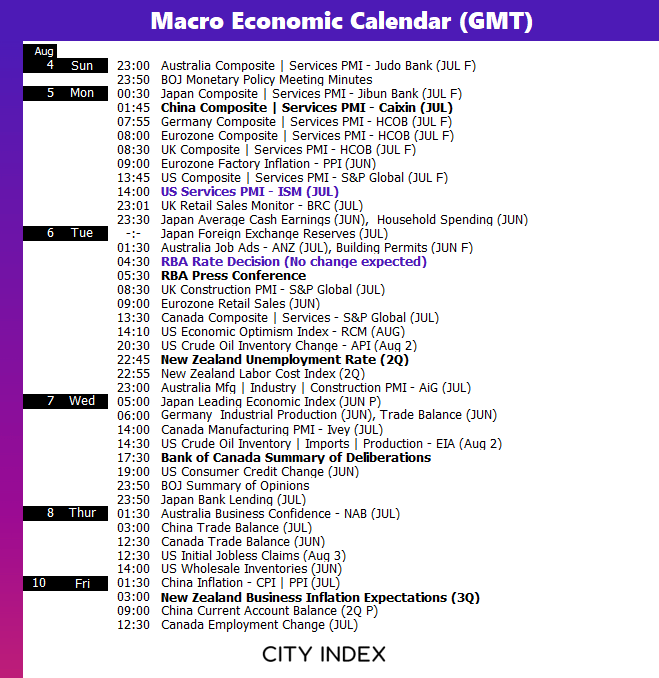

The Week Ahead: Key themes and events
- ISM services report
- RBA cash rate decision, press conference
- NZ unemployment, business inflation expectations
- China PMIs
ISM services report
USD bears and Fed doves were finally vindicated with another batch of weak economic data, and the Fed signalling rate cuts from next month. This week, ISM manufacturing contracted at a faster pace than expected. And if this is to be coupled with another weak ISM services report, it could further spook investors into thinking the Fed are late with cuts and they have finally broken something.
Last month’s report revealed the headline ISM figure contracted the services sector contracted at its fastest pace since the pandemic. New orders, employment and business activity were also negative. And if we are to see an extension of these patterns, then it points to a US (and therefore a global) recession on the horizon. That should be a bearish case for US indices, although it may be inadvertently bullish for the US dollar on a safe-haven basis, even if it does point to more aggressive easing from the Fed. Regardless, the ISM services report is the main economic event to watch next week.
Trader’s watchlist: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
RBA cash rate decision
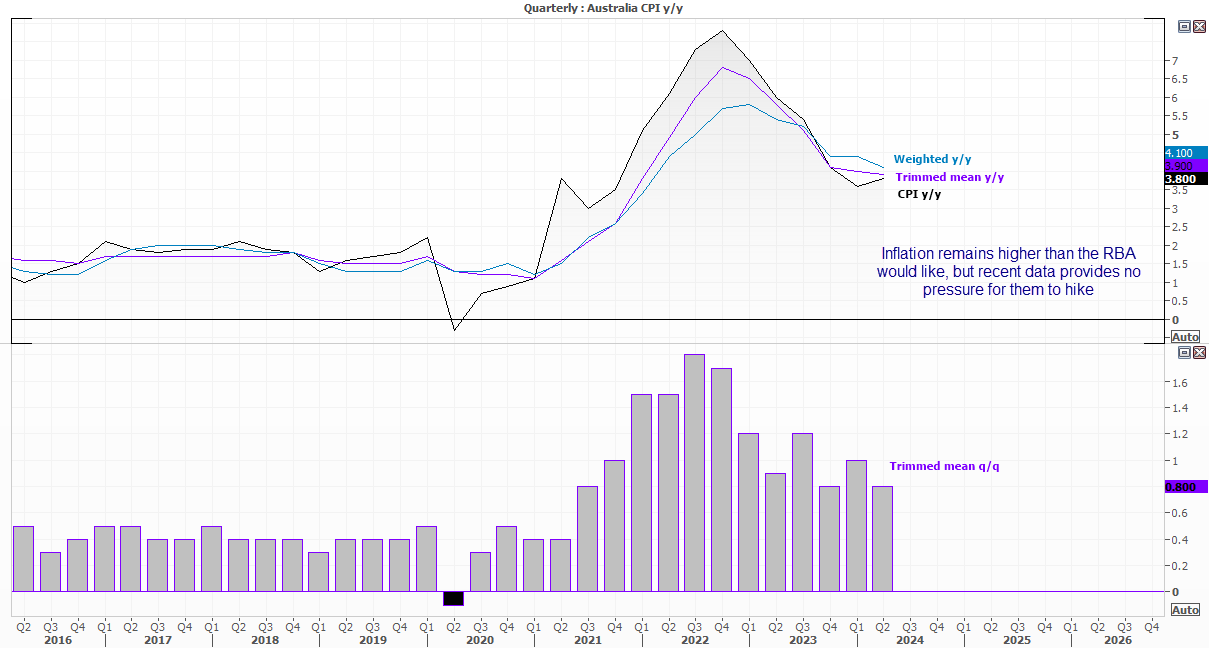
I really do not think the RBA have much of a decision to make, given their quarterly inflation data come in less than expected. Yes, it remains higher than they’d like it to be. But it might be enough for them to remove their hawkish bias from their next statement. And even if they keep it, traders won’t take it seriously. With the Fed in dovish move and the RBNZ removing their own hawkish bias, there seems little reason to expect them to hike with growth input figures softening, even if employment data remains robust overall.
Trader’s watchlist: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Outlook: Historic yield squeeze leaves Aussie bears in control
Australian bond yields have fallen below their US equivalents as the Fed's hawkish repricing gathers momentum. With the Aussie weakening broadly, technical signals suggest sellers remain in control.

Bond yields and crude call the shots for ASX 200
The ASX 200 has rallied on 93% of occasions this year when Australian three-year bond yields have fallen at least five basis points. With crude prices also plunging, the latest breakout has history on its side.

Australian Dollar Outlook: AUD/USD Bears Eye March Low as US CPI Looms
Australian Dollar Outlook: AUD/USD Bears Eye March Low as US CPI Looms
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.