


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
Share this:
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies. Against this backdrop, our S&P 500 forecast remains tilted to the downside in the near-term outlook.
Why are the market struggling?
The backdrop is becoming increasingly difficult for US and indeed global stocks. On Wall Street, market breadth has deteriorated sharply, bond yields are breaking higher and concerns about the US fiscal position are resurfacing, just as expectations of further Federal Reserve tightening are building. With fewer stocks doing the heavy lifting, the risk of a more meaningful correction has increased.
The weakness in risk assets has gathered pace over the past few sessions, as last week’s post-FOMC bounce has faded. Higher interest-rate expectations, elevated oil prices and a stronger dollar have combined to take some of the air out of the rally. I was never particularly convinced that equities could remain comfortably supported against such a challenging macro backdrop in the first place, but things could potentially get worse before they get better.
Wednesday’s move was particularly telling. The main catalyst was the sharp sell-off in the bond market, with yields breaking higher across the curve. Some stronger-than-expected US data and hawkish comments from Fed officials added to the pressure.
Trump-Xi summit matters, but the bond market matters more
The meeting between Donald Trump and Xi Jinping will command attention today, but it may not be the most important driver of markets. Any agreement to extend the existing trade truce would probably be mildly supportive for risk appetite, although much of that outcome appears to be anticipated already. Progress on artificial intelligence and related technology restrictions could also be welcomed.
The bigger issue is what is happening in the Treasury market.
As long as crude oil remains elevated, the combination of inflation concerns, a stronger dollar and higher Treasury yields is likely to keep pressure on risk assets. The US 10-year yield has surged above 5 per cent this week, while the 30-year yield is testing levels last seen around the 2007 highs.
Higher long-term yields raise the opportunity cost of owning growth stocks and other low- or zero-yielding assets like gold and silver. If yields continue to climb, the pressure on equity valuations is likely to intensify.
Market breadth is flashing warning signs
The weakness in breadth is another reason yesterday’s sell-off should not have come as a major surprise.
The S&P 500’s return towards record highs had increasingly been driven by a relatively narrow group of stocks, particularly the hyperscalers and semiconductor names that have carried much of the market’s gains.
As of Tuesday’s close, 52 per cent of S&P 500 constituents were trading below their 200-day moving averages, according to MarketWatch. That is an unusually weak level of participation for an index sitting, at the time, within 1 per cent of a record high.
Indeed, the last time the market displayed a similar combination of weak breadth and proximity to a record was around March 2000, at the peak of the dotcom bubble.
There is another worrying statistic. MarketWatch has highlighted that as of Monday, roughly 60 per cent of S&P 500 stocks were more than 20 per cent below their all-time highs.
None of this means the current market is about to repeat 2000. But it does highlight how narrow the rally has become. Add widening credit spreads and rising nominal Treasury yields to the equation, and the foundations underneath the index look considerably less comfortable than the headline level suggests.
Technical S&P 500 forecast and levels to watch
From a technical analysis perspective, the S&P 500 remains in a bullish trend and most of the important support levels are still intact. So, at this stage, there is no definitive confirmation that the market has peaked.
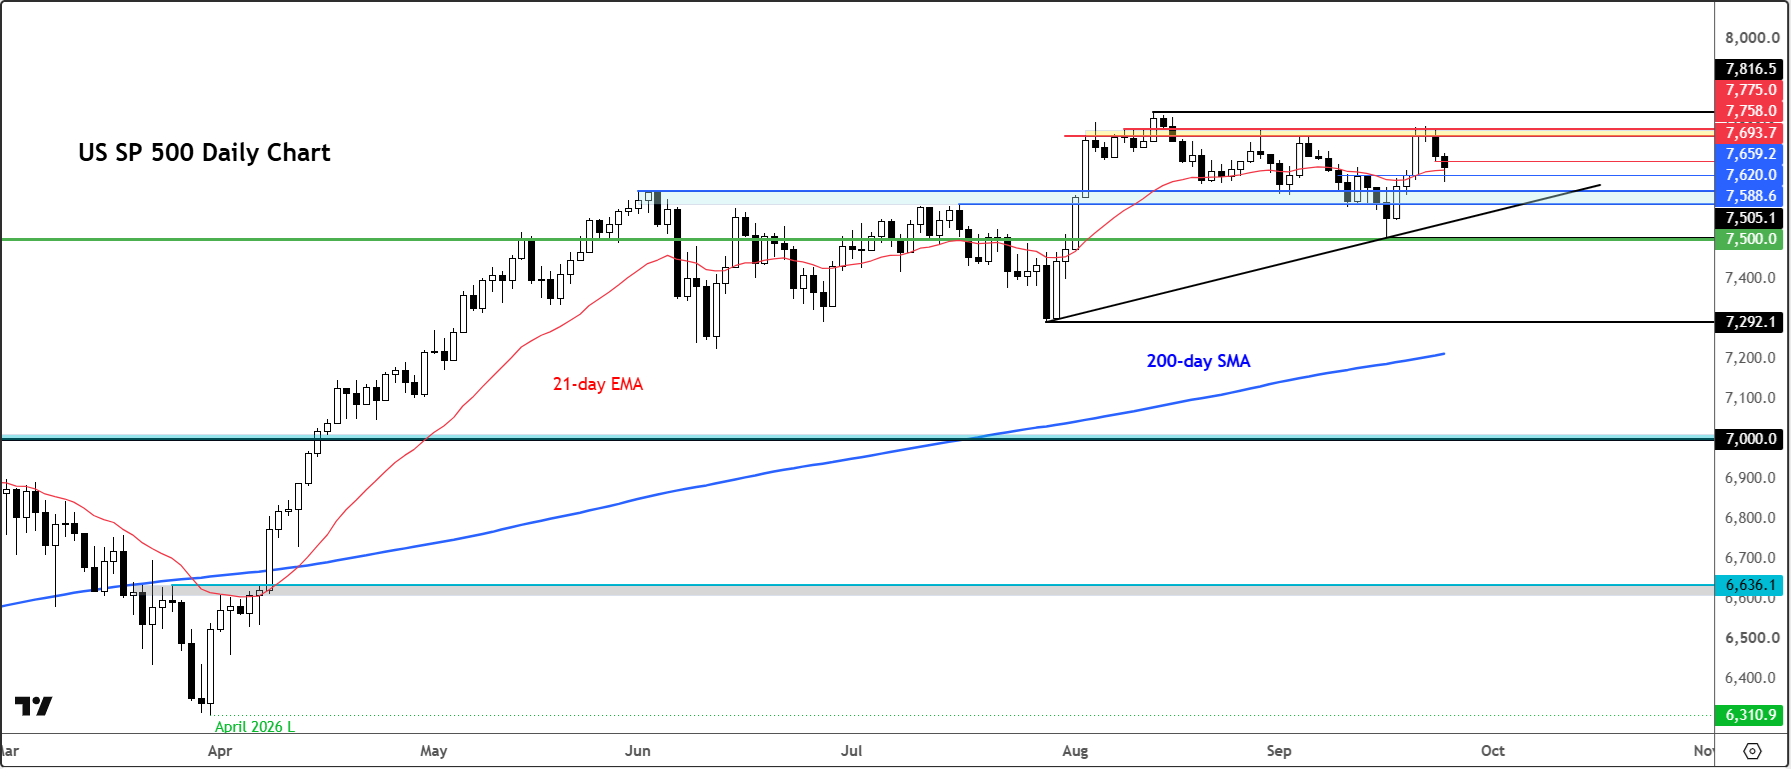
There is, however, a growing warning sign. Our SPX 500 index, which is derived from the underlying S&P 500 futures, has tested the 7,755 to 7,775 area several times without managing to break through decisively. That repeated failure raises the prospect that we may have seen at least a near-term peak.
Similar price action has occurred in the past before the market eventually pushed through resistance, so a renewed attempt at the highs cannot be ruled out. But the macro backdrop is deteriorating, although technically I would still want to see more evidence before declaring the broader uptrend over.
The immediate test is around 7,588-7620, which represents an important short-term support zone.
Below that, 7,505 becomes important. This was the most recent swing low. That is the line in the sand for me tactically. A decisive break would materially weaken the technical picture and increase the likelihood of a deeper correction.
In that scenario, the index could break below 7,500, opening the door towards the summer lows around 7,292.
There could ultimately be scope for an even deeper retracement, but there is little point in getting ahead of the market.
For now, the question is whether the S&P 500 can stabilise above these nearby support levels — or whether the deteriorating macro backdrop finally forces a more meaningful technical break.
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Forecast: AUD/USD, Gold, EUR/USD Under Pressure
Could the US dollar rally accelerate? Matt Simpson examines the outlook for DXY, AUD/USD, EUR/USD and gold, plus key technical levels across forex markets.
GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.

Japanese Yen Short-term Outlook: USD/JPY Breakout Hits 10-Week Highs—160 in Focus 11 11 2026
USD/JPY bulls need a decisive close above trend resistance to sustain the advance, with hotter U.S. inflation adding urgency to the test.

The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.