Market expectations for Fed and BOJ rate hikes in December are still on the table following this week’s central bank meetings and persistent geopolitical instability. Key resistance levels are in focus as markets navigate central-bank guidance, inflation pressures and, most importantly, geopolitical developments. The inconclusive Israeli election results and the upcoming U.S. midterm elections next Tuesday add uncertainty to the ongoing conflict with Iran and its proxies. These developments could influence decisions related to the conflict, as well as crude oil prices, inflation trends, central-bank guidance and corporate earnings outlooks.
December Rate Expectations
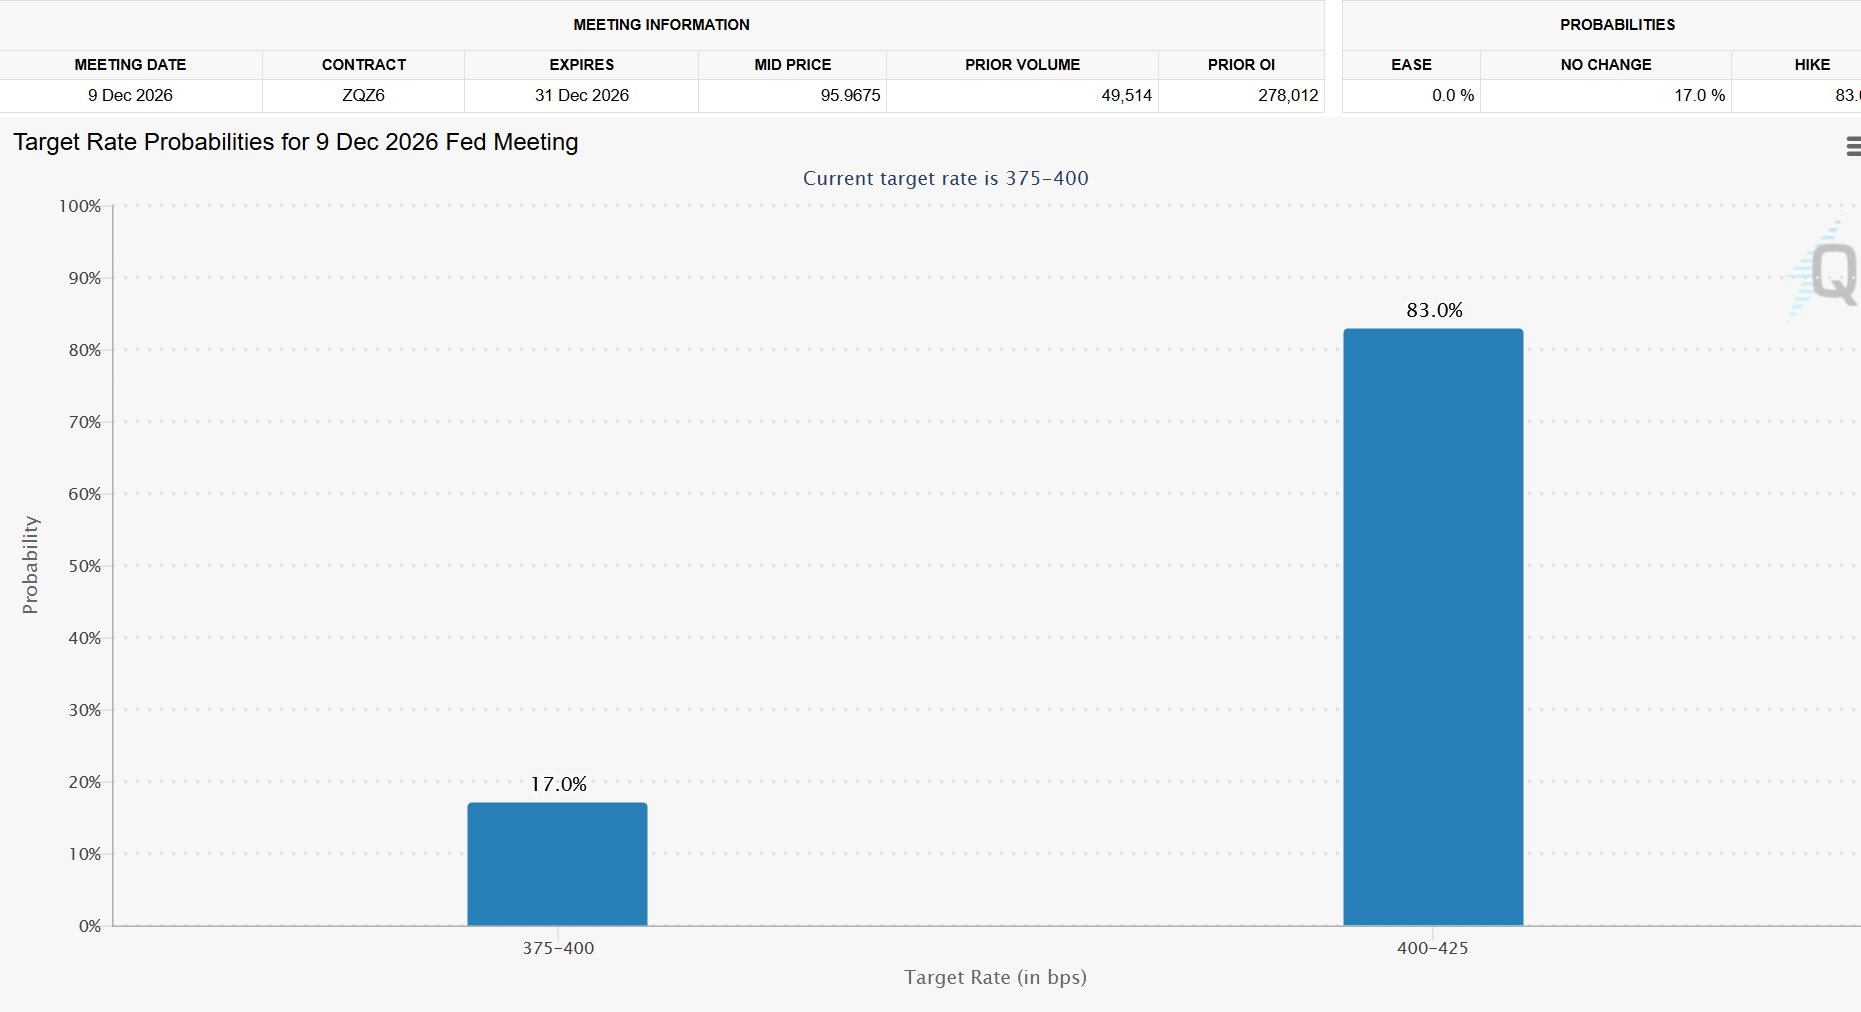
Source: CME Fed Watch Tool
December Fed rate-hike expectations are above 80%, helping keep the U.S. dollar index and dollar pairs on a relatively bullish footing against other currencies. Persistent inflation pressures are supporting this outlook: U.S. CPI rose to 3.7% in September, while Tokyo core CPI reached 2.7% that month, both above their central banks’ 2% targets.
Technically speaking:
- DXY: The index is trading near yearly highs above 102 and facing an eight-month rising resistance line near 103.40. This is a key barrier between longer-term bullish continuation and bearish reversal risks.
- USD/JPY: The pair is holding its bullish, impulsive rebound from 152.90 and daily oversold conditions last seen in 2024. This keeps the yen technically weaker relative to the dollar, despite hawkish December outlooks for both central banks.
- U.S. 10-year Treasury yields: Yields are holding cautiously above 4.93%, keeping bullish risks for the U.S. dollar on the table.
I cover these setups in my weekly webinar, held every Tuesday.
U.S. 10-Year Treasury Yield Outlook: Three-Day Time Frame – Log Scale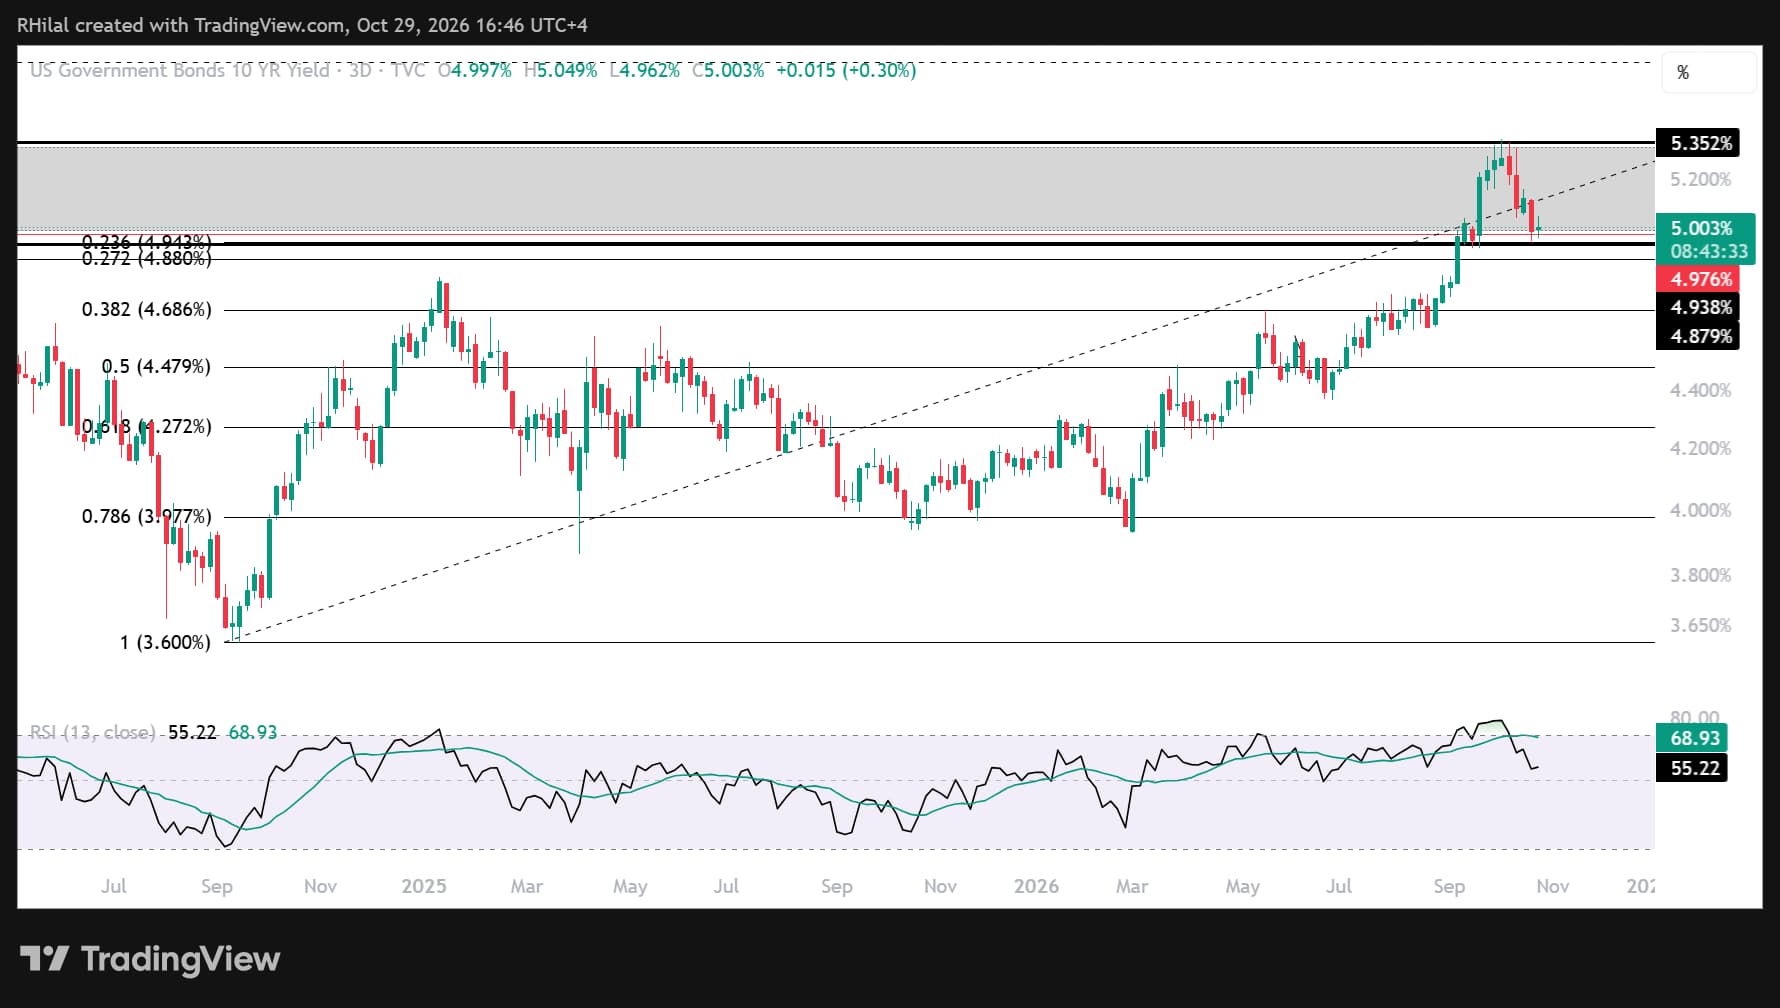
Source: Trading View
On the three-day chart, U.S. 10-year Treasury yields are testing a key Fibonacci retracement zone near 4.93%, based on the September 2024–October 2026 advance.
This support aligns with the 23.6% retracement. A break below 4.93%, followed by a move below the 27.2% retracement near 4.88%, would expose yields to a steeper drawdown and could weigh on the latest dollar rally.
On the upside, a sustained hold above 4.93% and a move back above 5.20% would bring yearly highs back into view on both yield charts and support further gains in the U.S. dollar and its pairs.
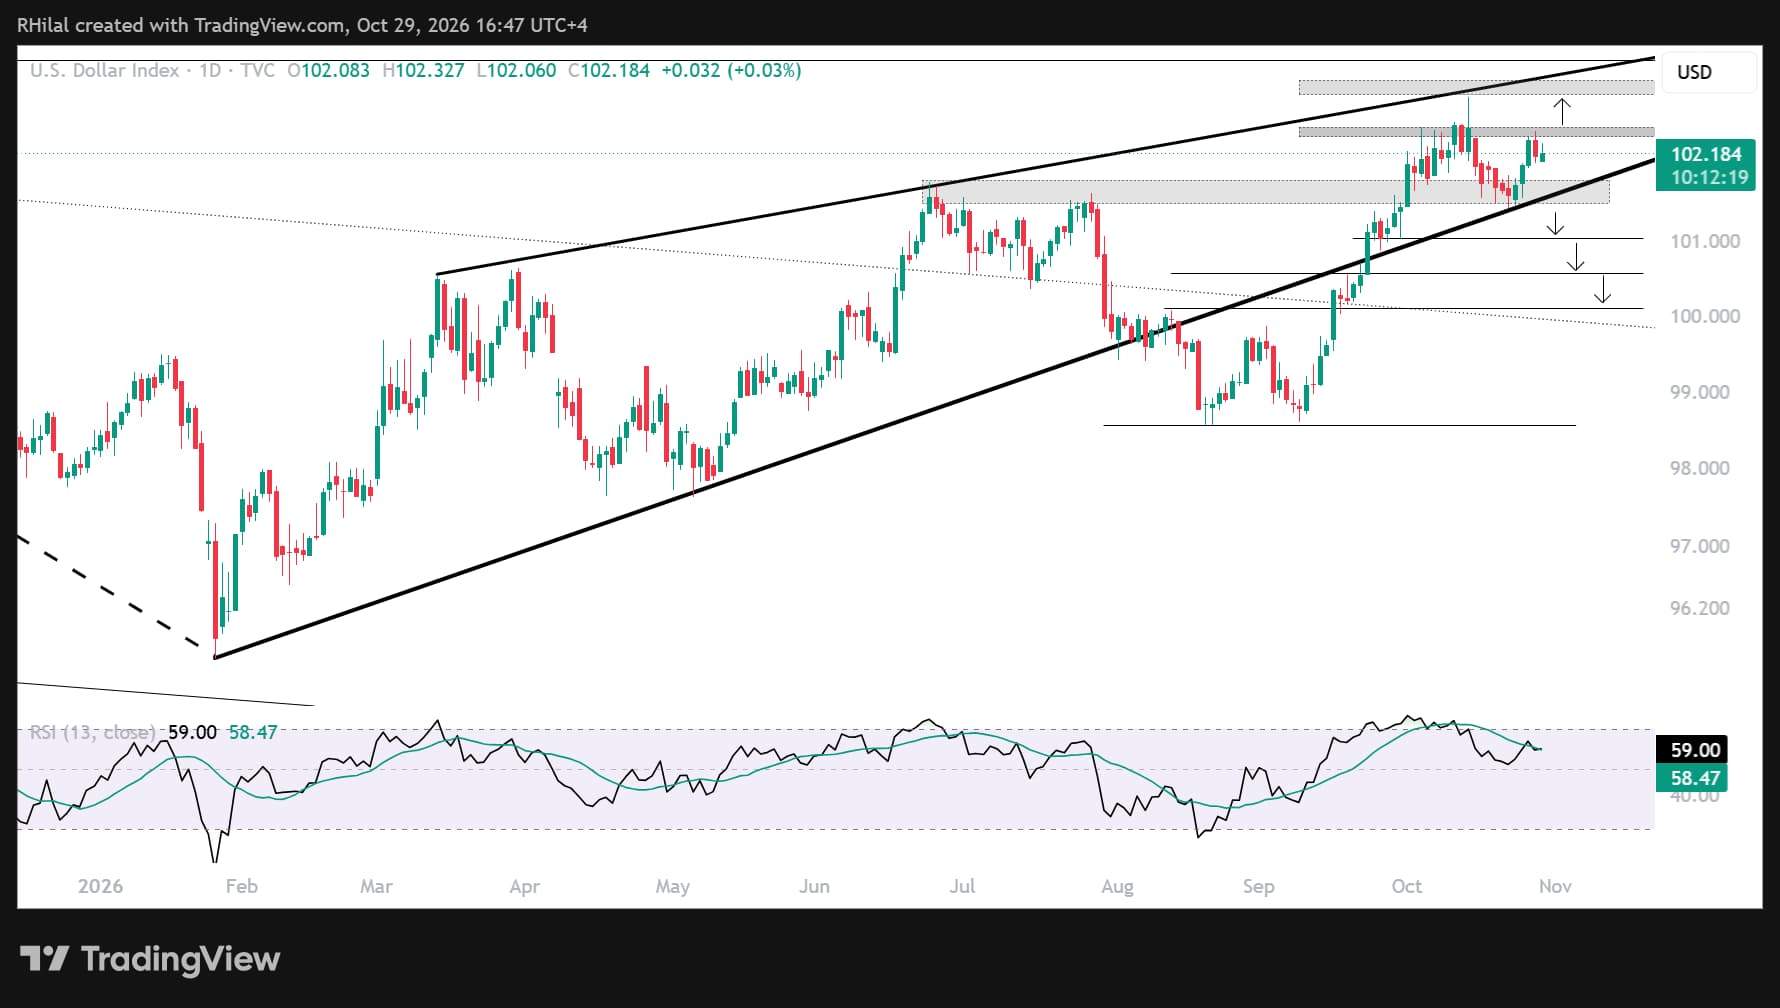
DXY Outlook: Daily Time Frame – Log Scale
Source: TradingView
The DXY is pulling back after closing near its yearly highs and facing resistance near 102.60, with markets weighing Fed expectations and an uncertain geopolitical outlook. A break above 102.60 would expose the yearly high near 103, followed by the eight-month rising resistance around 103.20 and 103.50.
These levels could bring another pullback risk into focus as daily RSI approaches overbought conditions last seen in September, July and March, which aligned with notable reversals on the chart.
A sustained move above the eight-month resistance near 103.50, followed by a hold above that level, would strengthen the longer-term bullish outlook. On the downside, a break below 101.80–101.50—the rising support connecting higher lows across the year—would expose the psychological 100 level and could invalidate the current setup.
USD/JPY Outlook: Daily Time Frame – Log Scale
Source: TradingView
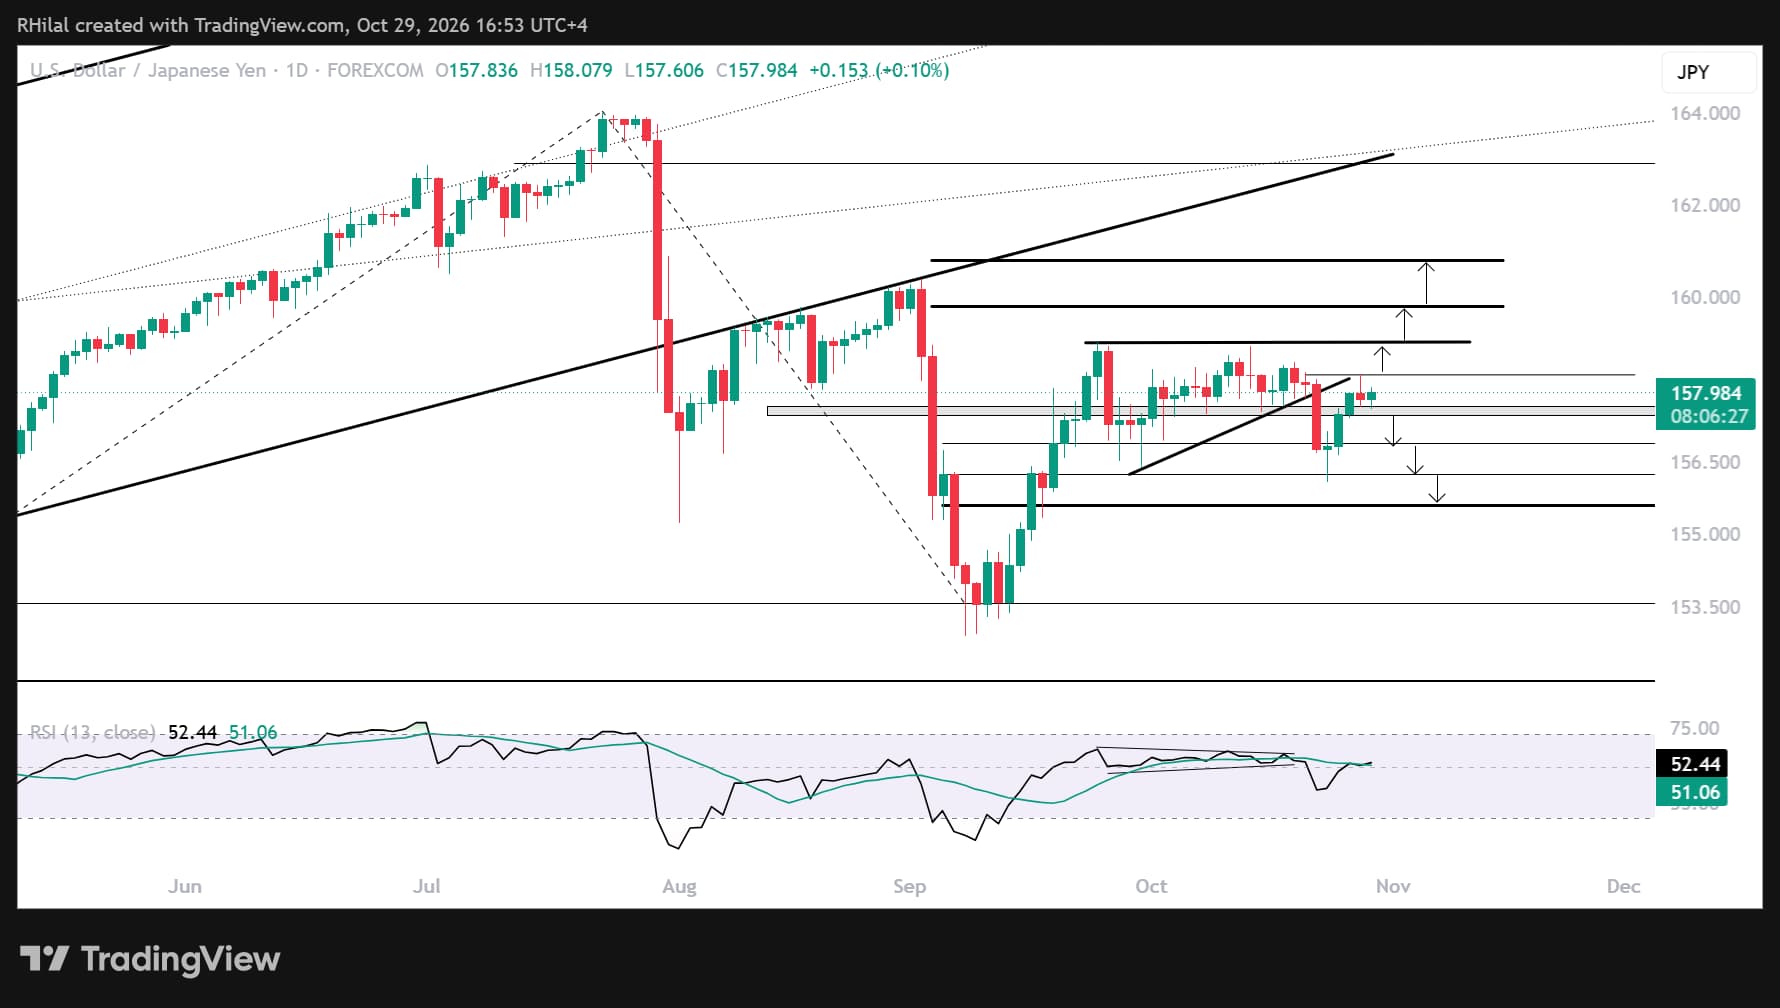
USD/JPY has been trading in a sideways range since September 2026, below 159 and above 156.
If the rebound from 152.60 is impulsive, a breakout above 158.30 would expose 159. That level could trigger another pullback or give way to a further rally toward 159.80 and 160.80. These levels align with Fibonacci extensions of the wave between the September low and high and the October low.
A sustained break higher would bring the yearly highs—and potentially new multi-decade highs—back into focus, while also raising the risk of BOJ intervention if yen weakness resumes.
On the downside, a break below 156.20, the 50% retracement of the September advance, would expose 155.60, 154.70 and 153.50. These levels align with the 61.8% and 78.6% retracements, while 153.50 also aligns with the September closing lows.
The U.S. midterm elections and upcoming inflation reports are likely to influence market direction this quarter. The outlook remains caught between the risk of further geopolitical escalation and the possibility that tensions are approaching an exhaustion point, as discussed in my crude oil weekly outlook: Crude Oil Weekly Outlook: Elections Test Brent–WTI Resistance Levels
Written by Razan Hilal, CMT
Follow on X: @Rh_waves