



USD/JPY Outlook: GDP surprise adds to BoJ pressure, but US still calls the shots
Japan’s GDP beat adds weight to BoJ hike bets, but USD/JPY’s fate still hinges on the U.S. economy, with retail sales and import prices now in focus.
Share this:
- Japan Q2 GDP +0.3% q/q, triple expectations
- Trade and consumption drive upside surprise
- BoJ pressure builds, but U.S. data remains key driver
USD/JPY Summary
U.S. Treasury Secretary Scott Bessent’s subtle nudge for the Bank of Japan (BoJ) to get on with rate hikes fits neatly with the message from Japan’s latest GDP report. But if the aim was to knock the dollar lower against the yen, that’s a job more likely to be done in Washington than Tokyo. For all the chatter about BoJ policy, the dominant driver of USD/JPY remains the U.S. economic and policy backdrop, with the next cues likely to come from retail sales and import price data later Friday.
Trade Boosts Japan GDP
Japan’s economy delivered a stronger-than-expected performance in Q2, with real GDP rising 0.3% q/q, triple the pace expected. The upside surprise was driven largely by trade, with net exports contributing 0.3 percentage points to growth as exports jumped 2% despite U.S. tariffs.
Private consumption, which accounts for more than half of economic activity and is therefore an important driver of inflationary pressures, rose 0.2%, double expectations. The BoJ will be encouraged by signs of consumer resilience but will likely want to see further transmission from stronger wages growth into stronger spending before feeling confident that inflation is self-sustaining.
The GDP deflator, a broad measure of economy-wide inflation that captures price changes across all goods and services produced domestically, rose 3% from a year earlier, down three-tenths from Q1.
The combination of firmer growth, resilient trade, and elevated inflation strengthens the case for the BoJ to resume rate hikes before year-end. While that may please Bessent, who unusually suggested this week that Japan’s central bank was behind the curve in fighting inflation, when it comes to the dominant longer-term driver of USD/JPY movement, that remains an almost entirely U.S. story.
But the U.S. Remains Key for USD/JPY
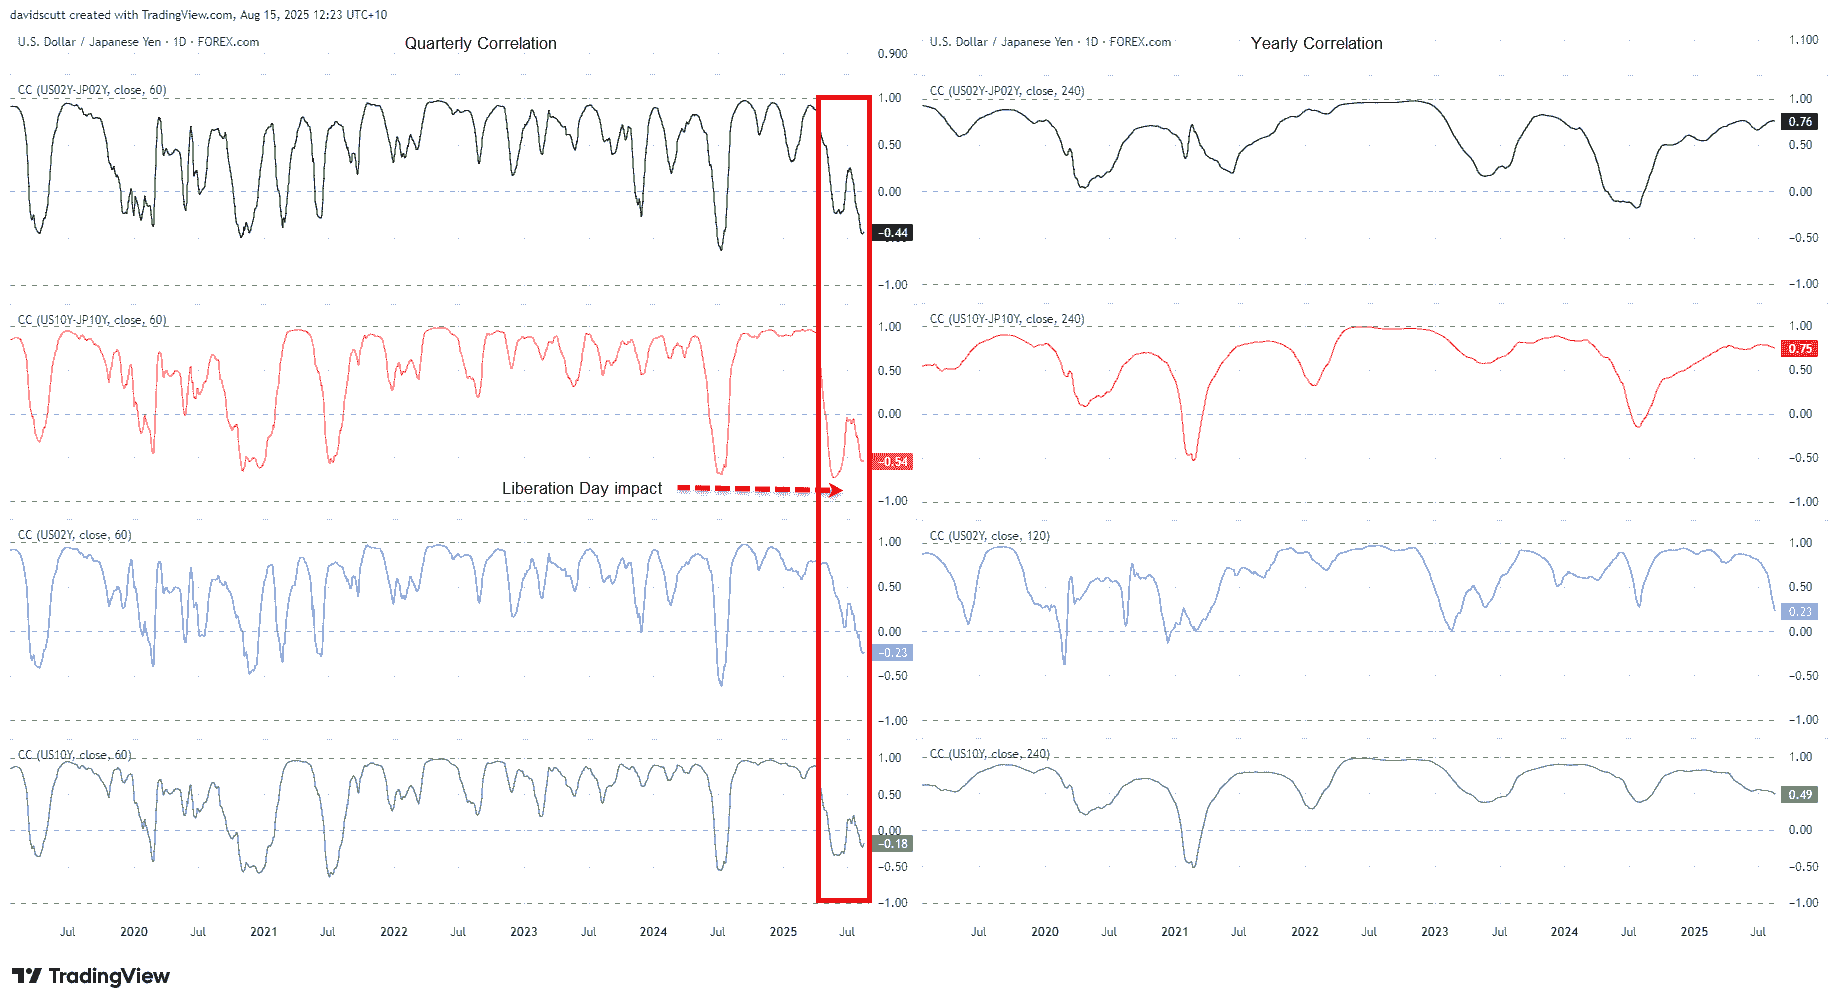
Source: TradingView
You can see that in the correlation analysis below tracking USD/JPY against moves in U.S.–Japanese yield spreads and outright Treasury yields over a rolling quarterly and annual basis. While not uniform over time—as demonstrated earlier this year when USD/JPY fell despite higher U.S. yields and wider spreads following the Liberation Day turbulence—the relationship is often strong to very strong, underlining why it’s U.S. economic data and policy that matter most for USD/JPY traders.
U.S. Retail Sales, Import Prices in Focus
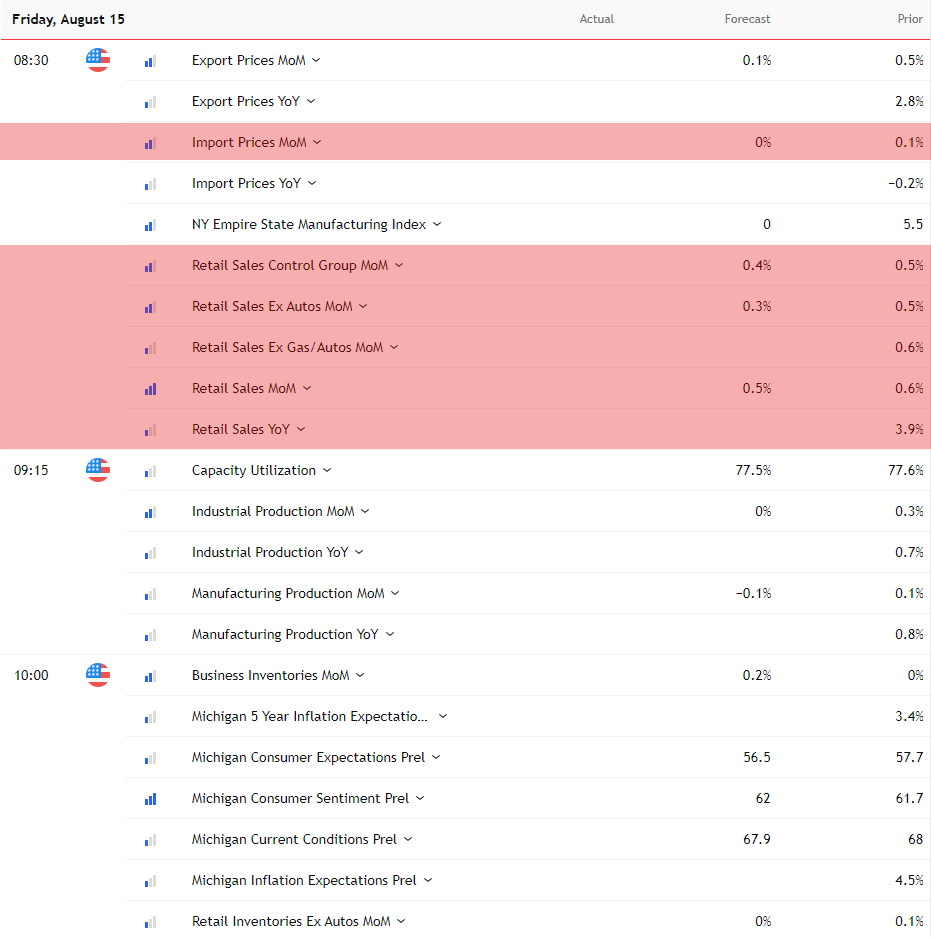
Source: TradingView
With the U.S. CPI and PPI reports out of the way, retail sales and import price data released later Friday are the next risk events set to shake things up for USD/JPY, providing insight on the impact higher tariffs are having on upstream price pressures and consumer behaviour.
After the reversal sparked by Thursday’s hot PPI report, which revealed a pickup in services prices mirroring the detail found in the CPI report, upside surprises in these data prints may see the bullish move in USD/JPY extend further heading into the weekend.
The Trump–Putin summit in Alaska may muddy the price action, but with few expecting significant progress, its influence on hedging activity may be limited.
U.S. Economic Uncertainty Whipsaws USD/JPY
By usual standards, the price action in USD/JPY has been a tad erratic recently, likely reflecting uncertainty as to what exactly is going on in the U.S. economy. Employment growth has slowed sharply, but wages and services inflation remain firm, while there’s little evidence of job shedding. While the Fed is expected to cut rates for the first time this year in September, that could quickly change if it’s proven the July payrolls report was an anomaly rather than the start of a trend, as was the case 12 months earlier.
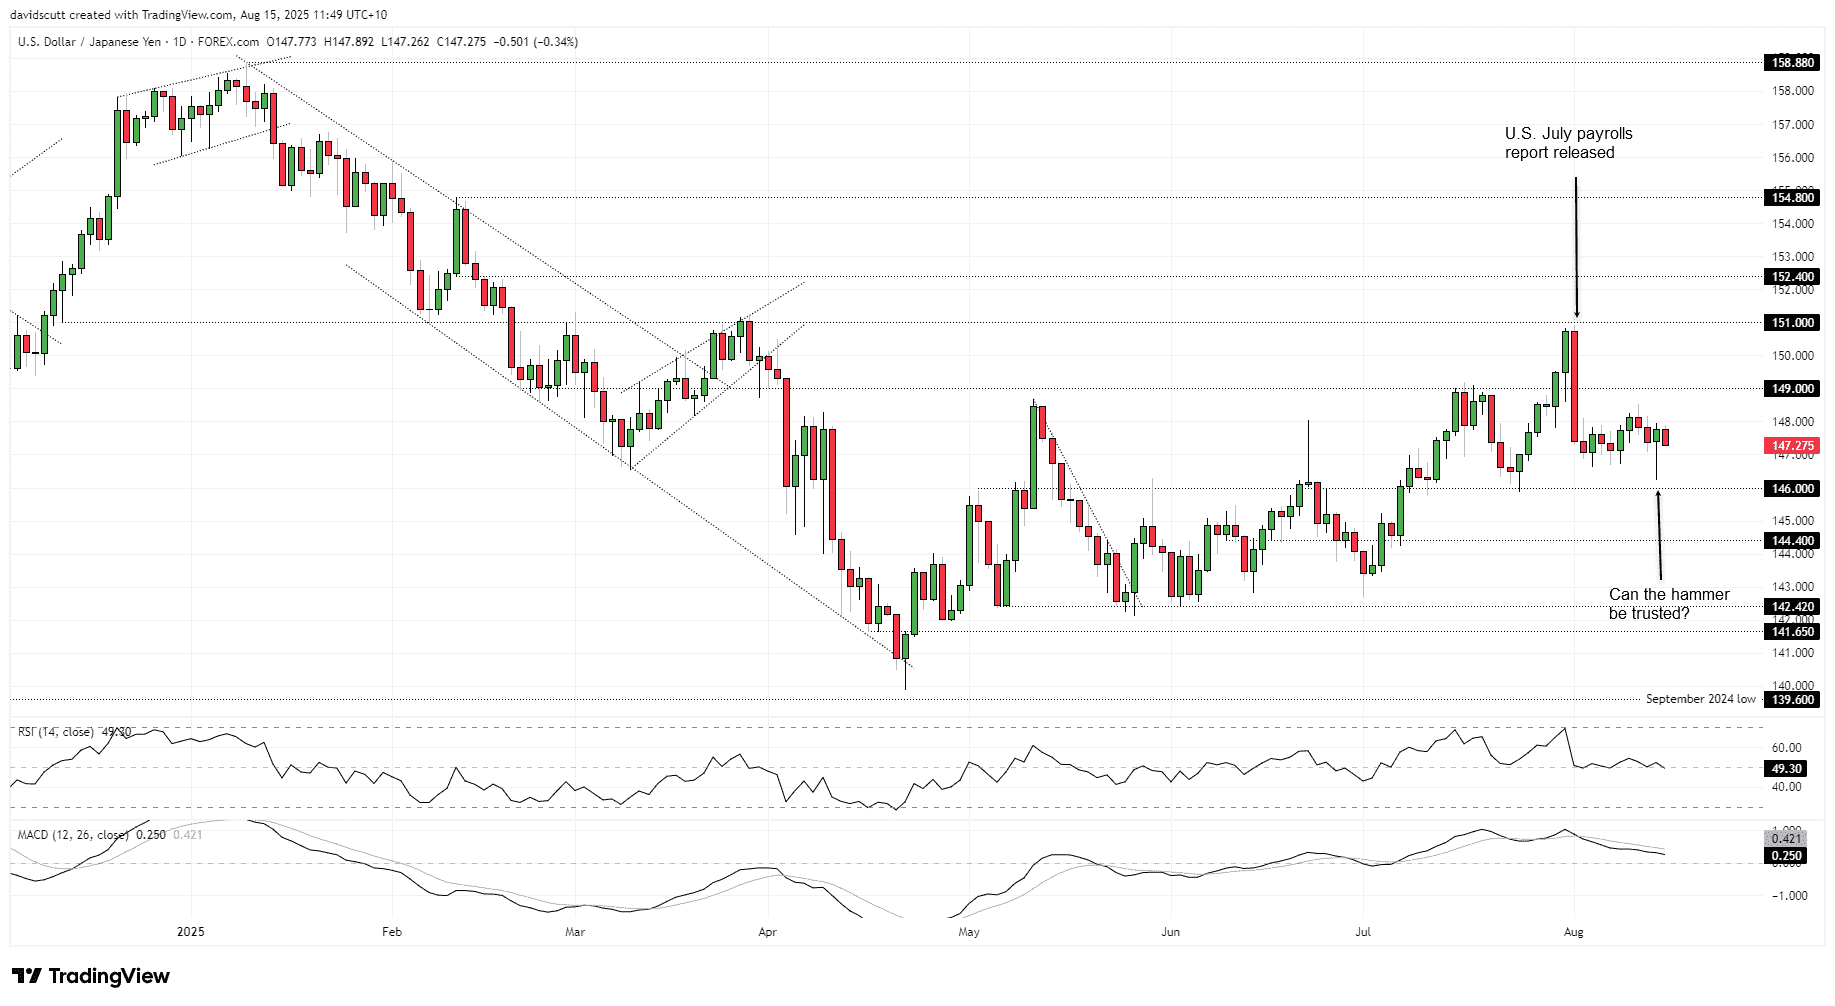
Source: TradingView
The result is that USD/JPY has been choppy within a narrow range since the payrolls report, attracting bids on dips beneath 147.00 with sellers parked above 148.00. Thursday’s hammer candle on the daily chart points to upside risk heading into Friday’s data, but it’s hard to put too much weight on it given recent chop. There’s also no clear signal from momentum indicators, with RSI (14) and MACD flattening out around neutral levels, meaning more emphasis should be put on price action.
Should the range be broken on the data, support is found at 146.00 and 144.40, with resistance located at 149.00 and 151.00.
Latest market news


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Price Action Setups: EUR/USD, USD/JPY
The US Dollar broke out to a fresh yearly high after the CPI report, and that Dollar strength was on full view in pretty much all major pairings with a particular push in EUR/USD.
Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

US dollar forecast: USD/JPY and USD/CHF in focus | Forex Friday
Sticky US inflation and a hawkish Fed have kept the dollar firm across the majors, with USD/JPY pressing on the 160 handle. Here are the levels that matter on USD/JPY and USD/CHF as next week's retail sales, Nvidia results and FOMC minutes approach.

The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.