PepsiCo Q2 Earnings Preview
PepsiCo is due to report Q2 earnings on July 9 before the market opens. Expectations are for the beverages and convenience foods giant to report earnings per share of $2.19, up 3.3% from the same quarter last year.
The key question for investors is whether weakness in PepsiCo’s North American business is finally beginning to stabilise.
Recent quarters have seen the company lose market share across parts of its North American snacks and beverages businesses as consumers pulled back on discretionary spending amid inflationary pressures. While PepsiCo’s international operations have continued to deliver solid growth, investors are increasingly looking for evidence that its core domestic business has reached a turning point.
PepsiCo Foods North America is expected to post another weak quarter as softer consumer spending, inflation and unfavourable weather around the Memorial Day holiday weighed on demand. Core brands including Lay’s, Doritos, Cheetos and Ruffles are all expected to report softer organic sales growth.
The beverages division is expected to perform better in North America, providing some offset to weakness in snacks.
Ultimately, investors are likely to look beyond whether PepsiCo beats earnings expectations and instead focus on management’s outlook. Signs that volumes are stabilising in North America or that promotional activity is easing could support the shares. However, another quarter of deteriorating market share could reinforce concerns that the turnaround is taking longer than expected.
How to Trade PepsiCo Earnings
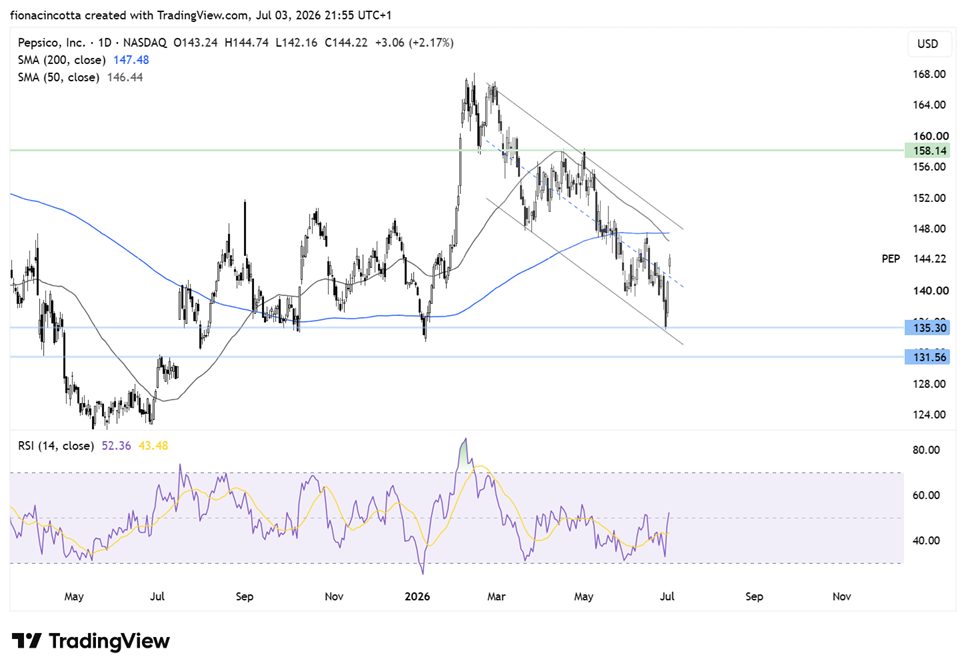
After rallying to a high of $168 at the start of the year, PepsiCo has been trending lower, forming a series of lower highs and lower lows.
The 50-day SMA is crossing below the 200-day SMA in a bearish death cross, while the share price recently fell to a low of $134 before staging a modest recovery. However, the price remains within a descending channel.
Buyers would need to break above the $147 resistance area, where the 200-day SMA and the upper boundary of the descending channel converge, to improve the technical outlook.
On the downside, a break below $134 would create a fresh lower low and expose further downside.
Delta Air Lines Q2 Earnings Preview
Delta Air Lines reports second-quarter earnings on July 10 after the market closes.
The stock has rallied around 35% year-to-date despite elevated fuel prices through much of the quarter, reflecting continued confidence in travel demand and Delta’s ability to protect margins.
Consensus expects earnings per share of $1.53, down from $2.10 a year earlier, while revenue is forecast to rise to $17.49 billion from $16.64 billion.
For investors, the focus is unlikely to be the headline earnings number. Instead, attention will centre on margins and forward guidance.
While fuel prices have fallen sharply following progress in U.S.-Iran peace negotiations, crude traded at elevated levels for much of the quarter, meaning fuel costs are still likely to have weighed on profitability.
At the same time, demand has remained resilient, particularly across premium and business travel, helping support revenue despite a more uncertain macroeconomic backdrop.
Higher labour costs remain a key headwind, meaning investors will want reassurance that pricing power and strong bookings continue to offset rising operating expenses.
With the share price already reflecting considerable optimism, management’s outlook for the second half of the year could prove more important than the Q2 results themselves.
How to Trade Delta Air Lines Earnings
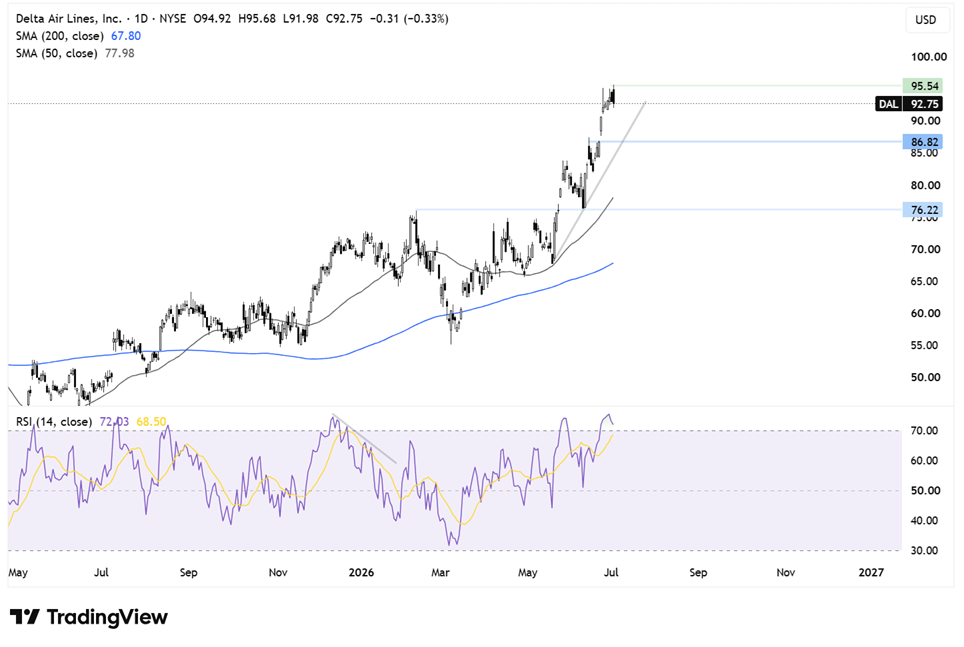
Delta has recovered strongly from its March low near $55, rallying to a record high around $95.
The RSI is moving into overbought territory, suggesting the rally may pause before extending further.
A break above $95 would expose the psychological $100 level.
Initial support sits around $86, where the rising trendline converges with the June 23 high. A move below this level would expose the 50-day SMA near $78, followed by support around $76.
Levi Strauss Q2 Earnings Preview
Levi Strauss is scheduled to report second-quarter earnings on July 8, with Wall Street expecting earnings per share of $0.24 on revenue of $1.52 billion.
Following a strong first quarter, investors will be looking for confirmation that Levi’s direct-to-consumer strategy continues to deliver higher-margin growth.
The company beat expectations in Q1 as higher pricing and direct sales through its own stores and website lifted profitability. Direct-to-consumer sales now account for more than half of total revenue, marking an important milestone for the business.
The strategy offers structurally higher margins but also requires greater investment in stores, logistics and marketing, meaning investors will want evidence that these investments continue to generate profitable growth.
Consumer spending has also remained under scrutiny after elevated fuel prices during much of the quarter threatened to squeeze discretionary spending. However, the sharp decline in oil prices towards quarter-end, combined with a resilient labour market, suggests any pressure on consumer demand may prove temporary.
Management recently raised full-year earnings guidance and now expects adjusted earnings per share of between $1.40 and $1.48, while forecasting revenue growth of 5.5% to 6.5%.
As a result, forward guidance and management’s comments on consumer demand are likely to have a greater impact on the share price than whether the company narrowly beats quarterly earnings estimates.
How to Trade Levi Strauss Earnings
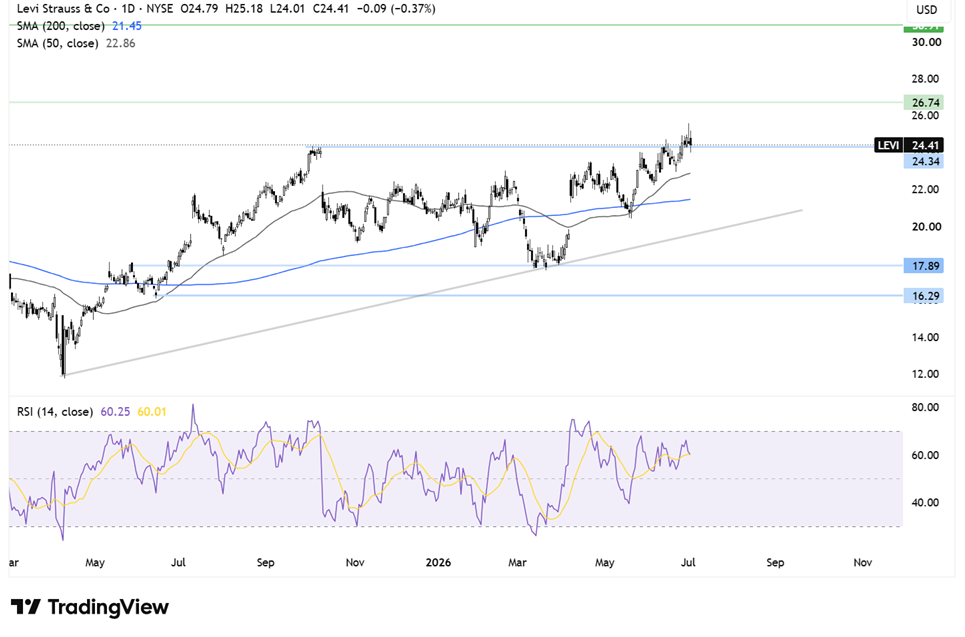
Levi traded within a broad range between $18 and $24 for much of the past nine months before breaking higher.
The share price has since moved above both the 50-day and 200-day SMAs, reaching $25.50, its highest level since 2022.
If bullish momentum continues, buyers will target the record high around $26.74.
On the downside, initial support lies at the 50-day SMA near $23. A break below there would expose the 200-day SMA around $21.50.