



06 11 US PRE OPEN
The S&P 500 Futures are drawing a consolidation after four straight days of rally
Share this:
The S&P 500 Futures are drawing a consolidation after four straight days of rally as investors still face uncertainty of the presidential election result.
Later today, the U.S. Labor Department will release the nonfarm payrolls report for October (+0.59 million jobs, jobless rate at 7.6% expected). The Commerce Department will report September wholesale inventories (-0.1% on month expected).
European indices are losing some ground. On the economic data front, German September industrial production only rose 1.6% on month while +2.5% was expected August figures have been revised lower from +0.5% to +0.2%.
Asian indices closed higher. In japan, official data showed that household spending dropped 10.2% on year in September (-10.5% expected).
WTI Crude Oil is still consolidating during Asian session. RBC expected that Iran would return to oil exported by 2H next year if former President Job Biden wins the President election. Besides, Standard Chartered Bank projected that global oil demand would fall by 8.73M b/d on year in 4Q. Later today, Baker Hughes will report the total number of rig counts for the U.S. and Canada.
Gold is on set for a weekly gain while the U.S dollar still consolidates on risks of divided U.S congress and hopes of further Fed stimulus.
Gold rose 6.14 dollars (+0.32%) to 1955.81.
The dollar index fell 0.2pt to 92.322.
U.S. Equity Snapshot
CVS Health (CVS), the pharmacy and healthcare company, pops before premarket after reporting third quarter adjusted EPS of 1.66 dollar, above estimates, vs 1.84 dollar a year earlier, on comparable sales up 5.7%, beating forecasts. The company expects full year adjusted EPS of 7.35-7.45 dollars, exceeding consensus, vs a previous forecast of 7.14-7.27 dollars. Separately, the company "appointed Karen S. Lynch, currently Executive Vice President, CVS Health and President, Aetna, as the company's next President and CEO, effective February 1, 2021."
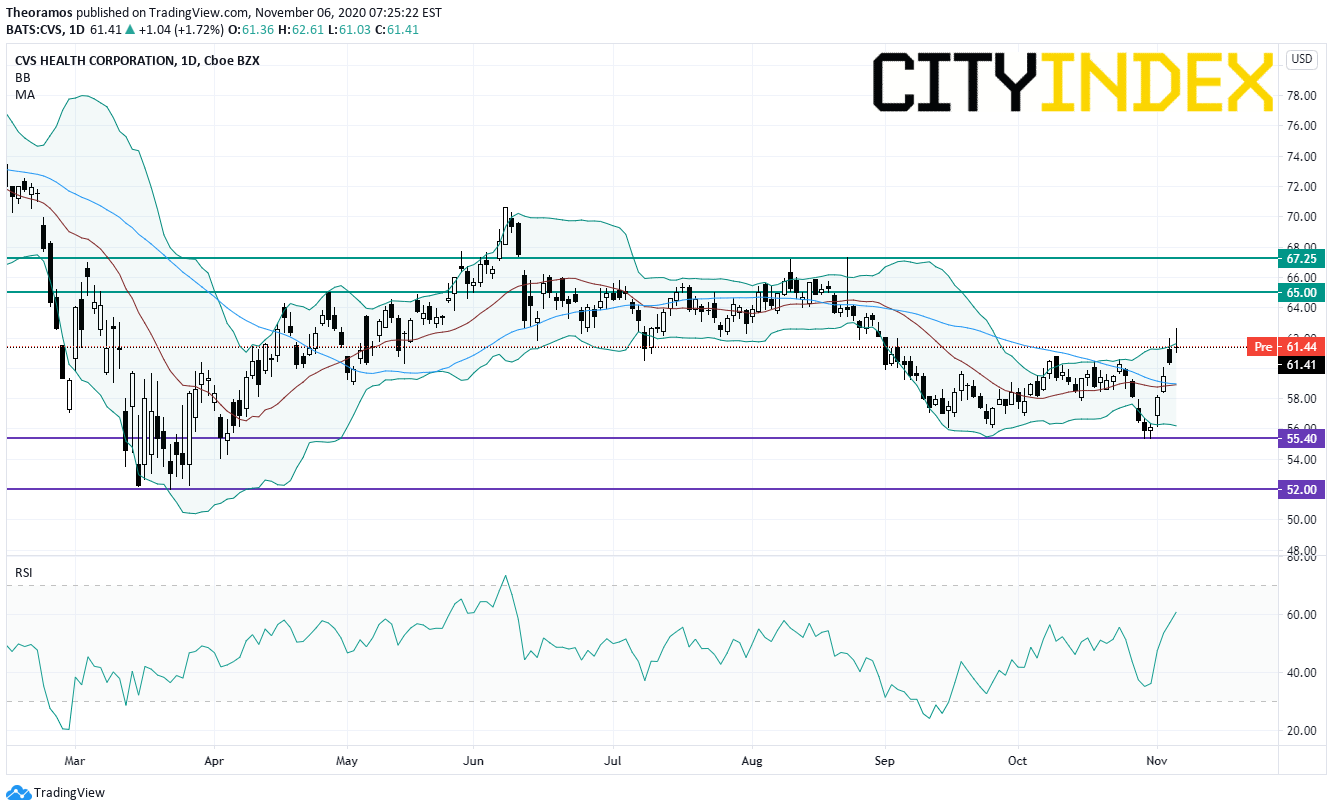
Source: TradingView, GAIN Capital
Square (SQ), the mobile and electronic payment specialist, jumped after hours after posting quarterly adjusted EPS that significantly beat estimates.
Uber Technologies (UBER), the ride-sharing company, lost ground post market as third quarter sales missed estimates.
Roku (ROKU), the video streaming platform, gained ground in extended trading after reporting third quarter earnings that beat estimates.
Electronic Arts (EA), a global developer and publisher of video games, posted second quarter adjusted EPS of 0.05 dollar, just ahead of the consensus, down from 0.97 dollar a year ago on adjusted revenue of 910.0 million dollars, below forecasts, down from 1.3 billion dollars a year earlier.
T-Mobile US (TMUS), a wireless network operator, released third quarter EPS of 1.00 dollar, beating forecasts, down from 1.15 dollar a year ago on revenue of 19.3 billion dollars, better than expected, up from 11.1 billion dollars a year earlier.
Peloton Interactive (PTON), the interactive fitness platform, dropped post market as the company warned of delivering delays and increasing costs.
Zillow (ZG), the online real estate database company, jumped after hours as third quarter earnings topped estimates.
Booking Holdings (BKNG), one of the largest online travel companies, reported third quarter adjusted EPS of 12.27 dollars, missing estimates, down from 45.36 dollars a year ago on revenue of 2.6 billion dollars, above forecasts, down from 5.0 billion dollars a year earlier.
AIG (AIG), a global insurance and financial services firm, announced third quarter adjusted EPS of 0.81 dollar, beating forecasts, up from 0.56 dollar a year ago.
Monster Beverage (MNST), a developer and marketer of energy drinks, disclosed third quarter EPS of 0.65 dollar, just above estimates, up from 0.55 dollar a year ago on sales of 1.3 billion dollars, also just beating the consensus, up from 1.1 billion dollars a year earlier.
Later today, the U.S. Labor Department will release the nonfarm payrolls report for October (+0.59 million jobs, jobless rate at 7.6% expected). The Commerce Department will report September wholesale inventories (-0.1% on month expected).
European indices are losing some ground. On the economic data front, German September industrial production only rose 1.6% on month while +2.5% was expected August figures have been revised lower from +0.5% to +0.2%.
Asian indices closed higher. In japan, official data showed that household spending dropped 10.2% on year in September (-10.5% expected).
WTI Crude Oil is still consolidating during Asian session. RBC expected that Iran would return to oil exported by 2H next year if former President Job Biden wins the President election. Besides, Standard Chartered Bank projected that global oil demand would fall by 8.73M b/d on year in 4Q. Later today, Baker Hughes will report the total number of rig counts for the U.S. and Canada.
U.S indices closed up on Thursday, lifted by Automobiles & Components (+5.05%), Materials (+4.05%) and Semiconductors & Semiconductor Equipment (+4.04%) sectors.
Approximately 72% of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% were trading above their 20-day moving average. The VIX Index fell 1.77pt (-5.99%) to 27.8 and WTI Crude Oil declined $0.64 (-1.63%) to $38.51 at the close.
On the U.S economic data front, Initial Jobless Claims dropped to 751K for the week ending October 31st (735K expected), from a revised 758K in the week before. Continuing Claims fell to 7,285K for the week ending October 24th (7,200K expected), from a revised 7,823K in the prior week. Finally, the Federal Open Market Committee (FOMC) kept the Federal Funds Target Rate between 0.00% and 0.25%, as expected.
Gold is on set for a weekly gain while the U.S dollar still consolidates on risks of divided U.S congress and hopes of further Fed stimulus.
Gold rose 6.14 dollars (+0.32%) to 1955.81.
The dollar index fell 0.2pt to 92.322.
U.S. Equity Snapshot
CVS Health (CVS), the pharmacy and healthcare company, pops before premarket after reporting third quarter adjusted EPS of 1.66 dollar, above estimates, vs 1.84 dollar a year earlier, on comparable sales up 5.7%, beating forecasts. The company expects full year adjusted EPS of 7.35-7.45 dollars, exceeding consensus, vs a previous forecast of 7.14-7.27 dollars. Separately, the company "appointed Karen S. Lynch, currently Executive Vice President, CVS Health and President, Aetna, as the company's next President and CEO, effective February 1, 2021."
Source: TradingView, GAIN Capital
Square (SQ), the mobile and electronic payment specialist, jumped after hours after posting quarterly adjusted EPS that significantly beat estimates.
Uber Technologies (UBER), the ride-sharing company, lost ground post market as third quarter sales missed estimates.
Roku (ROKU), the video streaming platform, gained ground in extended trading after reporting third quarter earnings that beat estimates.
Electronic Arts (EA), a global developer and publisher of video games, posted second quarter adjusted EPS of 0.05 dollar, just ahead of the consensus, down from 0.97 dollar a year ago on adjusted revenue of 910.0 million dollars, below forecasts, down from 1.3 billion dollars a year earlier.
T-Mobile US (TMUS), a wireless network operator, released third quarter EPS of 1.00 dollar, beating forecasts, down from 1.15 dollar a year ago on revenue of 19.3 billion dollars, better than expected, up from 11.1 billion dollars a year earlier.
Peloton Interactive (PTON), the interactive fitness platform, dropped post market as the company warned of delivering delays and increasing costs.
Zillow (ZG), the online real estate database company, jumped after hours as third quarter earnings topped estimates.
Booking Holdings (BKNG), one of the largest online travel companies, reported third quarter adjusted EPS of 12.27 dollars, missing estimates, down from 45.36 dollars a year ago on revenue of 2.6 billion dollars, above forecasts, down from 5.0 billion dollars a year earlier.
AIG (AIG), a global insurance and financial services firm, announced third quarter adjusted EPS of 0.81 dollar, beating forecasts, up from 0.56 dollar a year ago.
Monster Beverage (MNST), a developer and marketer of energy drinks, disclosed third quarter EPS of 0.65 dollar, just above estimates, up from 0.55 dollar a year ago on sales of 1.3 billion dollars, also just beating the consensus, up from 1.1 billion dollars a year earlier.
The S&P 500 Futures are drawing a consolidation after four straight days of rally as investors still face uncertainty of the presidential election result.
Later today, the U.S. Labor Department will release the nonfarm payrolls report for October (+0.59 million jobs, jobless rate at 7.6% expected). The Commerce Department will report September wholesale inventories (-0.1% on month expected).
European indices are losing some ground. On the economic data front, German September industrial production only rose 1.6% on month while +2.5% was expected August figures have been revised lower from +0.5% to +0.2%.
Asian indices closed higher. In japan, official data showed that household spending dropped 10.2% on year in September (-10.5% expected).
WTI Crude Oil is still consolidating during Asian session. RBC expected that Iran would return to oil exported by 2H next year if former President Job Biden wins the President election. Besides, Standard Chartered Bank projected that global oil demand would fall by 8.73M b/d on year in 4Q. Later today, Baker Hughes will report the total number of rig counts for the U.S. and Canada.
Gold is on set for a weekly gain while the U.S dollar still consolidates on risks of divided U.S congress and hopes of further Fed stimulus.
Gold rose 6.14 dollars (+0.32%) to 1955.81.
The dollar index fell 0.2pt to 92.322.
U.S. Equity Snapshot
CVS Health (CVS), the pharmacy and healthcare company, pops before premarket after reporting third quarter adjusted EPS of 1.66 dollar, above estimates, vs 1.84 dollar a year earlier, on comparable sales up 5.7%, beating forecasts. The company expects full year adjusted EPS of 7.35-7.45 dollars, exceeding consensus, vs a previous forecast of 7.14-7.27 dollars. Separately, the company "appointed Karen S. Lynch, currently Executive Vice President, CVS Health and President, Aetna, as the company's next President and CEO, effective February 1, 2021."
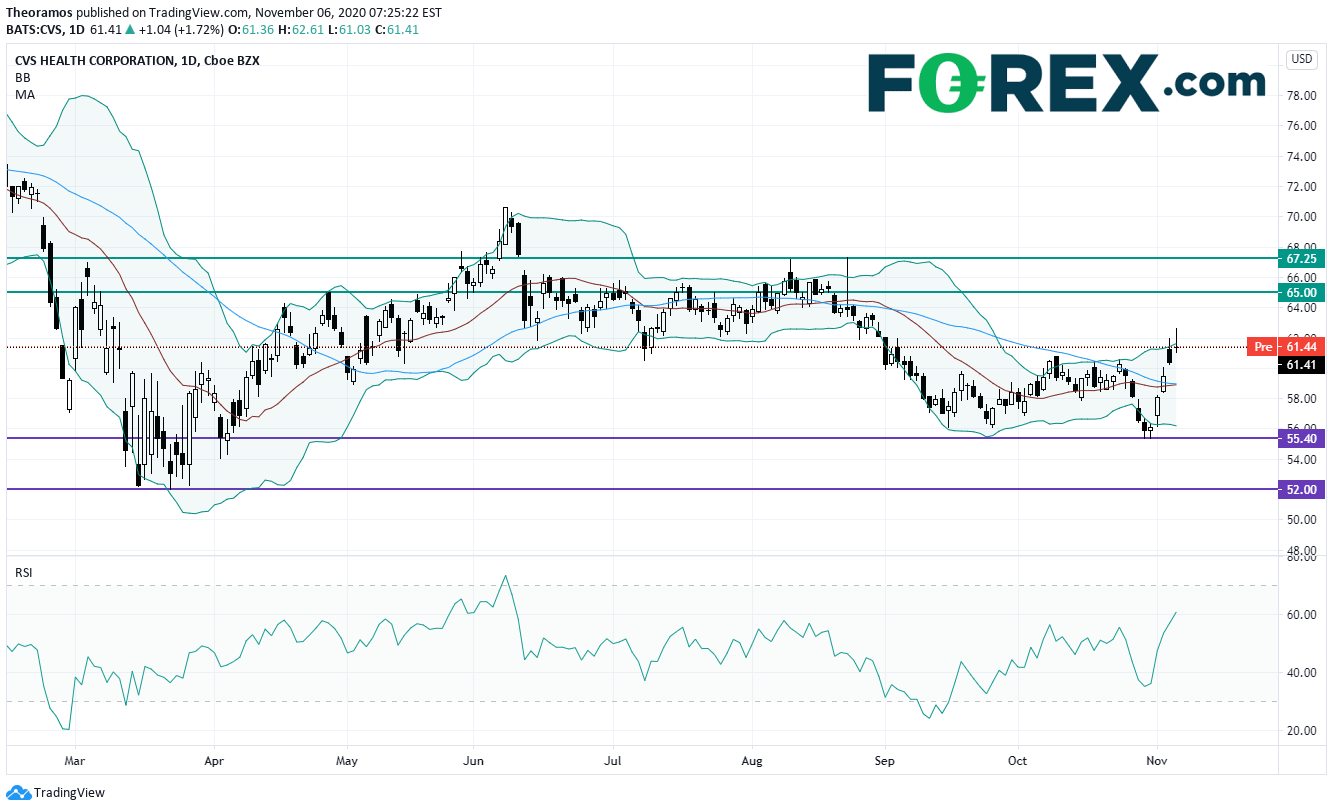
Source: TradingView, GAIN Capital
Square (SQ), the mobile and electronic payment specialist, jumped after hours after posting quarterly adjusted EPS that significantly beat estimates.
Uber Technologies (UBER), the ride-sharing company, lost ground post market as third quarter sales missed estimates.
Roku (ROKU), the video streaming platform, gained ground in extended trading after reporting third quarter earnings that beat estimates.
Electronic Arts (EA), a global developer and publisher of video games, posted second quarter adjusted EPS of 0.05 dollar, just ahead of the consensus, down from 0.97 dollar a year ago on adjusted revenue of 910.0 million dollars, below forecasts, down from 1.3 billion dollars a year earlier.
T-Mobile US (TMUS), a wireless network operator, released third quarter EPS of 1.00 dollar, beating forecasts, down from 1.15 dollar a year ago on revenue of 19.3 billion dollars, better than expected, up from 11.1 billion dollars a year earlier.
Peloton Interactive (PTON), the interactive fitness platform, dropped post market as the company warned of delivering delays and increasing costs.
Zillow (ZG), the online real estate database company, jumped after hours as third quarter earnings topped estimates.
Booking Holdings (BKNG), one of the largest online travel companies, reported third quarter adjusted EPS of 12.27 dollars, missing estimates, down from 45.36 dollars a year ago on revenue of 2.6 billion dollars, above forecasts, down from 5.0 billion dollars a year earlier.
AIG (AIG), a global insurance and financial services firm, announced third quarter adjusted EPS of 0.81 dollar, beating forecasts, up from 0.56 dollar a year ago.
Monster Beverage (MNST), a developer and marketer of energy drinks, disclosed third quarter EPS of 0.65 dollar, just above estimates, up from 0.55 dollar a year ago on sales of 1.3 billion dollars, also just beating the consensus, up from 1.1 billion dollars a year earlier.
Later today, the U.S. Labor Department will release the nonfarm payrolls report for October (+0.59 million jobs, jobless rate at 7.6% expected). The Commerce Department will report September wholesale inventories (-0.1% on month expected).
European indices are losing some ground. On the economic data front, German September industrial production only rose 1.6% on month while +2.5% was expected August figures have been revised lower from +0.5% to +0.2%.
Asian indices closed higher. In japan, official data showed that household spending dropped 10.2% on year in September (-10.5% expected).
WTI Crude Oil is still consolidating during Asian session. RBC expected that Iran would return to oil exported by 2H next year if former President Job Biden wins the President election. Besides, Standard Chartered Bank projected that global oil demand would fall by 8.73M b/d on year in 4Q. Later today, Baker Hughes will report the total number of rig counts for the U.S. and Canada.
U.S indices closed up on Thursday, lifted by Automobiles & Components (+5.05%), Materials (+4.05%) and Semiconductors & Semiconductor Equipment (+4.04%) sectors.
Approximately 72% of stocks in the S&P 500 Index were trading above their 200-day moving average and 49% were trading above their 20-day moving average. The VIX Index fell 1.77pt (-5.99%) to 27.8 and WTI Crude Oil declined $0.64 (-1.63%) to $38.51 at the close.
On the U.S economic data front, Initial Jobless Claims dropped to 751K for the week ending October 31st (735K expected), from a revised 758K in the week before. Continuing Claims fell to 7,285K for the week ending October 24th (7,200K expected), from a revised 7,823K in the prior week. Finally, the Federal Open Market Committee (FOMC) kept the Federal Funds Target Rate between 0.00% and 0.25%, as expected.
Gold is on set for a weekly gain while the U.S dollar still consolidates on risks of divided U.S congress and hopes of further Fed stimulus.
Gold rose 6.14 dollars (+0.32%) to 1955.81.
The dollar index fell 0.2pt to 92.322.
U.S. Equity Snapshot
CVS Health (CVS), the pharmacy and healthcare company, pops before premarket after reporting third quarter adjusted EPS of 1.66 dollar, above estimates, vs 1.84 dollar a year earlier, on comparable sales up 5.7%, beating forecasts. The company expects full year adjusted EPS of 7.35-7.45 dollars, exceeding consensus, vs a previous forecast of 7.14-7.27 dollars. Separately, the company "appointed Karen S. Lynch, currently Executive Vice President, CVS Health and President, Aetna, as the company's next President and CEO, effective February 1, 2021."
Source: TradingView, GAIN Capital
Square (SQ), the mobile and electronic payment specialist, jumped after hours after posting quarterly adjusted EPS that significantly beat estimates.
Uber Technologies (UBER), the ride-sharing company, lost ground post market as third quarter sales missed estimates.
Roku (ROKU), the video streaming platform, gained ground in extended trading after reporting third quarter earnings that beat estimates.
Electronic Arts (EA), a global developer and publisher of video games, posted second quarter adjusted EPS of 0.05 dollar, just ahead of the consensus, down from 0.97 dollar a year ago on adjusted revenue of 910.0 million dollars, below forecasts, down from 1.3 billion dollars a year earlier.
T-Mobile US (TMUS), a wireless network operator, released third quarter EPS of 1.00 dollar, beating forecasts, down from 1.15 dollar a year ago on revenue of 19.3 billion dollars, better than expected, up from 11.1 billion dollars a year earlier.
Peloton Interactive (PTON), the interactive fitness platform, dropped post market as the company warned of delivering delays and increasing costs.
Zillow (ZG), the online real estate database company, jumped after hours as third quarter earnings topped estimates.
Booking Holdings (BKNG), one of the largest online travel companies, reported third quarter adjusted EPS of 12.27 dollars, missing estimates, down from 45.36 dollars a year ago on revenue of 2.6 billion dollars, above forecasts, down from 5.0 billion dollars a year earlier.
AIG (AIG), a global insurance and financial services firm, announced third quarter adjusted EPS of 0.81 dollar, beating forecasts, up from 0.56 dollar a year ago.
Monster Beverage (MNST), a developer and marketer of energy drinks, disclosed third quarter EPS of 0.65 dollar, just above estimates, up from 0.55 dollar a year ago on sales of 1.3 billion dollars, also just beating the consensus, up from 1.1 billion dollars a year earlier.
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.