





AUD/USD clings to key trendline heading into US inflation
A dovish RBA meeting and stronger US dollar ahead of a key US inflation report has kept AUD/USD pinned to a key support level. And odds of it making a meaningful recovery this week appear low, without a surprise downside miss from US CPI. Which again, seems unlikely.
Share this:

Fed to pause in Jan?
90% of economists are backing a 25bp Fed cut next week and for them to pause in January, according to a Reuters poll. This is similar to market pricing, with Fed fund futures implying an 86.1% chance of a cut next week and 90.4% chance of a pause at their following meeting.
The same poll estimates the Fed funds to fall to 3.5% to 3.75% or lower by the end of 2025, which leaves room for a minimum of 100bp of cuts (three cuts next year to follow one this month).
RBA open the door to cuts
The RBA held rates at 4.35% as expected, tipped their hat to “weak growth”, noted lower “upside risks to inflation” and removed a key part of their statement hinting at a potential hike. By effectively removing their hawkish bias from the statement, the door has now been opened for the cut markets have been pricing in.
Governor bullock hit the wires after the meeting to say that while upside inflation risks have eased, they have not gone away. Regardless, RBA cash rate futures maintained their convictions of three cuts to arrive next year, having fully priced in a 25bp cut in April, July and December.
View my take on RBA statement in yesterday’s video: The RBA just made a small (but big) change to their statement
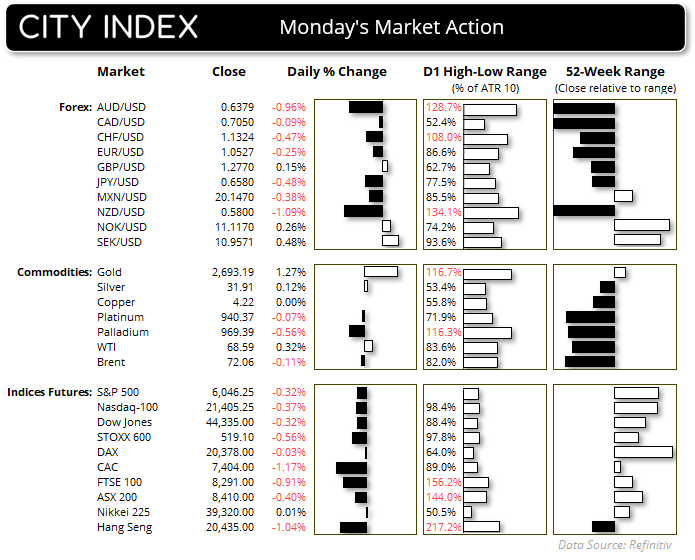
Wall Street indices continued lower on Tuesday ahead of a key US inflation report later today. The S&P 500 and Nasdaq were down for a second day while the Dow Jones tallied up its fourth bearish day. It is plausible to think that traders are taking a breather after pushing indices to record highs, knowing that if Santa's rally is to play out this year it tends to come in the second half of the month. The weak performance of Wall Street also weighed on ASX 200 futures which are now -2% off the record high, after last week’s soft GDP figures weighed on local sentiment.
USD/JPY reached my 152 target outlined in yesterday’s report and shows the potential to extend its gains should US inflation come in slightly hot. USD/CAD briefly touched a 4-year and 8-month high ahead of the BOC meeting. USD/CHF bounced off the August high and invalidated the head and shoulders top, which I suggested could happen last week. And it shows further upside potential over the near term.

Economic events in focus (AEDT)
The consensus is for the Bank of Canada to cut rates by 50bp to 3.25% but signal a slower pace of easing next year. This makes sense, as it allows them to get said cuts out of the way and reassess as the political landscape and inevitable trade tug-o-war develops next year with Trump.
US inflation is the main event, although forecasts are a tad uninspiring with core CPI expected to remain steady at 2.7% y/y and 0.3% m/m. But anything higher could further support the USD, raise the odds of a December pause for the Fed and potentially see AUD/USD break key support.
- 10:50 – JP PPI
- 12:30 – RBA chart pack
- 21:00 – OPEC monthly report
- 00:30 – US core CPI
- 01:45 – BOC interest rate decision (-50bp cut expected)
AUD/USD technical analysis:
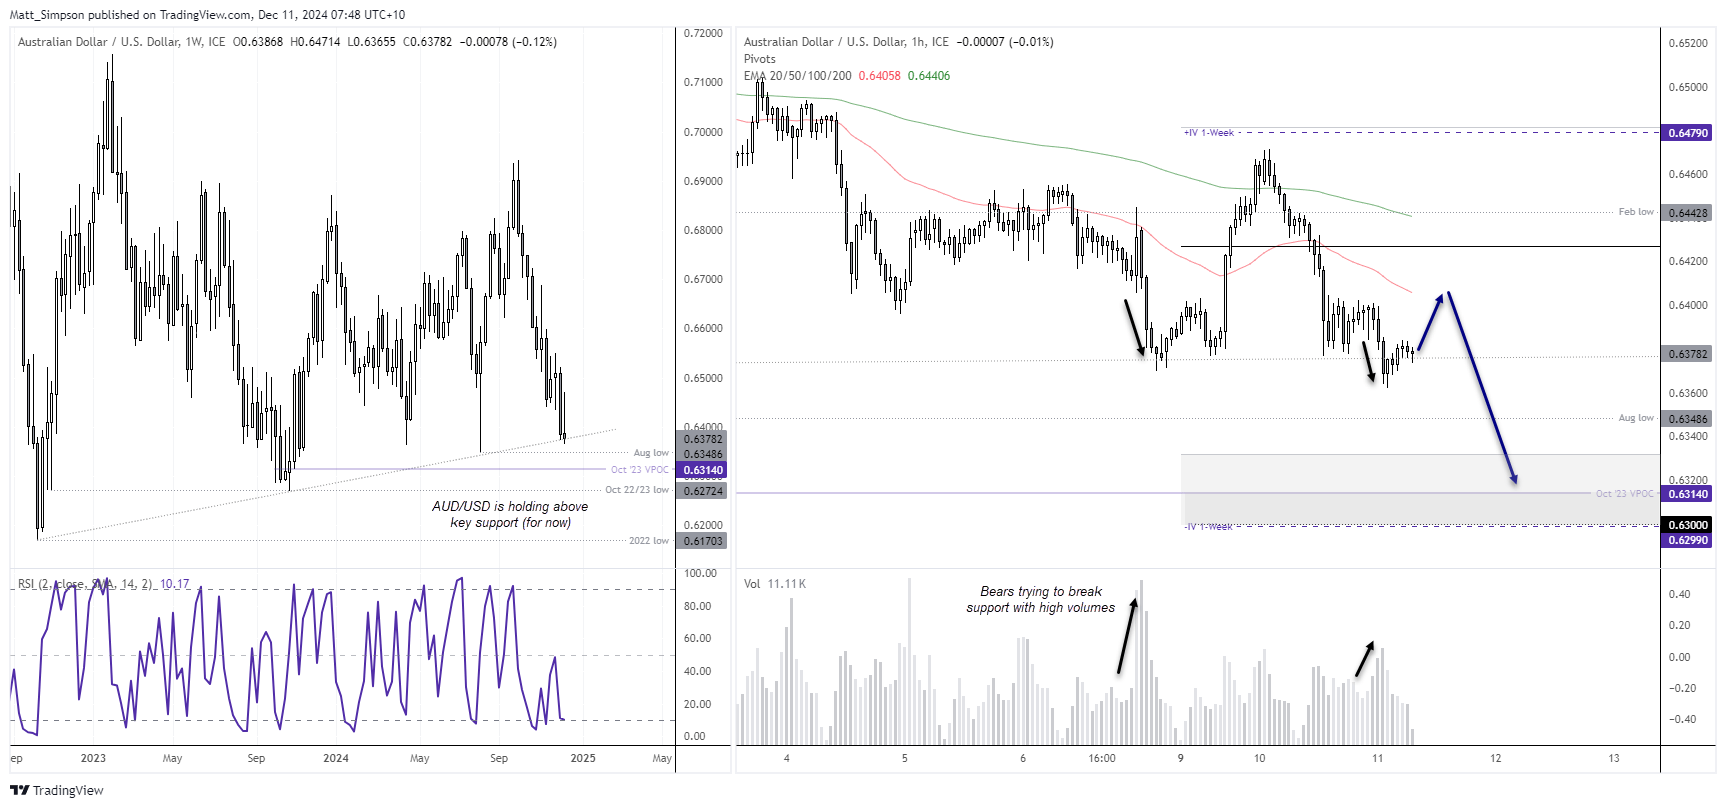
At current levels, AUD/USD is trying to form an inverted hammer at a key support level (2022 trendline). But it seems unlikely we’ll close the week at this level with US Inflation data pending. We’re therefor on guard for a breakdown or bounce from current levels.
The best bet the Aussie has for a rally appears to be in the hands of a weak US inflation report, which seems unlikely.
The 1-hour chart shows the swift reversal lower from Tuesday’s high. A false break of the 2022 trendline shows a slight hesitancy to roll over for now and raises the potential for a minor bounce in today’s Asian session. But given the daily bearish trend and potential for a stronger US dollar and weaker yuan (which AUD shares a strong correlation with), I suspect any such bounce will be seen as a gift for bears who are eyeing a move towards 63c.
Note the lower weekly implied volatility sits neat 63c, with a historical VPOC also close by for potential support.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

Japanese Yen Outlook: USD/JPY, GBP/JPY, AUD/JPY Setups
USD/JPY and GBP/JPY show signs of stabilising, while AUD/JPY remains vulnerable as yen crosses deliver mixed technical signals.

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.