



Dow Jones Forecast: DJIA eases from record high with data in focus
US stocks are heading for a slightly lower open on Thursday after a muted close in the previous session amid mixed economic data, which is maintaining uncertainty over the Fed's path forward.The US NFP report is due tomorrow, which could be the next key catalyst.
Share this:
US futures
Dow futures -0.2%, S&P futures -0.2% & Nasdaq futures -0.7%
In Europe
FTSE -0.2%6 & DAX 0.15%
- Stocks slip lower on Thursday
- Geoplitics remain on the radar
- US jobless claims rise to 208k ahead of tomorrow’s NFP
- Oil rebounds 2%
Stocks ease back from record high
US stocks are heading for a slightly lower open on Thursday after a muted close in the previous session amid mixed economic data, which is maintaining uncertainty over the Fed's path forward. The US NFP report is due tomorrow, which could be the next key catalyst.
US jobless claims rose by 8k to 208K, up from 200K in the previous week but below expectations of 213k. The four-week moving average of initial claims fell by 7000 the 212K, marking the lowest level since April 27, 2024.
The data comes after ADP payrolls JOLTS job openings pointed to a low-hire, low-fire environment. However, the ISM services PMI was stronger than expected, painting a mixed picture for the Federal Reserve and potentially encouraging a cautious stance from the central bank toward further rate cuts.
This week's data comes ahead of Friday's nonfarm payroll report, which is expected to show that headline job creation rose by 60,000, down from 64,000 in November. However, the unemployment rate is expected to decline to 4.5% from 4.6%.
The market is pricing in two Fed rate cuts this year; however, the Fed indicated one rate cut in 2026 in its December meeting.
Corporate news
Alphabet is rising almost 1% after the Google parent sees ongoing demand following its market capitalization rising above Apple's for the first time since 2019.
NVIDIA is rising 0.4% on reports that China is preparing to approve some purchases of H200 AI chips as early as this quarter, and a move that could reopen access to a key market for the chipmaker.
RTX, Lockheed Martin and Northrop Grumman are gaining between 5 to 7% as investors buy into the defence stocks following Trump floating the idea of lifting the 2027 US defence budget to 1.5 trillion U.S. dollars. These stocks are rebounding after sharp losses yesterday, when Trump vowed to block defence contractors from paying dividends or buying back shares until they accelerate weapon production.
S&P 500 forecast – technical analysis.
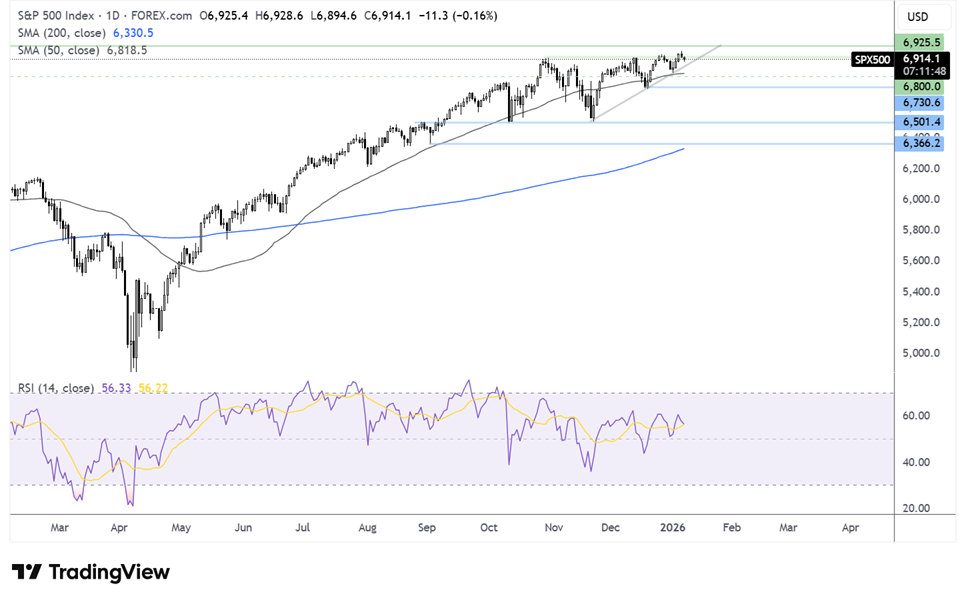
The S&P500 recovered from the 6500 November low, rising to a fresh record high of 6965 yesterday. The price has since eased back slightly to 6910 at the time of writing. The price continues to hold above its rising trendline and 50 SMA. Buyers will look to extend the uptrend, rising towards 7000 as the next logical level. Support is at 6885, the trendline. Below here 6820 comes into play, the 50 SMA ahead of 6715, the December low.
FX markets – USD rises, EUR/USD slips
The U.S. dollar is rising to a monthly high after US jobless claims were lower than expected. The data comes after yesterday's stronger-than-expected ISM services PMIs.
EUR/USD is falling to a fourth-month low against a stronger USD amid a souring market mood, despite eurozone unemployment unexpectedly falling to 6.3% in November, down from 6.4%. Economic sentiment indicators have also exceeded forecasts, with consumer, business, and industrial sentiment rising.
GBP/USD is edging lower for a third day on USD strength. The quiet UK economic calendar means that GBP is being driven mainly by risk sentiment. The next major macro event will be the UK employment data next week.
Oil rebounds 2%
Oil prices are rebounding after recent losses. Oil prices are rising 2%, recovering this week’s losses as fears over Venezuela ease and investors digest recent data.
Oil had been under pressure following the U.S. announcement of plans to import 50 million barrels of Venezuelan crude, adding to concerns about an already oversupplied market. However, the market also expects that increased supply will take time to ease immediate oversupply concerns.
Data is helping to put a near-term floor under crude oil prices. US crude stockpiles fell more than expected, indicating demand strength. Together with a stronger-than-expected US ISM services PMI and jobless claims have helped support prices for now.
Investors will continue to monitor geopolitical developments, particularly reports in the Wall Street Journal that Trump plans to assume long-term control of Venezuela's oil to bring prices down to $50 per barrel.
.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Wall Street Forecast: DJIA falls as treasury yields hit new highs and ahead of the Trump-Xi summit
U.S. stocks are falling, further extending losses from the previous session, as oil prices move higher alongside Treasury yields and caution reigns ahead of the summit between President Trump and Xi Jinping.
GBP/USD, DJIA Outlook: Support Levels Meet Oversold Risks
GBP/USD and the Dow test key support levels as rising Treasury yields, Fed rate-hike expectations and oversold momentum increase reversal risks.


USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.