




FTSE at key support with pound struggling amid Brexit uncertainty
The major equity indices in Europe started today’s session on the backfoot this morning.
Share this:

The major equity indices in Europe started today’s session on the backfoot this morning. Was this perhaps because of fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. But with major central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now, anyway. And we, too, continue to favour the bulls’ case rather than the bears’ in the short-term outlook even if the macro picture continues to deteriorate.
Today saw manufacturing PMIs from several economic regions fall further below the boom/bust level of 50, pointing to falling activity and underscoring the need for further monetary stimulus by major central banks. The Reserve Bank of Australia became the latest central bank to cut interest rates in this global easing phase. At 0.75%, the benchmark interest rate is at a record low in Down Under, with the RBA hinting that ore cuts could be on the way should the economy warrant it.
However, there was good news from the UK. Here, the PMI rose to 48.1 from 47.4 previously, beating analysts’ expectations. However, as my colleague Fiona Cincotta had envisaged, the gains for the pound was short-lived – in part because new orders and the employment components of the PMI data painted a grim picture. What’s more, with Brexit being just one month away, traders’ focus remained firmly on that rather than the economy. On that note, Boris Johnson is expected to submit formal proposals for an alternative to the Irish backstop on Wednesday. It remains to be seen whether the EU would accept it. The uncertainty is likely to keep the pound undermined, and paradoxically the FTSE underpinned. Remember the FTSE tends to react positively to a falling pound, given that the index is made up of large multi-national corporations whose foreign earnings will be boosted by a falling exchange rate.
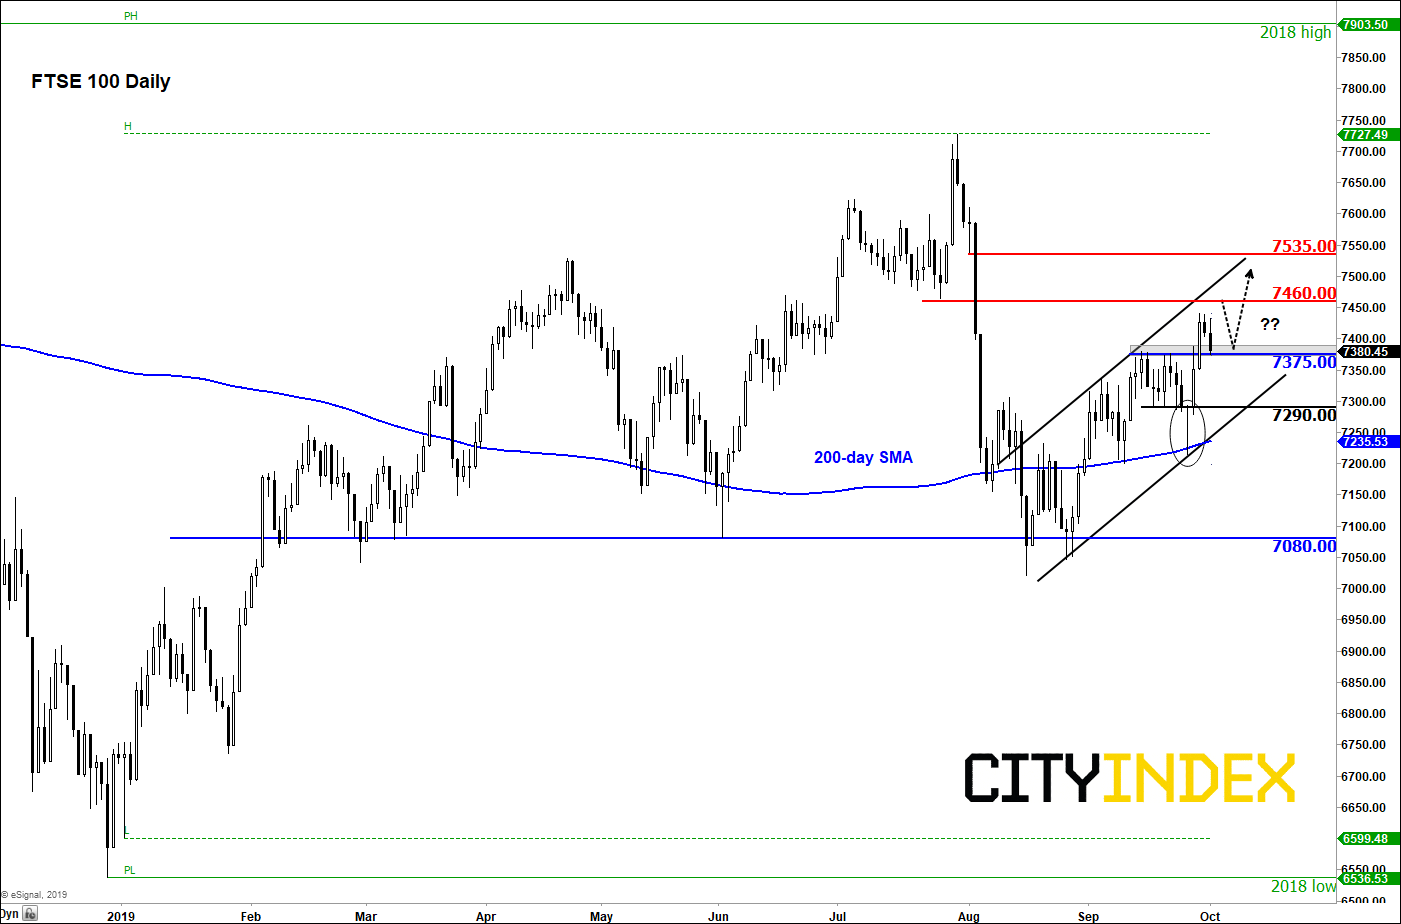
From a technical point of view, traders may wish to watch the FTSE closely here, because (1) it has shown strong bullish signals of late and (2) it was testing a key support level at the time of writing. The UK benchmark index was probing support at around 7375, a level which had been resistance in the past. Recently, the index has been rising inside a bullish channel and found support on a number of occasions from its now-rising 200-day moving average. So, given the overall bullish characteristics of the FTSE, and with the benchmark indices in the US being so close to their record high levels, I think the UK index has a good chance to bounce here and resume higher. However, if the 7375 level breaks on a closing basis then that could see the index drop back to the support trend of the rising channel and the next key support around 7290 area again.Source: eSignal and City Index. Please note this product may not be available to trade in all regions.
The major equity indices in Europe started today’s session on the backfoot this morning. Was this perhaps because of fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. But with major central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now, anyway. And we, too, continue to favour the bulls’ case rather than the bears’ in the short-term outlook even if the macro picture continues to deteriorate.
Today saw manufacturing PMIs from several economic regions fall further below the boom/bust level of 50, pointing to falling activity and underscoring the need for further monetary stimulus by major central banks. The Reserve Bank of Australia became the latest central bank to cut interest rates in this global easing phase. At 0.75%, the benchmark interest rate is at a record low in Down Under, with the RBA hinting that ore cuts could be on the way should the economy warrant it.
However, there was good news from the UK. Here, the PMI rose to 48.1 from 47.4 previously, beating analysts’ expectations. However, as my colleague Fiona Cincotta had envisaged, the gains for the pound was short-lived – in part because new orders and the employment components of the PMI data painted a grim picture. What’s more, with Brexit being just one month away, traders’ focus remained firmly on that rather than the economy. On that note, Boris Johnson is expected to submit formal proposals for an alternative to the Irish backstop on Wednesday. It remains to be seen whether the EU would accept it. The uncertainty is likely to keep the pound undermined, and paradoxically the FTSE underpinned. Remember the FTSE tends to react positively to a falling pound, given that the index is made up of large multi-national corporations whose foreign earnings will be boosted by a falling exchange rate.
From a technical point of view, traders may wish to watch the FTSE closely here, because (1) it has shown strong bullish signals of late and (2) it was testing a key support level at the time of writing. The UK benchmark index was probing support at around 7375, a level which had been resistance in the past. Recently, the index has been rising inside a bullish channel and found support on a number of occasions from its now-rising 200-day moving average. So, given the overall bullish characteristics of the FTSE, and with the benchmark indices in the US being so close to their record high levels, I think the UK index has a good chance to bounce here and resume higher. However, if the 7375 level breaks on a closing basis then that could see the index drop back to the support trend of the rising channel and the next key support around 7290 area again.Source: eSignal and FOREX.com. Please note this product may not be available to trade in all regions.
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.

Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum


S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.