


Indices weekly outlook: DAX forecast
The week ahead is set to be a busy one for the earnings calendar, while the macro calendar is again set to be quieter with the ongoing US government shutdown delaying the release of data there. Elsewhere, UK CPI on Wednesday and Global PMIs on Friday should bring about a bit of volatility for European markets. Among the indices to watch is the German DAX index this week, with the release of a few major company results to set the tone, including SAP in mid-week.
Share this:
The week ahead is set to be a busy one for the earnings calendar, while the macro calendar is again set to be quieter with the ongoing US government shutdown delaying the release of data there. Elsewhere, UK CPI on Wednesday and Global PMIs on Friday should bring about a bit of volatility for European markets. Among the indices to watch is the German DAX index this week, with the release of a few major company results to set the tone, including SAP in mid-week. With the impact of the huge fiscal push that could reshape sentiment in Europe to come, we maintain a bullish DAX forecast following the recent volatility.
The DAX took a hit last week, along with global markets, although finished the week off its worst levels on Friday. Between renewed US-China trade tension, credit risk in US regional banks, and stretched equity valuations, there was plenty to worry about last week. Yet, as we’ve seen time and again in 2025, all it takes is one optimistic headline — or even a single Trump post — to turn sentiment on its head. And that is what markets got on Friday when a Trump interview led investors to believe a deal with China to at least extend the trade war truce is forthcoming.
DAX forecast: EU equities still have reasons to stay upbeat
Despite weak data out of Germany, European stock market investors aren’t without hope. France’s recent political stability has helped calm nerves, sending the CAD sharply higher last week. What’s more, falling oil prices are easing inflation pressures. Add to that the growing conviction that the Fed could deliver two rate cuts before year-end, and the downside for equities looks limited.
But perhaps the biggest stimulus is Germany’s fiscal plans. Berlin’s €500 billion infrastructure package — alongside another €500 billion for defence and green initiatives — could provide a long-term lift to the Eurozone economy. That kind of spending backdrop doesn’t come around often, and it’s tough to stay bearish when policymakers are clearly shifting towards growth. Granted, the tangible economic benefits may not fully materialize until 2026, but the psychological impact is already being felt. That’s supportive for the DAX forecast, even if traders remain hesitant until they see results in hard data. For now, soft German industrial output and fading consumer sentiment have kept the European Central Bank’s dovish camp in control, hinting at the possibility of one more rate cut next year.
The week ahead: UK CPI, global PMIs and company earnings
- UK CPI
Wednesday, October 22
There’s been some concern over the UK government’s upcoming budget that could lose investor confidence, specifically Chancellor Reeve’s reliance on tax rises over spending cuts to meet her fiscal rules is what worries investors. UK data has also been mixed recently and the pound has eased back. With budget uncertainty at the forefront, the FTSE could drop sharply if CPI raises stagflation worries in the UK, although the UK 100 did form a bullish hammer candle on Friday to suggest the low might be in after the recent dip.
- Global PMIs
Friday, October 24
We have seen a number of weaker hard data from the Eurozone’s largest economy Germany of late, and this has held back the euro. Meanwhile political crisis in France has weighed on business and consumer sentiment there. Will Eurozone PMIs surprise to the downside? If they do, this will only underscore the need for more fiscal stimulus from Germany.
- Possible release of US data
US government data releases have been impacted by the ongoing government shutdown. The non-farm payrolls were among a number of government reports that were due for release, but never arrived. If the government re-opens, we could see a raft of US data releases in the week ahead. But there are no certainties, and are subject to delay, revision, or cancellation. Media reports suggest CPI could be released on Friday, October 24.
German company earnings
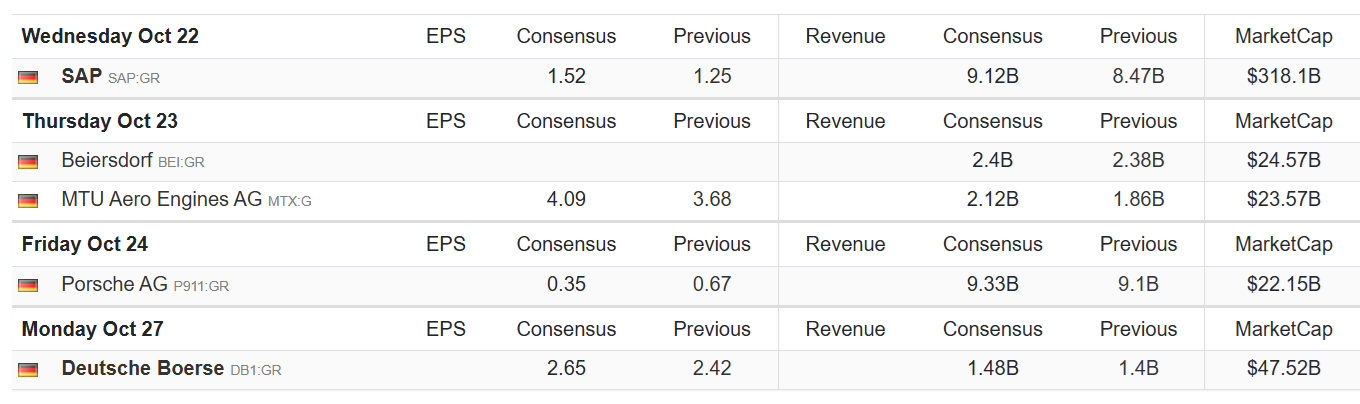
The week ahead features a handful of Frankfurt-listed corporate earnings, with SAP set to kick things off on Wednesday. Here’s what’s coming up in the week ahead, which has the potential to impact the DAX forecast:
Source: tradingeconomics.com
Technical analysis: DAX outlook positive – for now
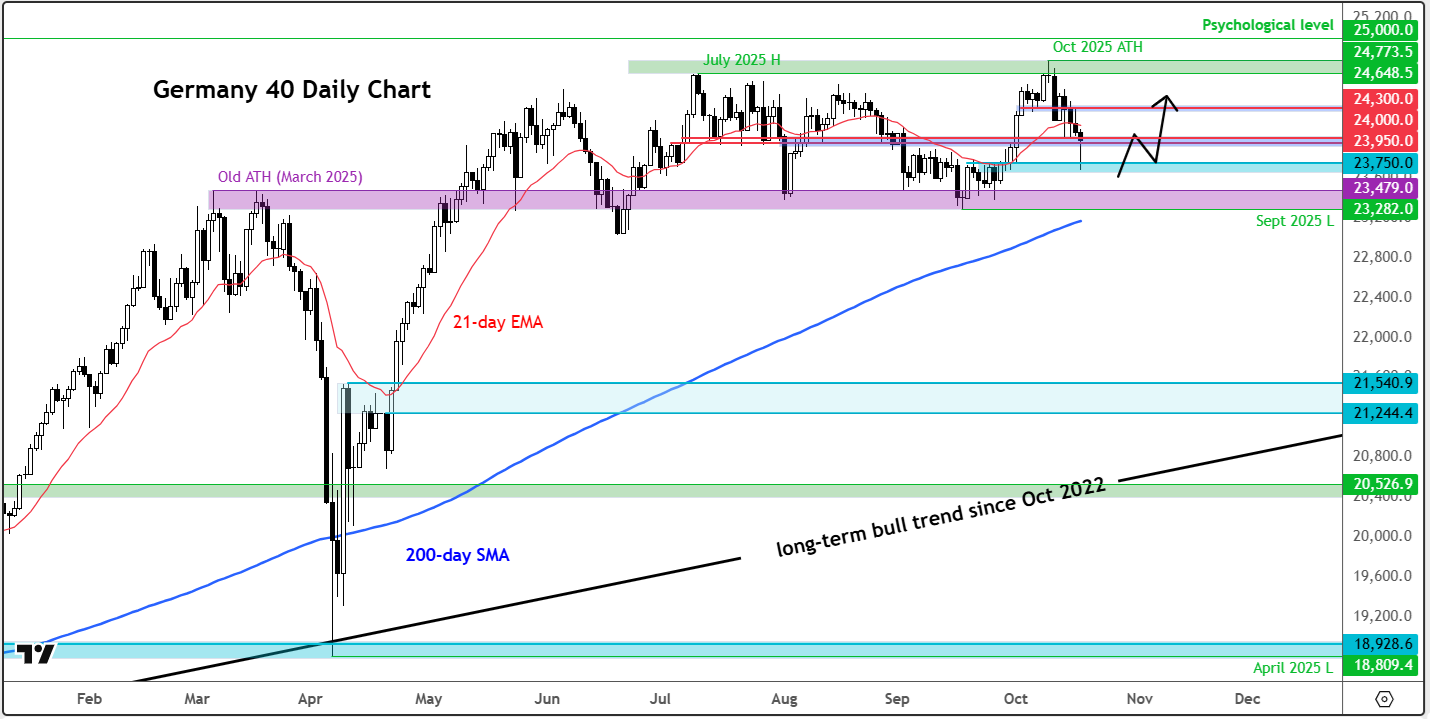
From a technical perspective, the DAX’s slide last week came as a surprise — especially after breaking to fresh highs just a week earlier. Still, the bulls deserve the benefit of the doubt. The index has held the first retest of a key inflection zone near 23,700–23,750, an area that served as the breakout level not long ago. If buyers defend this region, we could see another leg higher. Should that fail, the next major support lies around 23,280–23,480, marking a massif area of prior support and resistance.
Meanwhile resistance sits at 23,950 and 24,000, where the index closed Friday’s session at. A clean break above this area could open the door to the next resistance near 24,300. Above that? Fresh record highs and potentially the 25,000 handle.


-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.