



Morrisons turns a corner
Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Share this:

Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Wm. Morrisons’ special dividend announcement caps a half-year performance by the number-four UK supermarket that looks relatively solid, considering its less than optimal industry position and underlying sales growth that’s seen it pace only the worst performer among established chains, Sainsbury’s, for several quarters. The stock is faring better than its larger rival as the latter continues to lick its wounds after failing to buy Asda. MRW’s 4% so far this year fall compares with a 19% slump by SBRY. That nevertheless demonstrates widely disparate sentiment versus market leader, Tesco, whose long-standing efficiency and growth drive is now reaping benefits warranting a 2019 advance of 25%.
True, Morrisons’ key second-quarter sales—at stores open for at least a year and excluding fuel—were always going to struggle to match Q2 2018’s 6.3% surge. Then, the entire sector was buoyed by beautiful British weather, a royal wedding and the World Cup. In the end though, a 1.9% fall over the quarter to early August this year wasn’t as bad as widely expected. An in-line interim dividend garnished with a ‘special’ one-off payment helps convey the expectation that Morrisons’ strategy is showing increasing traction.
The strategy includes an expanded partnership with Amazon, that ought to provide further reassurance of some protection from the disruptive e-commerce giant. Morrison’s storefront on the platform will now distribute to more UK cities. In fact though, a move that MRW trumpets less than the Amazon deal, its tie-in with McColl’s, holds even higher medium-term potential. The arrangement to supply 300 additional units of the McColl’s chain adds volume, whilst a trial conversion of some units to Morrisons stores could boost the move towards higher joint participation. As such, there are now deeper inroads towards the upper end of a targeted £75m-£125m cumulative pre-tax profit after MRW booked £54m mostly from lower finance costs.
Major challenges remain, at both industry level (see Brexit) and for £4.8bn Morrisons. Sales growth per square foot continues to inch up, but growth remains more fragile than top rivals. MRW also still lacks a well-defined convenience format, leaving it vulnerable to challenges that go alongside the problematic online history with Ocado. The group is still catching up. Still, Ebitda margin expansion of 20 basis points in H1 and a £15m rise in underlying free cash flow back the view that an upturn has been seen. Against an action-packed industry backdrop, to say the least, a major takeaway for investors is that Morrisons remains on track to hit milestones that can open the door to further higher than expected cash returns.
Chart thoughts
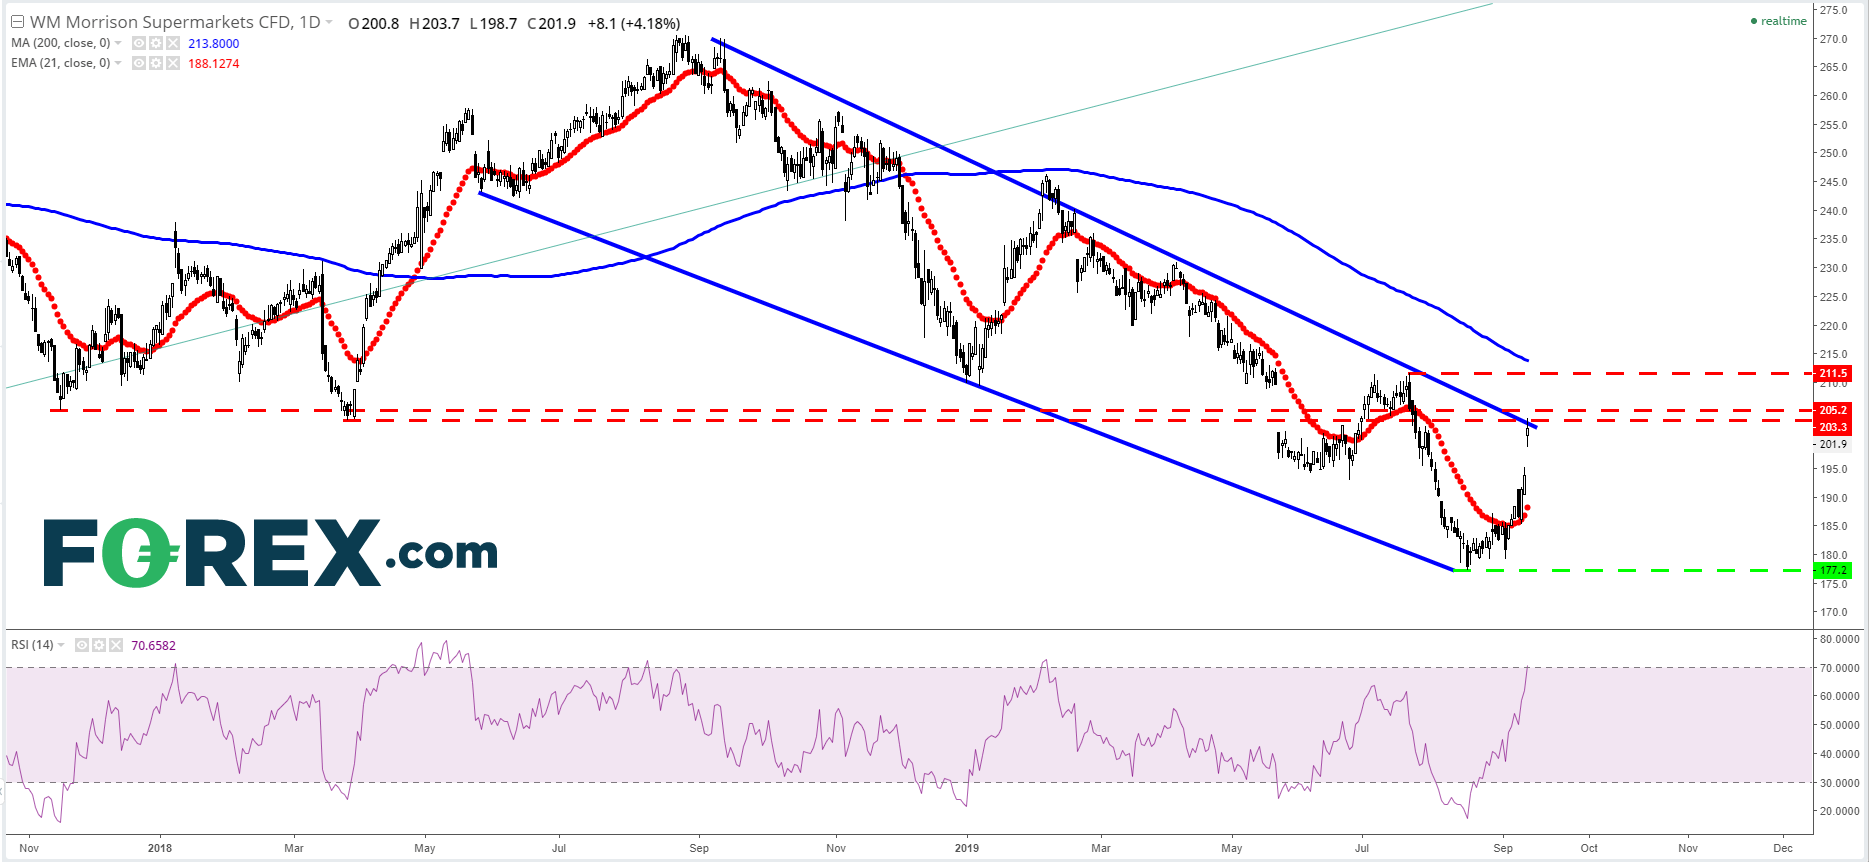
- An almost 3-year uptrend was broken last November, posing an overarching selling bias since then
- Some corroboration of that is shown by MRW’s falling channel in place for almost exactly a year; note Thursday’s rally hit the upper wall of the pattern
- The stock has also rallied to resistance from strongly defended November 2017 and March/April 2018 lows of around 205p and 203p respectively
- Failure here would imply another look at the 177p kick back low from August for support
- The 200-day moving average trends downwards encapsulating long-term weakness, but the 21-day exponential average is a ray of light. Its recent supports points to a possible trend change as it curves attractively upwards
- A break above 22nd July’s 211.5p failure high which was just short of the upper wall looks like it would confirm a turning point for buyers
WM Morrisons CFD – Daily
Source: City Index
Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Wm. Morrisons’ special dividend announcement caps a half-year performance by the number-four UK supermarket that looks relatively solid, considering its less than optimal industry position and underlying sales growth that’s seen it pace only the worst performer among established chains, Sainsbury’s, for several quarters. The stock is faring better than its larger rival as the latter continues to lick its wounds after failing to buy Asda. MRW’s 4% so far this year fall compares with a 19% slump by SBRY. That nevertheless demonstrates widely disparate sentiment versus market leader, Tesco, whose long-standing efficiency and growth drive is now reaping benefits warranting a 2019 advance of 25%.
True, Morrisons’ key second-quarter sales—at stores open for at least a year and excluding fuel—were always going to struggle to match Q2 2018’s 6.3% surge. Then, the entire sector was buoyed by beautiful British weather, a royal wedding and the World Cup. In the end though, a 1.9% fall over the quarter to early August this year wasn’t as bad as widely expected. An in-line interim dividend garnished with a ‘special’ one-off payment helps convey the expectation that Morrisons’ strategy is showing increasing traction.
The strategy includes an expanded partnership with Amazon, that ought to provide further reassurance of some protection from the disruptive e-commerce giant. Morrison’s storefront on the platform will now distribute to more UK cities. In fact though, a move that MRW trumpets less than the Amazon deal, its tie-in with McColl’s, holds even higher medium-term potential. The arrangement to supply 300 additional units of the McColl’s chain adds volume, whilst a trial conversion of some units to Morrisons stores could boost the move towards higher joint participation. As such, there are now deeper inroads towards the upper end of a targeted £75m-£125m cumulative pre-tax profit after MRW booked £54m mostly from lower finance costs.
Major challenges remain, at both industry level (see Brexit) and for £4.8bn Morrisons. Sales growth per square foot continues to inch up, but growth remains more fragile than top rivals. MRW also still lacks a well-defined convenience format, leaving it vulnerable to challenges that go alongside the problematic online history with Ocado. The group is still catching up. Still, Ebitda margin expansion of 20 basis points in H1 and a £15m rise in underlying free cash flow back the view that an upturn has been seen. Against an action-packed industry backdrop, to say the least, a major takeaway for investors is that Morrisons remains on track to hit milestones that can open the door to further higher than expected cash returns.
Chart thoughts
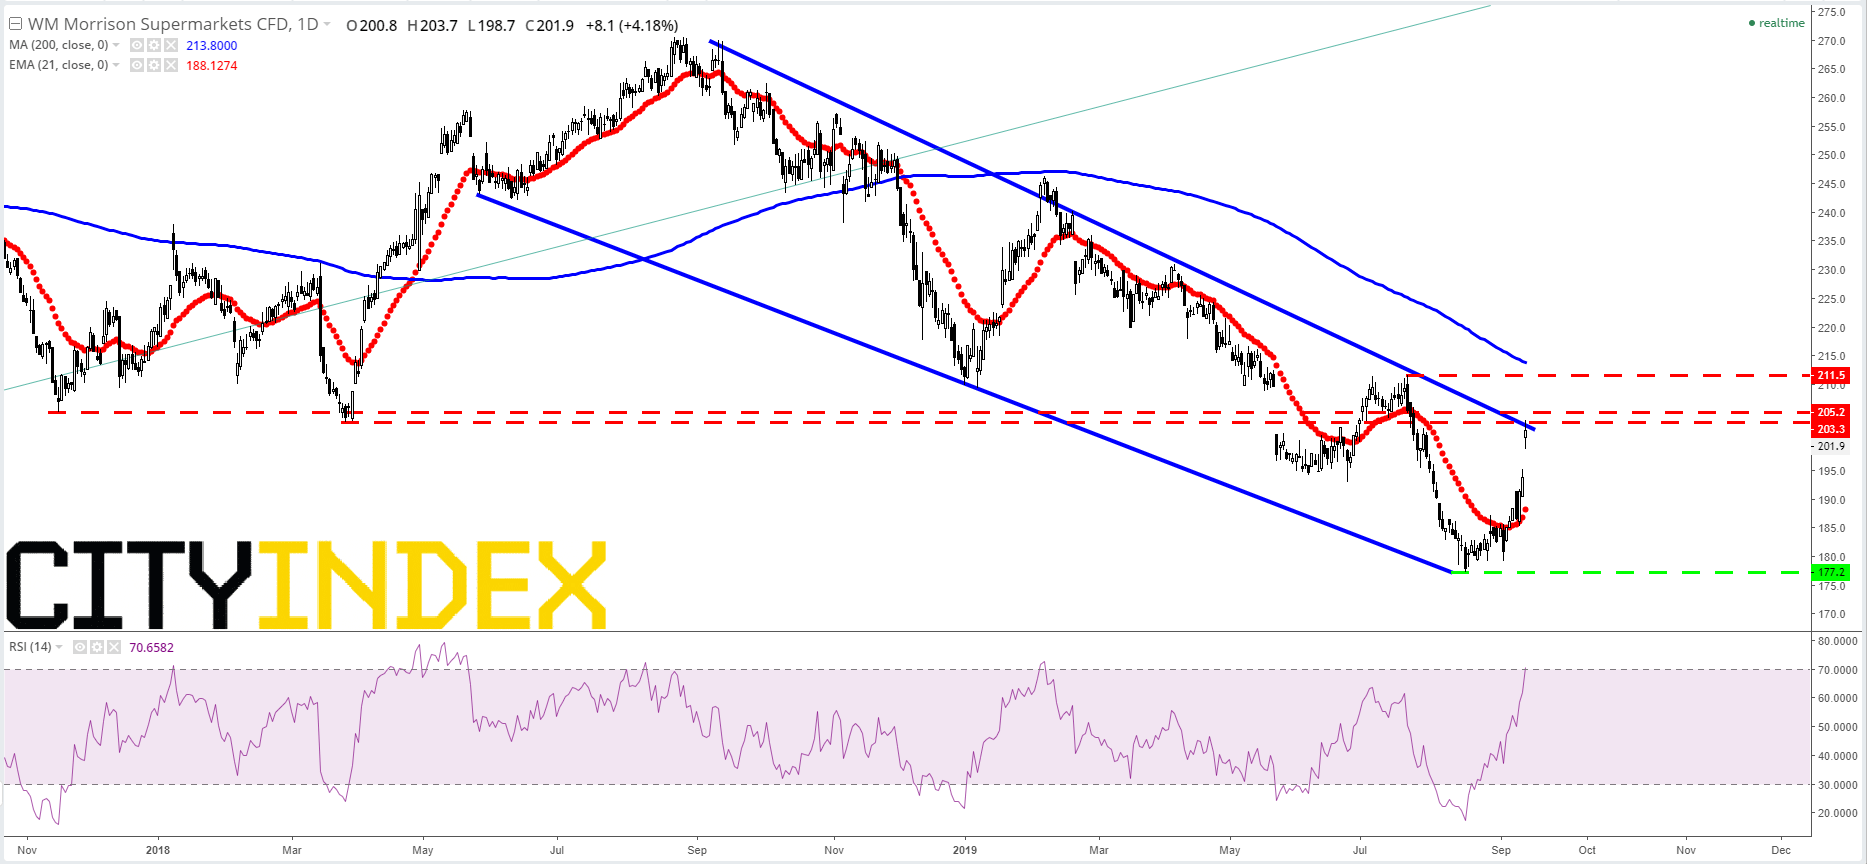
- An almost 3-year uptrend was broken last November, posing an overarching selling bias since then
- Some corroboration of that is shown by MRW’s falling channel in place for almost exactly a year; note Thursday’s rally hit the upper wall of the pattern
- The stock has also rallied to resistance from strongly defended November 2017 and March/April 2018 lows of around 205p and 203p respectively
- Failure here would imply another look at the 177p kick back low from August for support
- The 200-day moving average trends downwards encapsulating long-term weakness, but the 21-day exponential average is a ray of light. Its recent supports points to a possible trend change as it curves attractively upwards
- A break above 22nd July’s 211.5p failure high which was just short of the upper wall looks like it would confirm a turning point for buyers
WM Morrisons CFD – Daily
Source: City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

S&P 500, Nasdaq 100 Forecast for the Week Ahead
A hawkish Fed and 10-Year Notes on the verge of a push above 5%, yet stocks have so far shrugged off that fear. But can it continue?


Hang Seng Tech rout nears make-or-break zone
The technical damage is clear, but with Hang Seng Tech now deeply stretched and approaching major support, the risk-reward is becoming more two-sided.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.