



01 09 US PRE OPEN
The S&P 500 Futures are up again after they closed mixed yesterday
Share this:

The S&P 500 Futures are up again after they closed mixed yesterday. Nasdaq 100 hit a fresh record high while the Dow Jones Industrial Average dropped 223 points (-0.8%) and the S&P 500 fell 7 points (+0.2%) to 3500.
Later today, the U.S. Commerce Department will report July construction spending (+1.1% on month expected). The Institute for Supply Management will post August Manufacturing PMI (54.5 expected). Research firm Markit will publish final readings of August Manufacturing PMI (53.6 expected).
European indices have rebounded at the open before facing a consolidation. German Government has revised its 2020 GDP forecast to -5.8%, vs -6.3% previously. It also revised its 2021 GDP forecast to +4.4%, vs +5.2%. Research firm Markit has published final readings of August Manufacturing PMI for the eurozone at 51.7 (as expected), for Germany at 52.2 (vs 53.0 expected), for France at 49.8 (vs 49.0 expected) and for the U.K. at 55.2 (vs 55.3 expected). The European Commission has posted August CPI at -0.2% (vs +0.2% on year expected) and July jobless rate at 7.9% (vs 8.0% expected). The German Federal Statistical Office has reported August jobless rate at 6.4%, as expected. The Bank of England has released the number of mortgage approvals for July at 66,300 (vs 55,500 expected).
Asian indices closed slightly on the upside except the Australian ASX. The Reserve Bank of Australia held its rates unchanged, as expected. Data released earlier today showed that China's Caixin Manufacturing PMI rose to 53.1 in August (52.5 expected), the highest level since January 2011.
WTI Crude Oil futures are rebounding. Abu Dhabi, the biggest oil producer in the United Arab Emirates, said it will reduce exports in that month by 30% below contracted amounts for buyers with long-term agreements. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for August 28.
Gold is well oriented, trading at two-week high, while the US dollar declines on low rates outlook.
Gold rose 21.56 dollars (+1.1%) to 1989.37 dollars.
The dollar index fell 0.32pt to 91.826.
U.S. Equity Snapshot
Zoom Video Communications (ZM), the leader in modern enterprise video communications, soared in extended trading after reporting second quarter adjusted EPS of 0.92 dollar, significantly beating estimates, up from 0.02 dollar last year, on revenue of 663.5 million dollars, also exceeding forecasts, up from 145.8 million dollars a year earlier. The Co raised its third quarter and full year adjusted EPS and revenue forecast.
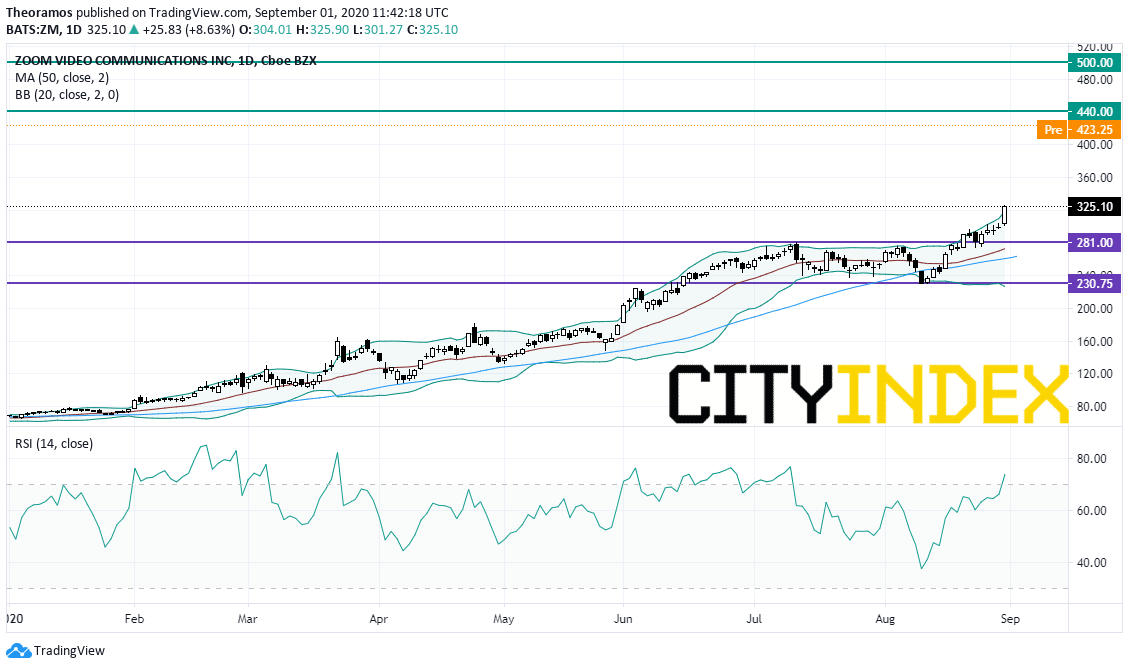
Source: TradingView, GAIN Capital
Apple (AAPL): according to Bloomberg, the tech giant would ship 75 million 5G IPhones for late year.
QUALCOMM (QCOM), a maker of digital wireless communications equipment, is gaining ground before hours as the stock was upgraded to "equal weight" from "underweight" at Wells Fargo.
Later today, the U.S. Commerce Department will report July construction spending (+1.1% on month expected). The Institute for Supply Management will post August Manufacturing PMI (54.5 expected). Research firm Markit will publish final readings of August Manufacturing PMI (53.6 expected).
European indices have rebounded at the open before facing a consolidation. German Government has revised its 2020 GDP forecast to -5.8%, vs -6.3% previously. It also revised its 2021 GDP forecast to +4.4%, vs +5.2%. Research firm Markit has published final readings of August Manufacturing PMI for the eurozone at 51.7 (as expected), for Germany at 52.2 (vs 53.0 expected), for France at 49.8 (vs 49.0 expected) and for the U.K. at 55.2 (vs 55.3 expected). The European Commission has posted August CPI at -0.2% (vs +0.2% on year expected) and July jobless rate at 7.9% (vs 8.0% expected). The German Federal Statistical Office has reported August jobless rate at 6.4%, as expected. The Bank of England has released the number of mortgage approvals for July at 66,300 (vs 55,500 expected).
Asian indices closed slightly on the upside except the Australian ASX. The Reserve Bank of Australia held its rates unchanged, as expected. Data released earlier today showed that China's Caixin Manufacturing PMI rose to 53.1 in August (52.5 expected), the highest level since January 2011.
WTI Crude Oil futures are rebounding. Abu Dhabi, the biggest oil producer in the United Arab Emirates, said it will reduce exports in that month by 30% below contracted amounts for buyers with long-term agreements. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for August 28.
Gold is well oriented, trading at two-week high, while the US dollar declines on low rates outlook.
Gold rose 21.56 dollars (+1.1%) to 1989.37 dollars.
The dollar index fell 0.32pt to 91.826.
U.S. Equity Snapshot
Zoom Video Communications (ZM), the leader in modern enterprise video communications, soared in extended trading after reporting second quarter adjusted EPS of 0.92 dollar, significantly beating estimates, up from 0.02 dollar last year, on revenue of 663.5 million dollars, also exceeding forecasts, up from 145.8 million dollars a year earlier. The Co raised its third quarter and full year adjusted EPS and revenue forecast.
Source: TradingView, GAIN Capital
Apple (AAPL): according to Bloomberg, the tech giant would ship 75 million 5G IPhones for late year.
QUALCOMM (QCOM), a maker of digital wireless communications equipment, is gaining ground before hours as the stock was upgraded to "equal weight" from "underweight" at Wells Fargo.
The S&P 500 Futures are up again after they closed mixed yesterday. Nasdaq 100 hit a fresh record high while the Dow Jones Industrial Average dropped 223 points (-0.8%) and the S&P 500 fell 7 points (+0.2%) to 3500.
Later today, the U.S. Commerce Department will report July construction spending (+1.1% on month expected). The Institute for Supply Management will post August Manufacturing PMI (54.5 expected). Research firm Markit will publish final readings of August Manufacturing PMI (53.6 expected).
European indices have rebounded at the open before facing a consolidation. German Government has revised its 2020 GDP forecast to -5.8%, vs -6.3% previously. It also revised its 2021 GDP forecast to +4.4%, vs +5.2%. Research firm Markit has published final readings of August Manufacturing PMI for the eurozone at 51.7 (as expected), for Germany at 52.2 (vs 53.0 expected), for France at 49.8 (vs 49.0 expected) and for the U.K. at 55.2 (vs 55.3 expected). The European Commission has posted August CPI at -0.2% (vs +0.2% on year expected) and July jobless rate at 7.9% (vs 8.0% expected). The German Federal Statistical Office has reported August jobless rate at 6.4%, as expected. The Bank of England has released the number of mortgage approvals for July at 66,300 (vs 55,500 expected).
Asian indices closed slightly on the upside except the Australian ASX. The Reserve Bank of Australia held its rates unchanged, as expected. Data released earlier today showed that China's Caixin Manufacturing PMI rose to 53.1 in August (52.5 expected), the highest level since January 2011.
WTI Crude Oil futures are rebounding. Abu Dhabi, the biggest oil producer in the United Arab Emirates, said it will reduce exports in that month by 30% below contracted amounts for buyers with long-term agreements. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for August 28.
Gold is well oriented, trading at two-week high, while the US dollar declines on low rates outlook.
Gold rose 21.56 dollars (+1.1%) to 1989.37 dollars.
The dollar index fell 0.32pt to 91.826.
U.S. Equity Snapshot
Zoom Video Communications (ZM), the leader in modern enterprise video communications, soared in extended trading after reporting second quarter adjusted EPS of 0.92 dollar, significantly beating estimates, up from 0.02 dollar last year, on revenue of 663.5 million dollars, also exceeding forecasts, up from 145.8 million dollars a year earlier. The Co raised its third quarter and full year adjusted EPS and revenue forecast.

Source: TradingView, GAIN Capital
Apple (AAPL): according to Bloomberg, the tech giant would ship 75 million 5G IPhones for late year.
QUALCOMM (QCOM), a maker of digital wireless communications equipment, is gaining ground before hours as the stock was upgraded to "equal weight" from "underweight" at Wells Fargo.
Later today, the U.S. Commerce Department will report July construction spending (+1.1% on month expected). The Institute for Supply Management will post August Manufacturing PMI (54.5 expected). Research firm Markit will publish final readings of August Manufacturing PMI (53.6 expected).
European indices have rebounded at the open before facing a consolidation. German Government has revised its 2020 GDP forecast to -5.8%, vs -6.3% previously. It also revised its 2021 GDP forecast to +4.4%, vs +5.2%. Research firm Markit has published final readings of August Manufacturing PMI for the eurozone at 51.7 (as expected), for Germany at 52.2 (vs 53.0 expected), for France at 49.8 (vs 49.0 expected) and for the U.K. at 55.2 (vs 55.3 expected). The European Commission has posted August CPI at -0.2% (vs +0.2% on year expected) and July jobless rate at 7.9% (vs 8.0% expected). The German Federal Statistical Office has reported August jobless rate at 6.4%, as expected. The Bank of England has released the number of mortgage approvals for July at 66,300 (vs 55,500 expected).
Asian indices closed slightly on the upside except the Australian ASX. The Reserve Bank of Australia held its rates unchanged, as expected. Data released earlier today showed that China's Caixin Manufacturing PMI rose to 53.1 in August (52.5 expected), the highest level since January 2011.
WTI Crude Oil futures are rebounding. Abu Dhabi, the biggest oil producer in the United Arab Emirates, said it will reduce exports in that month by 30% below contracted amounts for buyers with long-term agreements. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for August 28.
Gold is well oriented, trading at two-week high, while the US dollar declines on low rates outlook.
Gold rose 21.56 dollars (+1.1%) to 1989.37 dollars.
The dollar index fell 0.32pt to 91.826.
U.S. Equity Snapshot
Zoom Video Communications (ZM), the leader in modern enterprise video communications, soared in extended trading after reporting second quarter adjusted EPS of 0.92 dollar, significantly beating estimates, up from 0.02 dollar last year, on revenue of 663.5 million dollars, also exceeding forecasts, up from 145.8 million dollars a year earlier. The Co raised its third quarter and full year adjusted EPS and revenue forecast.
Source: TradingView, GAIN Capital
Apple (AAPL): according to Bloomberg, the tech giant would ship 75 million 5G IPhones for late year.
QUALCOMM (QCOM), a maker of digital wireless communications equipment, is gaining ground before hours as the stock was upgraded to "equal weight" from "underweight" at Wells Fargo.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?


USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.