




24 07 US PRE OPEN
The S&P 500 Futures remain on the downside after they encountered a sell-off yesterday
Share this:

The S&P 500 Futures remain on the downside after they encountered a sell-off yesterday. Market sentiment was dampened by a spike in unemployment claims and worries of a new round of lockdowns amid rising coronavirus cases.
Due later today are reports on Markit U.S. Manufacturing Purchasing Managers' Index (a rise in July preliminary reading to 52.0 expected) and New Homes Sales (an increase in June annualized rate of 700,000 units expected).
European indices are in the red. Research firm Markit has published preliminary readings of July Manufacturing PMI for the eurozone at 51.1 (vs 50.0 expected), for Germany at 50.0 (vs 48.0 expected), for France at 52.0 (vs 53.2 expected) and for the U.K. at 53.6 (vs 52.0 expected). Also, preliminary readings of June Services PMI was published for the eurozone at 55.1 (vs 51.0 expected), for Germany at 56.7 (vs 50.5 expected), for France at 57.8 (vs 52.3 expected) and for the U.K. at 56.6 (vs 51.5 expected). The U.K. Office for National Statistics has posted June retail sales at +13.9% (vs +8.0% on month expected). The July Gfk Consumer Confidence was released at -27.0 vs -24.0 expected.
Asian indices all closed in the red. Government data showed that New Zealand recorded a trade surplus of NZ$0.43 billion in June (NZ$0.45 billion surplus expected), where exports totaled NZ$5.07 billion dollars (as expected).
WTI Crude Oil futures are under pressure. Later today, Baker Hughes will report the oil rig counts for the U.S. and Canada.
Gold remains firm close to 1,900 dollars while the yen increased to a one-month high on China-US tensions.
Gold rose 4.58 dollars (+0.24%) to 1892.02 dollars.
USD/JPY fell 61pips to 106.25.
U.S. Equity Snapshot
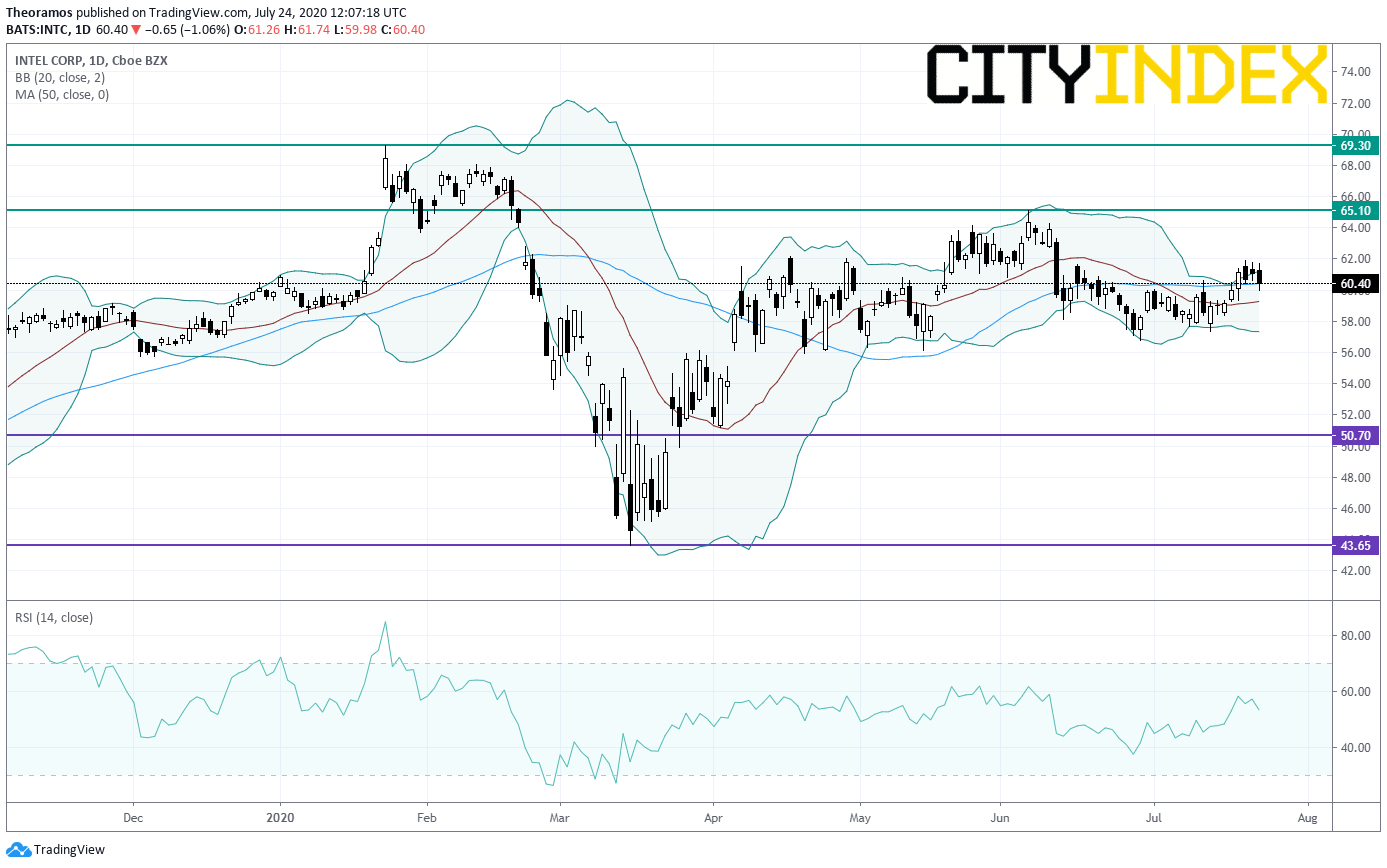
Intel (INTC), a designer and manufacturer of microprocessors, plunged after hours after warning that the "company's 7nm-based CPU product timing is shifting approximately six months relative to prior expectations." Rival Advanced Micro Devices (AMD) gained ground following that release.
Source: TradingView, Gain Capital
Goldman Sachs (GS), the banking group, reached a 3.9 billion dollars agreement to settle charges related to Malaysian sovereign wealth fund 1MDB.
Tesla's (TSLA), an electric vehicle manufacturer, credit rating was upgraded to "B2" from "B3" at Moody's, outlook "Stable". The rating agency said: "The upgrade reflects Tesla's sustainable position in the auto industry as a specialized producer of pure battery electric vehicles (BEVs)." Separately, the stock was downgraded to "neutral" from "outperform" at Daiwa.
Twitter's (TWTR), the social network, price target was raised to 36 dollars from 25 dollars at UBS.
Honeywell (HON), a diversified technology company, reported second quarter adjusted EPS down to 1.26 dollar from 2.10 dollars a year earlier, on sales down 19% to 7.48 billion dollars. Both figures beat estimates.
American Express (AXP), a globally integrated payments company, unveiled second quarter sales down 29% to 7.7 billion dollars, below estimates. EPS was down to 0.29 dollar from 2.07 dollars a year earlier.
Schlumberger (SLB), the world's largest supplier of oil and gas products and services, posted second quarter adjusted EPS down to 0.05 dollar, above estimates, from 0.35 dollar a year earlier, on sales down 35% to 5.4 billion dollars, in-line with expectations.
E*Trade (ETFC), an online brokerage service, announced second quarter EPS of 0.88 dollar, better than expected, down from 0.90 dollar a year ago.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?


USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.