




Alibaba Q4 Earnings Preview
The company’s outlook moving forward will be the biggest driver for the stock...
Share this:
Chinese e-commerce giant Alibaba (BABA) reports its Q4 earnings tomorrow morning before the bell, and no matter how you look at it, the fourth quarter was a big one for the company.
In the last three months of the year, Alibaba raised $13B in a secondary listing in Hong Kong, closed at a fresh record high above $210, and set a new record with $38.4B in sales on Singles Day alone. For Americans tracking at home, that’s more than US consumers spent online on Thanksgiving Day, Black Friday, Cyber Monday, and Amazon Prime Day…combined!
In other words, the company’s outlook was looking bright in Q4, and the market has set correspondingly high expectations heading into tomorrow’s earnings release. According to FactSet, analysts are expecting BABA to report $2.27 in EPS (up from $1.82 in Q4 last year) on $22.7B in revenue (up from $17.5B last year). 54 of the 56 analysts tracked by FactSet have “buy” ratings on the stock, with the other two analysts maintaining “hold” ratings, and an overall price target of $242 over the next 12 months.
While the outlook through Q4 was undoubtedly bright, the biggest question on traders’ minds will be around how the outbreak of coronavirus has impacted consumer demand in China. This information will not be in the backward-looking reported figures, but management’s guidance for the year will give insight into the expected scale of the disruption to consumer demand, manufacturing production, and labor delivery. In other words, the company’s outlook moving forward will be the biggest driver for the stock.
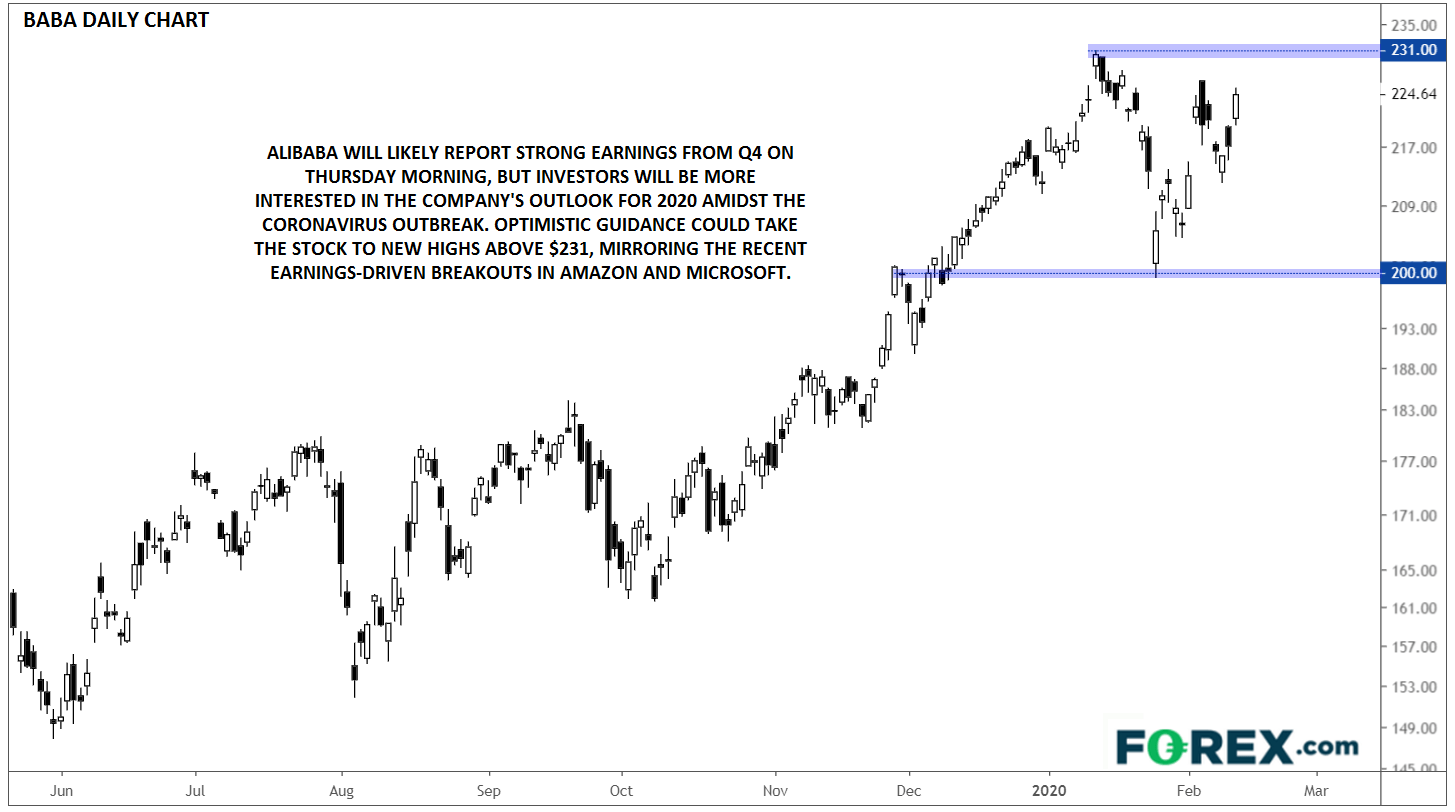
Technically speaking, BABA remains in a clear uptrend, recovering relatively quickly from the nearly 15% late-January swoon to trade back above $220. A strong report, with solid guidance for the year ahead, would likely take the stock to fresh record highs above $231; this would mirror the recent earnings-driven breakouts in massive US technology names like Amazon and Microsoft. On the other hand, a disappointing earnings report and acknowledgement that coronavirus is likely to lead to major disruptions throughout the year could take the stock back down toward the psychologically-significant $200 level, which has served as both resistance and support in recent months.
Source: TradingView, GAIN Capital
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.
S&P 500, Nasdaq 100 Forecast for the Week Ahead
A hawkish Fed and 10-Year Notes on the verge of a push above 5%, yet stocks have so far shrugged off that fear. But can it continue?

Hang Seng Tech rout nears make-or-break zone
The technical damage is clear, but with Hang Seng Tech now deeply stretched and approaching major support, the risk-reward is becoming more two-sided.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.