




Another Dead Cat Bounce On FTSE
FTSE rebounding after 10% sell off on Thursday. Can it hold?
Share this:
Coronavirus panic selling hit stocks and asset classes across the board on Thursday. The FTSE closed down over 10%, the DAX 12% and US stock indices ended the session 9-10% lower. Ironically on Friday 13th, Black Friday, things are looking up (at least momentarily)
Fed tried, more to come?
After a wild week on the markets hopes of a Fed stimulus package are boosting stocks in early trade on Friday. Europe has opened on the front foot and US futures are pointing higher. The turnaround comes as central banks from US to Australia pump liquidity in the financial markets and as investors become hopeful that US Democrats and Republicans could pass a stimulus package on Friday. Washington may be late to the party, but they are still more than welcome.
After a wild week on the markets hopes of a Fed stimulus package are boosting stocks in early trade on Friday. Europe has opened on the front foot and US futures are pointing higher. The turnaround comes as central banks from US to Australia pump liquidity in the financial markets and as investors become hopeful that US Democrats and Republicans could pass a stimulus package on Friday. Washington may be late to the party, but they are still more than welcome.
So far, US Government bureaucracy has not kept up with the nature of the coronavirus outbreak and market needs and expectations. The Fed did its best last night with a three-day $1.5 trillion liquidity injection into the markets. There are hopes for another rate cut and QE when the FOMC meets next week.
Light at the end of a tunnel (which we are just entering)
After stocks experienced the worst sell of since Black Monday over 3 decades ago, there is a sense that the market has more than priced in the negative impact that coronavirus headwinds could bring. Let’s not forget that China has recorded the lowest level of infections with just 8 new confirmed cases. This proves that with containment measures such as lock down, strict quarantine and travel restriction it is possible for a country to rebound and relatively quickly. China has sent a specialist team to Italy to help get control over the outbreak. There is light at the end of the coronavirus tunnel, which in Europe and US we are just entering.
After stocks experienced the worst sell of since Black Monday over 3 decades ago, there is a sense that the market has more than priced in the negative impact that coronavirus headwinds could bring. Let’s not forget that China has recorded the lowest level of infections with just 8 new confirmed cases. This proves that with containment measures such as lock down, strict quarantine and travel restriction it is possible for a country to rebound and relatively quickly. China has sent a specialist team to Italy to help get control over the outbreak. There is light at the end of the coronavirus tunnel, which in Europe and US we are just entering.
FTSE levels to watch
However, the chart is not quite so convincing. Any stronger starts that we have seen this week have not been sustained into the afternoons so there is plenty of caution on trading floors this morning.
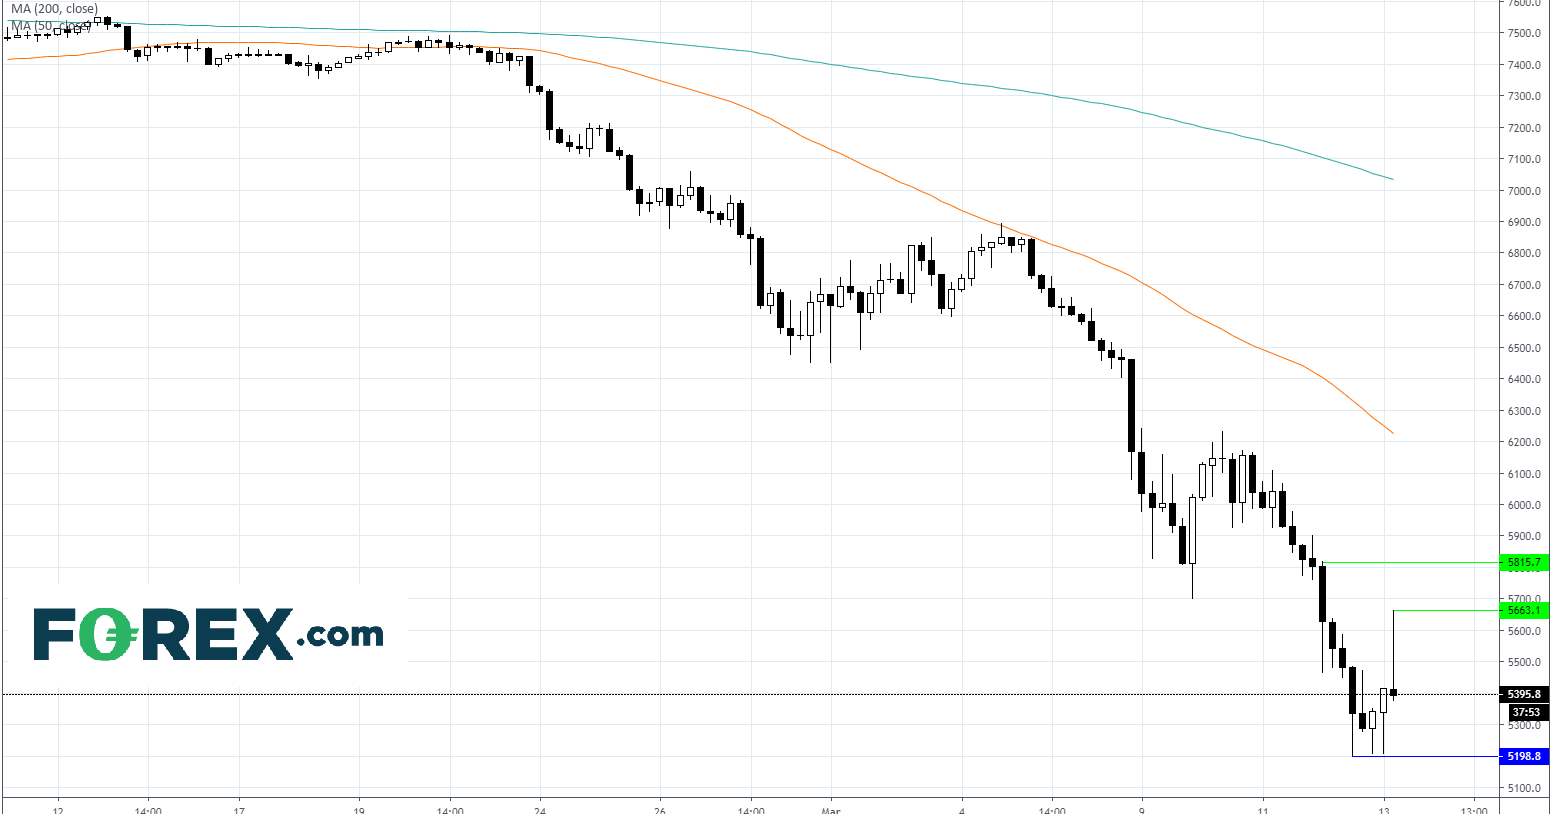
The FTSE is up 2% after initial opening volatility at 5345. The 4-hour chart shows a bearish chart. However, strong support can be seen at 5202/7 (low from today and yesterday) This level was also a solid support in May and June 2012 . This is an important level to note. Further support is seen at 5070 (low Nov’11)
Resistance can be seen at 5663, today’s high and 5815 (Monday’s high).
Coronavirus panic selling hit stocks and asset classes across the board on Thursday. The FTSE closed down over 10%, the DAX 12% and US stock indices ended the session 9-10% lower. Ironically on Friday 13th, Black Friday, things are looking up (at least momentarily)
Fed tried, more to come?
After a wild week on the markets hopes of a Fed stimulus package are boosting stocks in early trade on Friday. Europe has opened on the front foot and US futures are pointing higher. The turnaround comes as central banks from US to Australia pump liquidity in the financial markets and as investors become hopeful that US Democrats and Republicans could pass a stimulus package on Friday. Washington may be late to the party, but they are still more than welcome.
After a wild week on the markets hopes of a Fed stimulus package are boosting stocks in early trade on Friday. Europe has opened on the front foot and US futures are pointing higher. The turnaround comes as central banks from US to Australia pump liquidity in the financial markets and as investors become hopeful that US Democrats and Republicans could pass a stimulus package on Friday. Washington may be late to the party, but they are still more than welcome.
So far, US Government bureaucracy has not kept up with the nature of the coronavirus outbreak and market needs and expectations. The Fed did its best last night with a three-day $1.5 trillion liquidity injection into the markets. There are hopes for another rate cut and QE when the FOMC meets next week.
Light at the end of a tunnel (which we are just entering)
After stocks experienced the worst sell of since Black Monday over 3 decades ago, there is a sense that the market has more than priced in the negative impact that coronavirus headwinds could bring. Let’s not forget that China has recorded the lowest level of infections with just 8 new confirmed cases. This proves that with containment measures such as lock down, strict quarantine and travel restriction it is possible for a country to rebound and relatively quickly. China has sent a specialist team to Italy to help get control over the outbreak. There is light at the end of the coronavirus tunnel, which in Europe and US we are just entering.
After stocks experienced the worst sell of since Black Monday over 3 decades ago, there is a sense that the market has more than priced in the negative impact that coronavirus headwinds could bring. Let’s not forget that China has recorded the lowest level of infections with just 8 new confirmed cases. This proves that with containment measures such as lock down, strict quarantine and travel restriction it is possible for a country to rebound and relatively quickly. China has sent a specialist team to Italy to help get control over the outbreak. There is light at the end of the coronavirus tunnel, which in Europe and US we are just entering.
FTSE levels to watch
However, the chart is not quite so convincing. Any stronger starts that we have seen this week have not been sustained into the afternoons so there is plenty of caution on trading floors this morning.
The FTSE is up 2% after initial opening volatility at 5345. The 4-hour chart shows a bearish chart. However, strong support can be seen at 5202/7 (low from today and yesterday) This level was also a solid support in May and June 2012 . This is an important level to note. Further support is seen at 5070 (low Nov’11)
Resistance can be seen at 5663, today’s high and 5815 (Monday’s high).
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FTSE 100 and GBP/USD forecast: UK data gives BoE March cut a further boost
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling.
FTSE 100 forecast - Indices weekend outlook | February 16, 2026
With the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
Indices weekly outlook: FTSE holds steady ahead of UK data after tech volatility
Last week saw the technology sector take a plunge, before dip buyers stepped in on Friday to save the day, helping to fuel a late rally on Wall Street. In Europe, the major indices also came off their earlier lows to close either flat or in the positive. In the week ahead, the global macro calendar is lighter, with US market closed on Tuesday in observance of Veterans Day.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.