



FTSE 100 forecast - Indices weekend outlook | February 16, 2026
With the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
Share this:
the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
The week that was
It was a pretty choppy week for the major indices last week, with US tech weakness being the highlight but overall nothing too significant to report with major indices holding key support levels. A strong US jobs report was followed by US inflation data coming in weaker than expected at 2.4% year-on-year, falling relatively sharply from the previous month’s 2.7% reading.
That soft inflation print has pushed markets to start pricing in more aggressive Fed easing, again, with traders seeing around a 30% chance of a rate cut by April, and more than an 80% chance of easing by June.
Meanwhile, the FTSE 100 continued to trade near record highs as expectations for Bank of England rate cuts increased thanks to some further signs of weakness in the UK economy, while the resulting weakness in the pound also helped the cause. The UK economy certainly ended 2025 on a fairly weak note. Construction and business investment were particularly soft, which highlights ongoing growth concerns. However, this wasn’t really new information for the Bank of England. Policymakers already knew the economy was slowing, which explains why the pound didn’t sell off aggressively after the data. That said, the pound remains fundamentally fragile, especially against commodity dollars like the Aussie or kiwi.
FTSE 100 forecast: Looking ahead to the new week
Looking ahead, we’ve got plenty of market-moving data coming up. In the UK, we get wages data on Tuesday and CPI on Wednesday – both crucial for shaping expectations around future BoE rate cuts, putting the FTSE 100 forecast into focus. Among other data highlights, we’ll see global PMIs, followed by US GDP and core PCE inflation, the Fed’s preferred inflation measure, all on Friday.
Top 10 Company Earnings This Week
The results of UK companies will undoubtedly impact the FTSE 100 forecast in the week ahead. But it is not just UK companies reporting. Looking at the broader market, we have some interesting earnings coming up from other major markets too.
Here’s the top 10 list of U.S. & European companies reporting earnings in the week ahead:
Tuesday, Feb 10
1. BP
2. AstraZeneca
3. Barclays
4. S&P Global
5. The Coca-Cola Company
6. Robinhood Markets
Wednesday, Feb 11
7. Cisco Systems
8. McDonald’s
Thursday, Feb 12
9. Unilever
10. Anheuser-Busch InBev
What are the key data highlights this week?
Monday, Feb 9
- Japan GDP
- Eurozone industrial production
Tuesday, Feb 10
- UK Jobless claims, average earnings index and employment data
- German ZEW Economic Sentiment
- Canadian CPI
- US Empire State Manufacturing Index
Wednesday, Feb 11
- RBNZ interest rate decision - no change expected
- UK CPI - expected to ease to 3.0% from 3.4%
- US durable goods orders, housing starts, building permits and FOMC minutes
Thursday, Feb 12
- Australia employment data
- US Jobless Claims, Philly Fed Manufacturing Index and Pending Home Sales
Friday, Feb 13
- Global PMIs
- UK retail sales
- Canada retail sales
- US Advance GDP, Core PCE Price Index and New Home Sales
FTSE 100 Key levels
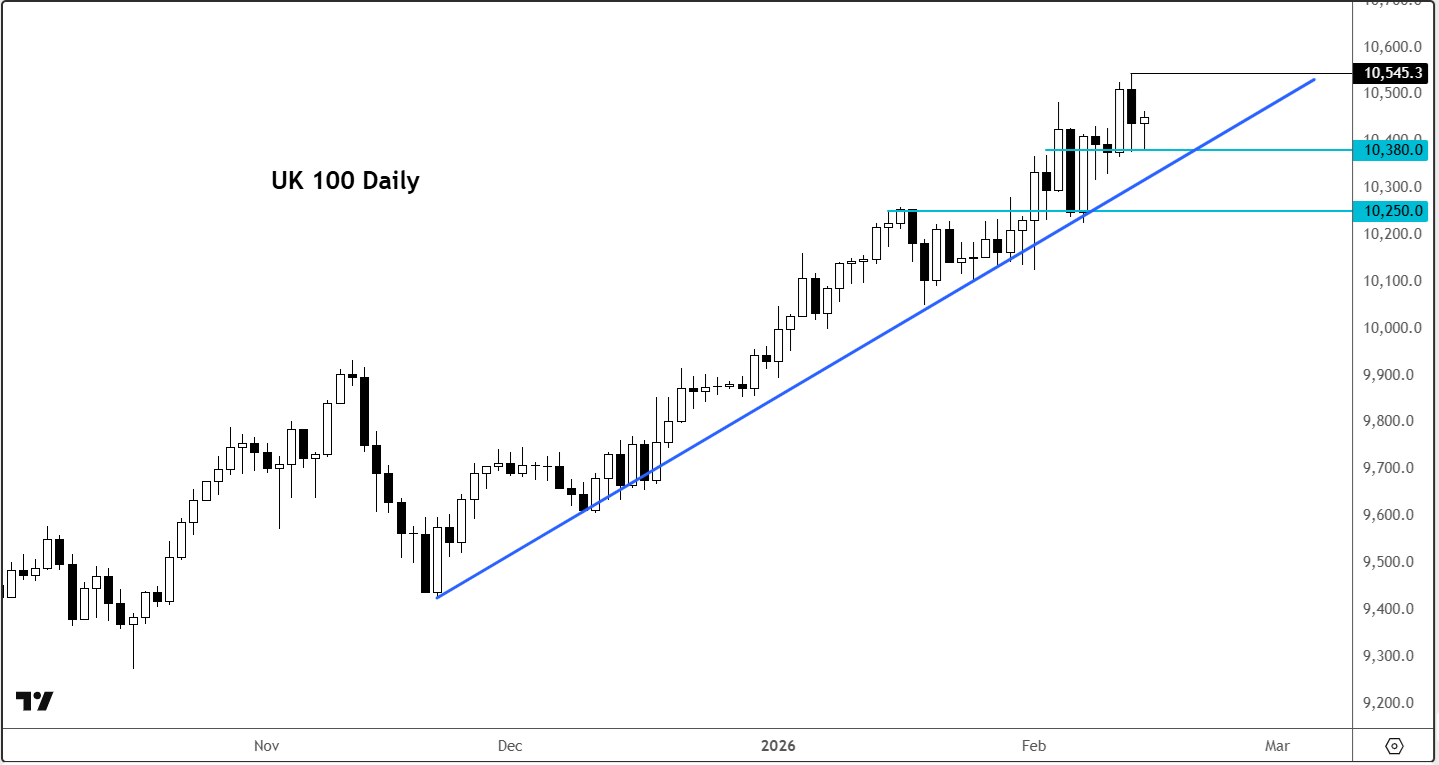
Aggressive recent dip buying means we don’t have to look too far below to identify key short term levels, unless an unexpected stimulus drives markets sharply lower. Among support levels to watch, 10,400 is important, below which 10,375 comes into focus next, followed by 10,300 and 10,280. Resistance is in short supply, with the exception of 10,480ish - above which is the all time high at 10,545.


What about the pound?
Everything you need to know in this video:
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.
Nasdaq Sell-Off Exposes the Hidden Gap in AI Profits
The Nasdaq sell-off deepened as doubts over AI spending, weak chip earnings and the threat of tighter AI regulation hit U.S. tech stocks.
Nikkei 225 bear market deepens as volatility surges
The Nikkei has entered a technical bear market following a historic plunge. RSI and ATR stretch readings suggest a bounce may be coming, but history carries a warning for dip buyers.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.