


FTSE 100 and GBP/USD forecast: UK data gives BoE March cut a further boost
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling.
Share this:
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling. Looking at the broader markets, it has been a choppy affair the last week and a bit. This week has started quietly with US markets closed on Monday for Presidents’ Day and China effectively offline for the whole week thanks to the Spring Festival there. But things should become a bit lively as it’s shaping up to be a busy few days on the earnings front, with plenty of results due from the UK, Europe and the US. On top of that, we’ve got a steady stream of key economic data from both sides of the Atlantic, which means interest rate expectations are likely to remain a dominant theme once again.
What to make of today’s UK data?
Sterling slipped across the board while the FTSE 100 edged up 0.4% following the release of the latest UK labour market data, reflecting growing expectations that interest rate cuts are becoming more likely, as a softer jobs market continues to take the heat out of wage growth.
The three-month annual rate of average earnings slowed to 4.2% in December, down from 4.6% in November and well below the 5.9% seen a year earlier. That trend was echoed in the private sector too, where pay growth excluding bonuses eased from 3.6% to 3.4%. This is a big comedown from the 6.2% pace recorded last year.
Diving deeper into the data, it looks like most of the weakness remains concentrated in consumer-facing sectors, particularly hospitality, retail and leisure, possibly as a result of the after-effects of last year’s higher National Insurance and minimum wage costs. Elsewhere, the picture is less alarming. Private-sector employment is edging down only marginally, redundancies remain contained, and vacancies have stabilised.
In short, wage pressures – one of the key sticking points for the MPC – are clearly cooling. And that’s strengthening the case for further easing from the BoE with the UK central bank likely to move in March now instead of waiting until April. Traders are now pricing in a 76% chance of a March cut while odds of two cuts are now fully priced in by November, up from about 48 basis points earlier. But I think we could see that second cut as early as June. As such, this should keep the FTSE 100 forecast positive.
What about the FX markets?
It’s been a fairly subdued start to the week in FX, following a mildly bearish stretch for the US dollar last week. Despite a stronger-than-expected US jobs report, the greenback struggled to hold onto gains after Friday’s softer inflation data, which reinforced expectations that the Federal Reserve is still edging closer to rate cuts. That weakness helped to cushion the pound, even though UK data hasn’t exactly inspired confidence. The UK economy ended 2025 on a soft note, with construction and business investment under pressure, and a recent dovish hold from the Bank of England has kept sterling on the back foot against most majors. Today’s weaker wages data has further weighed on pound crosses, mostly notably the GBP/JPY with the yen again outperforming.
Looking ahead: plenty of more data this week
Speaking of inflation, CPI is expected tomorrow and it will also be closely watched for clues on how soon and how aggressively the BoE might start cutting rates. Headline CPI is seen easing to 3.0% year-over-year, down from 3.4% in December.
Elsewhere, we’ll see a batch of global PMI figures on Friday, along with UK retail sales. Actually, Friday is also heavy on US data with GDP and core PCE inflation – the Fed’s preferred inflation gauge – both on the calendar. In short, rate expectations are unlikely to drift too far from centre stage, keeping the GBP/USD forecast in neutral territory.
GBP/USD forecast: Key levels to watch
Despite the pound generally weakening elsewhere, the resilience in GBP/USD looks more like dollar weakness than genuine pound strength. Otherwise, the pair should be trading much lower given UK data weakness. Technically, support around the 1.3500–1.3565 zone remains key, with a break lower opening the door towards the 200-day average near 1.3400. On the upside, resistance sits around 1.3700 and 1.3800.
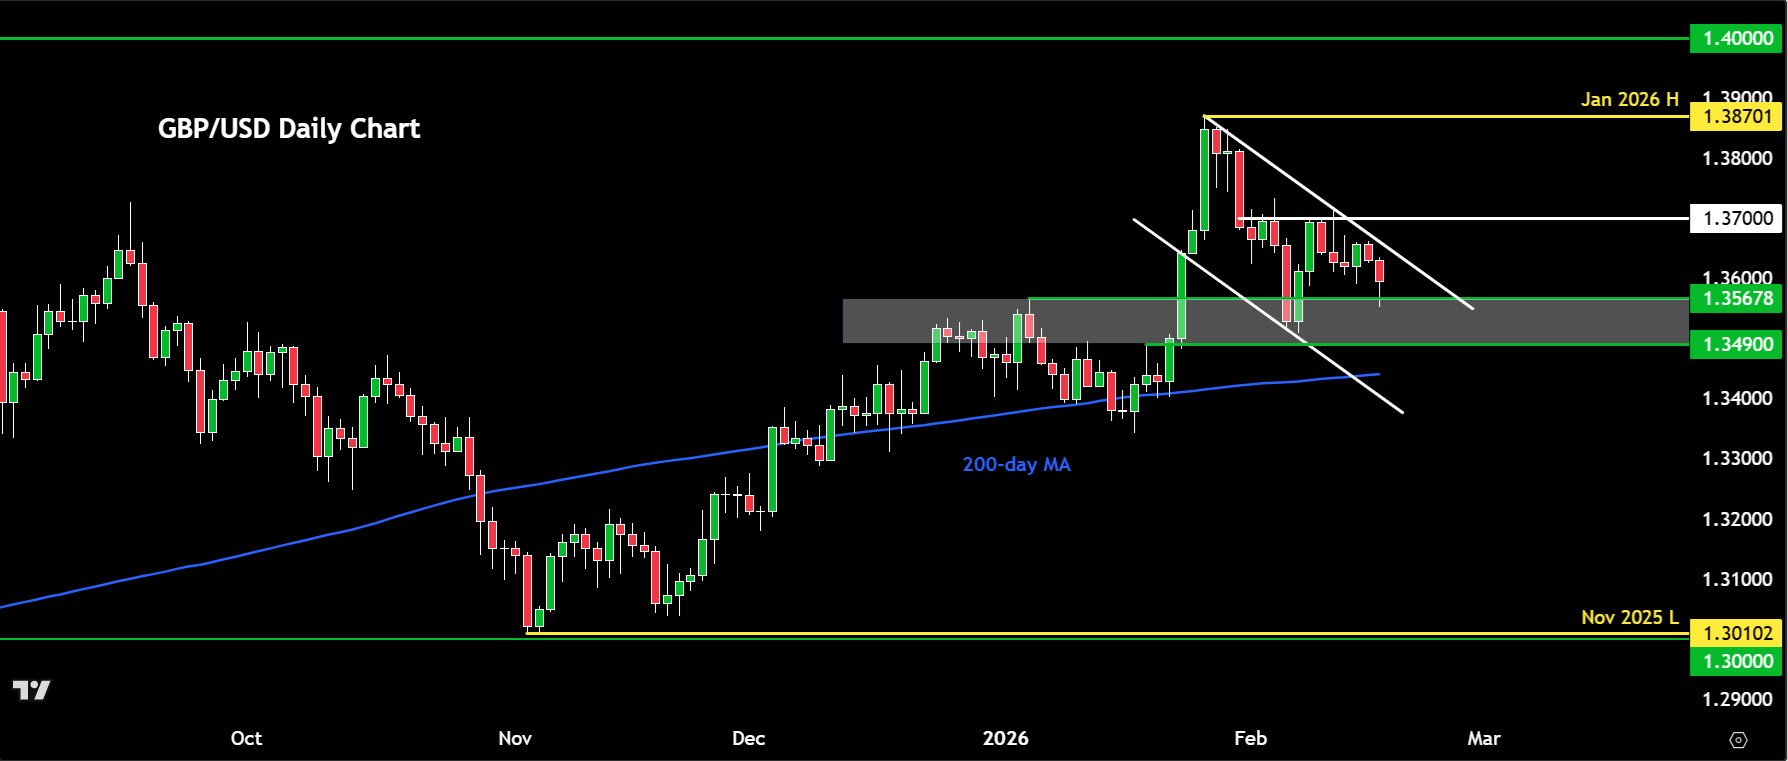
Looking ahead, UK inflation data will be crucial in shaping expectations for the next BoE move, while global PMIs and US GDP should drive broader dollar sentiment. Ultimately, unless US data surprises positively, the bias for the GBP to USD forecast is somewhat neutral given the recent dollar weakness.


FTSE 100 technical analysis and key levels
From a technical point of view, the aggressive dip-buying we’ve seen recently means key support levels are still relatively close by. The 10,400 – 10,375 area looks important in the short term. Below that, 10,250 comes into focus, followed by 10,000.
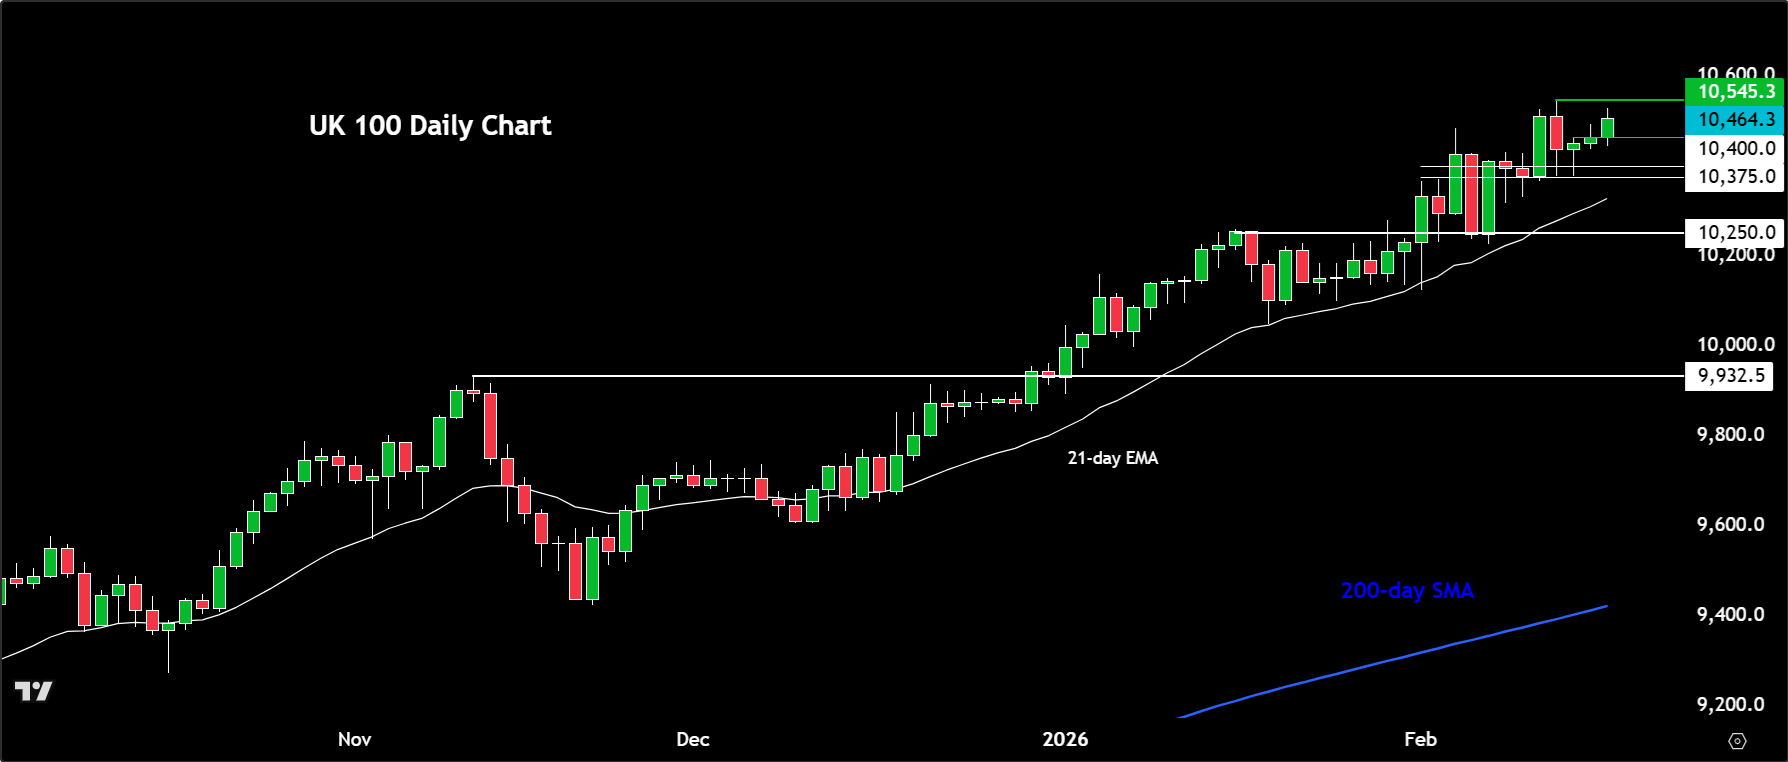
On the upside, resistance remains fairly thin. The first real hurdle sits around the 10,500 region, and beyond that the all-time high at 10,545 is the obvious level to watch. As long as broader sentiment remains stable, the path of least resistance still appears to be higher.
Company News
Shares in housebuilders Persimmon and Berkeley rose as the outlook for mortgage affordability benefited from hopes of a March rate cut. Elsewhere, Antofagasta shares dropped on the back of its earnings results.


Source for all charts used in this article: TradingView.com
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.
Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.


USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.