



Another Step Higher Following Wall Streets Impressive Gains
The lifting of coronavirus lockdown and hopes of a quick recovery are feeding trader optimism, although the lack of fresh catalysts is seeing that optimism start to fade.
Share this:

After another phenomenal rally on Wall Street, which saw the Nasdaq strike a fresh all time high and the S&P come close to wiping out all its losses for the year, Asian markets traded mixed. The lifting of coronavirus lockdown and hopes of a quick recovery are feeding trader optimism, although the lack of fresh catalysts is seeing that optimism start to fade.
European markets are pointing to a quieter start as investors take stock of recent gains, particularly in light of the poor economic conditions, and tread water ahead of tomorrow’s FOMC. There is little doubt that the central bank’s accommodative stance and obliging manners has helped propel stocks to there current levels. Any sense that the Fed could be less accommodative could threaten a repeat performance of 2013’s taper tantrum.
Glass half full
Whilst recent data has shown a stark improvement from April’s bottom, the numbers still paint a grim picture. Yet traders are showing that they are more than prepared to see the economy in a glass half full manner. The jobs report is a good example. Traders focused on the 2.5 million jobs created rather than the 20 million jobs that have been lost.
Whilst recent data has shown a stark improvement from April’s bottom, the numbers still paint a grim picture. Yet traders are showing that they are more than prepared to see the economy in a glass half full manner. The jobs report is a good example. Traders focused on the 2.5 million jobs created rather than the 20 million jobs that have been lost.
BRC retail sales improving
BRC retail sales data here in the UK also added to mounting evidence that the economy was on the right track, with sales -5.9% in May compared to a year earlier. This was a vast improvement of April’s -19.1% drop giving optimistic traders reason to cheer. However, it was still the second worst reading since records began in 1995. After 8 straight days of gains the Pound is mildly lower versus the USD. That said it still remains close to three month tops above $1.27.
BRC retail sales data here in the UK also added to mounting evidence that the economy was on the right track, with sales -5.9% in May compared to a year earlier. This was a vast improvement of April’s -19.1% drop giving optimistic traders reason to cheer. However, it was still the second worst reading since records began in 1995. After 8 straight days of gains the Pound is mildly lower versus the USD. That said it still remains close to three month tops above $1.27.
Eurozone data in focus
A slew of data is due from the Eurozone. German exports were considerably worse than forecast -24% vs -15.6% expected. Imports -16.5% vs -16%. The Dax has barely acknowledged the data whilst the Euro continues to show resilience against the slightly stronger US Dollar.
Eurozone unemployment and GDP figures are also due shortly.
Oil clawing back losses
Oil is attempting to claw back loses after falling sharply in the previous session after Saudi Arabia, Kuwait and United Arab Emirates confirmed that they would not extend an additional 1.18 million bpd in cuts on top of the OPEC+ cuts in July. The disappointment resulted in WTI and Brent shedding over 5%.
Today, oil is back on the rise as easing of coronavirus lockdown measures boost hopes that a recovery in demand will do some of the heavy lifting. Brent is sitting comfortably over $40 and the expectation, particularly now that New York is reopening, is that WTI will be back there soon.
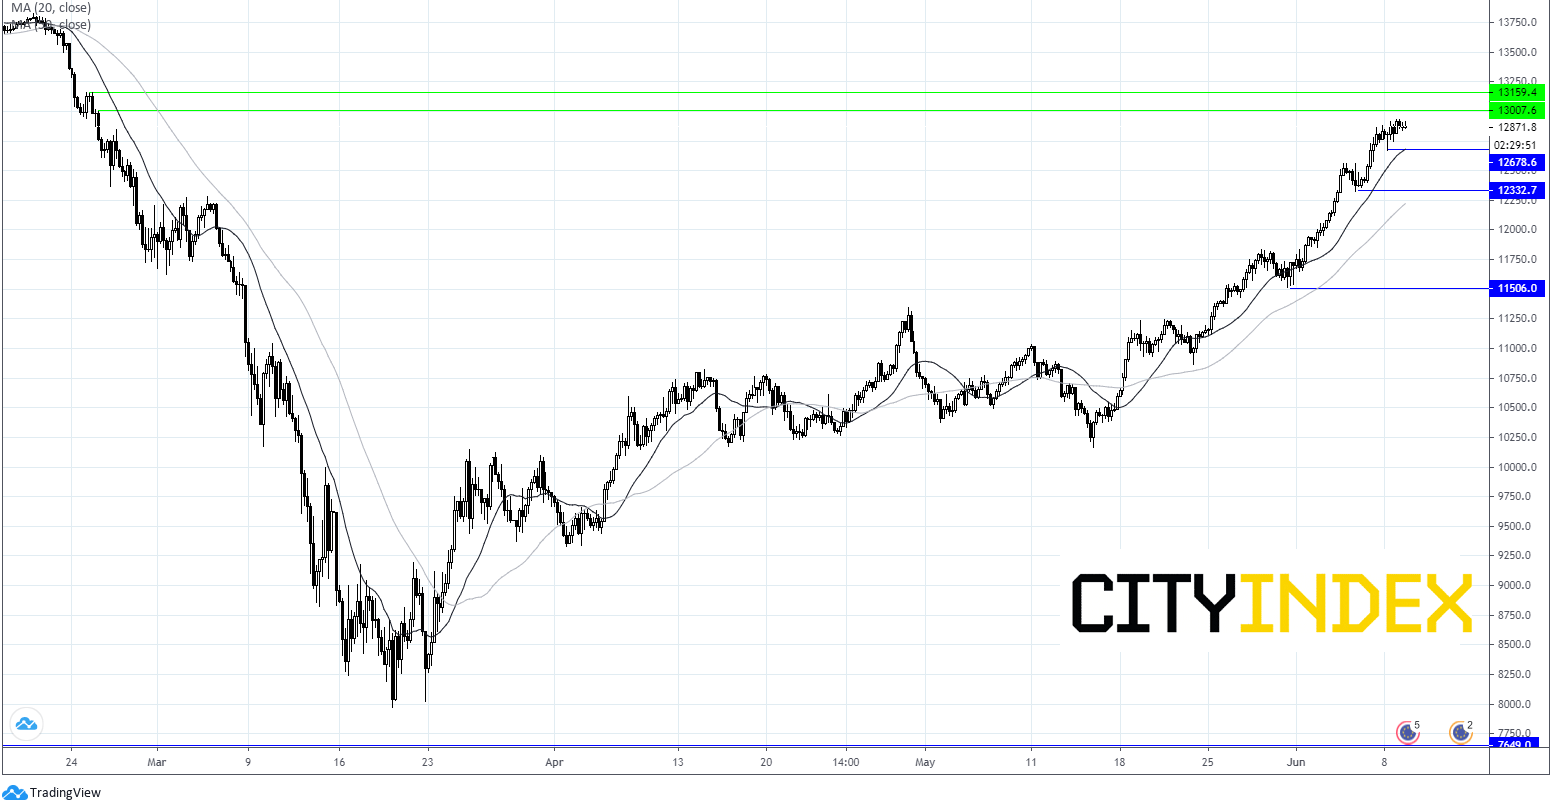
Dax chart
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.