



ASX200 Afternoon Report June 8th 2022
The ASX200 is trading 21 points higher at 7116 at 3.00 pm Sydney time. A mute rebound after its post RBA thumping yesterday.
Share this:
The ASX200 is trading 21 points higher at 7116 at 3.00 pm Sydney time. A mute rebound after its post RBA thumping yesterday.
While the RBA's forward guidance that accompanied its supersized 50bp rate hike wasn't as clear as its central bank peers, the door is open for a follow up inflation-busting 50bp hike next month and for the RBA's official cash rate to end at 2% by year-end.
The start of a more aggressive RBA hiking cycle on the same day that the ANZ- Roy Morgan Consumer Confidence fell to its lowest level since 2020 on cost-of-living concerns has the potential to become a polar vortex for the ASX200.
The decline in consumer sentiment is set to deepen after a deluge of negative reports this week around higher gas and electricity bills, softening housing prices, and higher mortgage repayments.
The strain of the RBA's more aggressive rate hike cycle has been felt by the Financials. While higher rates will allow the big banks to pass on higher margins, it will weigh on demand for mortgages, lead to greater recession risk and a weaker housing market.
Westpac (WBC) has fallen by 5.5% to $22.12 as it became the first bank to pass on yesterday's rate rise. Commonwealth Bank (CBA) fell 4% to $97.83, National Australia Bank (NAB) fell 3.89% to $28.92. ANZ fell 2.58% to $23.82. Macquarie (MQG) bucked the trend lifting 1.2% to $179.62.
The energy sector is the best performing sector today as crude oil holds around $120 p/b on tight supply and increased demand coming from the re-opening in China and the start of the driving season in the U.S.
Woodside (WDS) has lifted by 3.1% to $33.91, Santos (STO) added 2.9% to $8.72, Origin Energy (ORG) added 1.9% to $6.29, AGL added 1.7% to $8.87, and Beach Energy (BPT) added 1.5% to $1.87.
Gains also for the Industrials as Atlas Arteria (ALX) surged over 16% following news that fund manager IFM had taken a 15% stake in the company. Boral (BOR) lifted by 14% to $3.26 after naming a new CEO. Elsewhere Transurban (TCL) added 2.1% to $14.37. Seven Group Holdings (SVW) added 1.9% to $19.16, and Qantas (QAN) lifted by 1.5% to $5.41.
A fall in U.S yields overnight has helped the IT sector snap a two-day losing streak. Block (SQ2) added 3.45% to $116.47, Wisetech Global (WTC) added 2.8% to $40.84, Xero (XRO) added 2.4% to $82.14, and Life 360 (360) added 1.9% to $3.18. Elsewhere, heavy falls for Sezzle (SZL) and ZIP dropping 11.96% and 5.34%, respectively, after yesterday's announcement by Apple that it's entering the BNPL space.
Robust iron ore and coal prices have provided support for the Materials sector. Of the iron ore miners BHP Group (BHP) added 2.5% to $47.43, Rio Tinto (RIO) added 2% to $118.89. Fortescue Metals (FMG) added 1.8% to $21.54. Coal miner Yancoal (YAL) added 5.65% to $5.99, Coronado Coal (CRN) added 3.14% to $2.14. Whitehaven Coal (WHC) added 1.66% to $5.51.
The roller coast ride in the Lithium space continues. Vulcan Energy (VUL) fell 4.1% to $6.90, Galan Lithium (GLN) fell 1.56% to $1.27, Allkem (AKE) fell 1.32% to $11.62, and Pilbara Minerals (PLS) fell 1.65% to $2.39.
Finally, Paladin Energy (PDN) has lifted by 12.8% on news the U.S is seeking to move away from Russian uranium supply.
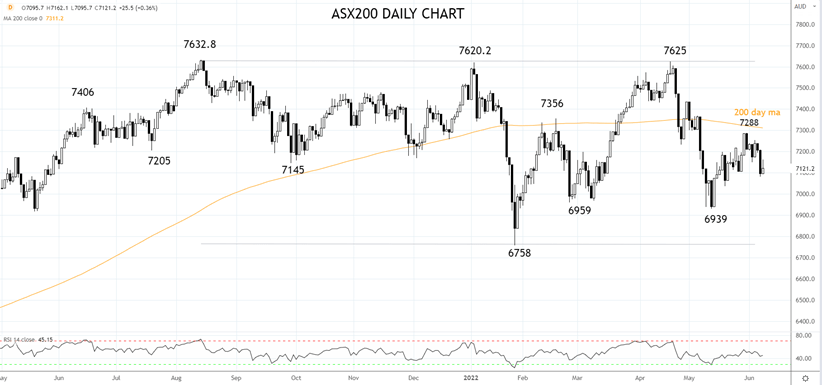
The expectation of a more aggressive RBA hiking cycle into slowing growth/sentiment is a negative for the ASX200. After rejecting the resistance coming from the 200-day moving average last week near 7300, yesterday's break of support at 7100 indicates that the ASX200 will test the bottom of its nine-month range 6950/6750 area in the coming weeks.
Source Tradingview. The figures stated are as of June 8th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 is trading 21 points higher at 7116 at 3.00 pm Sydney time. A mute rebound after its post RBA thumping yesterday.
While the RBA's forward guidance that accompanied its supersized 50bp rate hike wasn't as clear as its central bank peers, the door is open for a follow up inflation-busting 50bp hike next month and for the RBA's official cash rate to end at 2% by year-end.
The start of a more aggressive RBA hiking cycle on the same day that the ANZ- Roy Morgan Consumer Confidence fell to its lowest level since 2020 on cost-of-living concerns has the potential to become a polar vortex for the ASX200.
The decline in consumer sentiment is set to deepen after a deluge of negative reports this week around higher gas and electricity bills, softening housing prices, and higher mortgage repayments.
The strain of the RBA's more aggressive rate hike cycle has been felt by the Financials. While higher rates will allow the big banks to pass on higher margins, it will weigh on demand for mortgages, lead to greater recession risk and a weaker housing market.
Westpac (WBC) has fallen by 5.5% to $22.12 as it became the first bank to pass on yesterday's rate rise. Commonwealth Bank (CBA) fell 4% to $97.83, National Australia Bank (NAB) fell 3.89% to $28.92. ANZ fell 2.58% to $23.82. Macquarie (MQG) bucked the trend lifting 1.2% to $179.62.
The energy sector is the best performing sector today as crude oil holds around $120 p/b on tight supply and increased demand coming from the re-opening in China and the start of the driving season in the U.S.
Woodside (WDS) has lifted by 3.1% to $33.91, Santos (STO) added 2.9% to $8.72, Origin Energy (ORG) added 1.9% to $6.29, AGL added 1.7% to $8.87, and Beach Energy (BPT) added 1.5% to $1.87.
Gains also for the Industrials as Atlas Arteria (ALX) surged over 16% following news that fund manager IFM had taken a 15% stake in the company. Boral (BOR) lifted by 14% to $3.26 after naming a new CEO. Elsewhere Transurban (TCL) added 2.1% to $14.37. Seven Group Holdings (SVW) added 1.9% to $19.16, and Qantas (QAN) lifted by 1.5% to $5.41.
A fall in U.S yields overnight has helped the IT sector snap a two-day losing streak. Block (SQ2) added 3.45% to $116.47, Wisetech Global (WTC) added 2.8% to $40.84, Xero (XRO) added 2.4% to $82.14, and Life 360 (360) added 1.9% to $3.18. Elsewhere, heavy falls for Sezzle (SZL) and ZIP dropping 11.96% and 5.34%, respectively, after yesterday's announcement by Apple that it's entering the BNPL space.
Robust iron ore and coal prices have provided support for the Materials sector. Of the iron ore miners BHP Group (BHP) added 2.5% to $47.43, Rio Tinto (RIO) added 2% to $118.89. Fortescue Metals (FMG) added 1.8% to $21.54. Coal miner Yancoal (YAL) added 5.65% to $5.99, Coronado Coal (CRN) added 3.14% to $2.14. Whitehaven Coal (WHC) added 1.66% to $5.51.
The roller coast ride in the Lithium space continues. Vulcan Energy (VUL) fell 4.1% to $6.90, Galan Lithium (GLN) fell 1.56% to $1.27, Allkem (AKE) fell 1.32% to $11.62, and Pilbara Minerals (PLS) fell 1.65% to $2.39.
Finally, Paladin Energy (PDN) has lifted by 12.8% on news the U.S is seeking to move away from Russian uranium supply.
The expectation of a more aggressive RBA hiking cycle into slowing growth/sentiment is a negative for the ASX200. After rejecting the resistance coming from the 200-day moving average last week near 7300, yesterday's break of support at 7100 indicates that the ASX200 will test the bottom of its nine-month range 6950/6750 area in the coming weeks.
Source Tradingview. The figures stated are as of June 8th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?


USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.