






BOC Optimism and Firmer WTI Boosts CAD
BOC held rates as expected, although their statement was optimistic enough to send the Canadian dollar sharply higher.
Share this:

BOC held rates as expected, although their statement was optimistic enough to send the Canadian dollar sharply higher.
The statement was indeed one of optimism, although not hawkish as there is clearly no bias to raise rates. But with a relatively high OCR of 1.75%, it leaves BOC vulnerable to easing in 2020 if data turns against their forecasts. Particularly if trade talks sour. Going forward, we’ll be keeping a close eye on consumer spending and housing activity as they’ll likely hold the key as to whether they’ll remain neutral or seek to ease in future.
Summary of BOC statement:
- Maintained OCT at 1.75%
- Evidence that the global economy is stabilizing
- Growth slowed as expected, but still expected to edge higher over the next couple of years
- Housing investment, population growth, low mortgage rates and consumer spending (via higher wages) was a source of strength
- Investment spending unexpectedly slowed; we’ll continue to monitor its momentum
- CPI remains on target, and we expect it to track close to 2% over the next 2 years
- Future rate decision guided by adverse impact of conflicts against resilience of Canada’s economy (most notably consumer spending and housing activity)
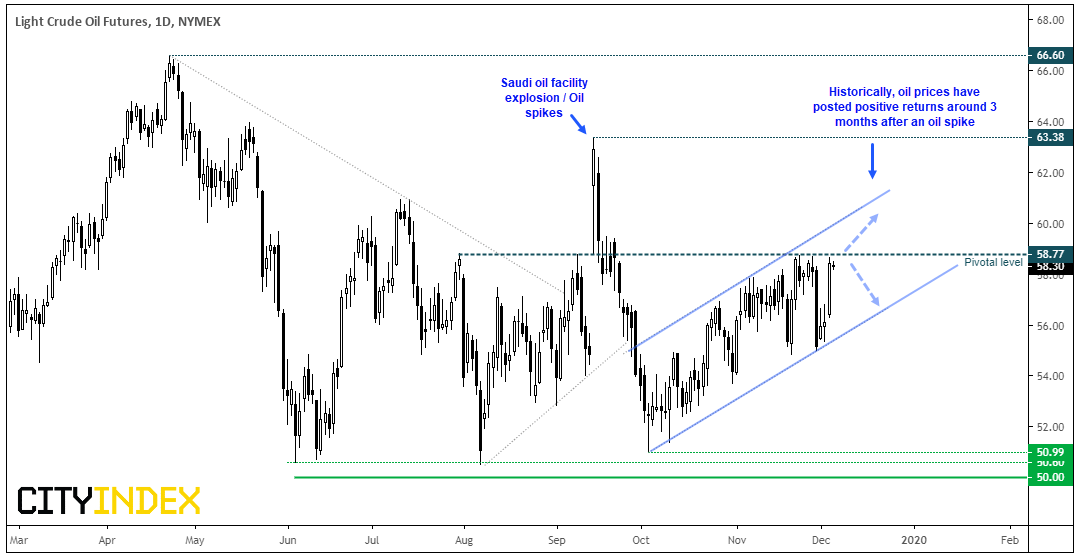
Whilst the positive outlook was clearly a major factor in CAD strength, firmer oil prices also played a part too after a surprise inventory drawdown. WTI enjoyed its most bullish session since September’s oil spike and, if forward returns are to be believed, we could see oil prices rally in mid-December as historically they have rebounded 3-months after an price spike.
Technically, WTI sits just below 58.77 resistance within a bullish channel. It’s clearly a pivotal level as it has acted as both support and resistance in recent months, so with prices stalling beneath it, bears could be tempted to fade into move (at least over the near-term). Yet if prices break above 58.77 we’re in a new range and this could likely further support CAD strength.
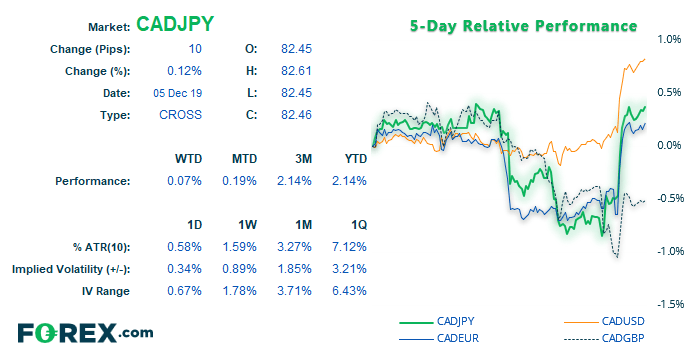
CAD/JPY: There have been a few twists and turns along the way, but the bullish wedge pattern remains in play. We have been following CAD/JPY closely has it drifted towards the August trendline, as it was either going to bounce off the trendline and confirm the wedge or invalidate both. Whilst the bounce did occur, bearish price action this week looked set to invalidate the wedge, only to see bullish range expansion take it back up to Monday’s high in breakneck speed.
For now, momentum favours the bull-cap so we’re looking for a break higher.
- Bias remains bullish above the trendline / 81.52 low wedge target remains around 83.50
- A break above 82.62 assumes bullish continuation, leaving traders the option to wait for a break, or assume the break by seeking dips above the trendline (this potentially increases reward to risk ratio, with the added risk it doesn’t breakout).
BOC held rates as expected, although their statement was optimistic enough to send the Canadian dollar sharply higher.
The statement was indeed one of optimism, although not hawkish as there is clearly no bias to raise rates. But with a relatively high OCR of 1.75%, it leaves BOC vulnerable to easing in 2020 if data turns against their forecasts. Particularly if trade talks sour. Going forward, we’ll be keeping a close eye on consumer spending and housing activity as they’ll likely hold the key as to whether they’ll remain neutral or seek to ease in future.
Summary of BOC statement:
- Maintained OCT at 1.75%
- Evidence that the global economy is stabilizing
- Growth slowed as expected, but still expected to edge higher over the next couple of years
- Housing investment, population growth, low mortgage rates and consumer spending (via higher wages) was a source of strength
- Investment spending unexpectedly slowed; we’ll continue to monitor its momentum
- CPI remains on target, and we expect it to track close to 2% over the next 2 years
- Future rate decision guided by adverse impact of conflicts against resilience of Canada’s economy (most notably consumer spending and housing activity)
Whilst the positive outlook was clearly a major factor in CAD strength, firmer oil prices also played a part too after a surprise inventory drawdown. WTI enjoyed its most bullish session since September’s oil spike and, if forward returns are to be believed, we could see oil prices rally in mid-December as historically they have rebounded 3-months after an price spike.
Technically, WTI sits just below 58.77 resistance within a bullish channel. It’s clearly a pivotal level as it has acted as both support and resistance in recent months, so with prices stalling beneath it, bears could be tempted to fade into move (at least over the near-term). Yet if prices break above 58.77 we’re in a new range and this could likely further support CAD strength.
CAD/JPY: There have been a few twists and turns along the way, but the bullish wedge pattern remains in play. We have been following CAD/JPY closely has it drifted towards the August trendline, as it was either going to bounce off the trendline and confirm the wedge or invalidate both. Whilst the bounce did occur, bearish price action this week looked set to invalidate the wedge, only to see bullish range expansion take it back up to Monday’s high in breakneck speed.
For now, momentum favours the bull-cap so we’re looking for a break higher.
- Bias remains bullish above the trendline / 81.52 low wedge target remains around 83.50
- A break above 82.62 assumes bullish continuation, leaving traders the option to wait for a break, or assume the break by seeking dips above the trendline (this potentially increases reward to risk ratio, with the added risk it doesn’t breakout).
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.