



BP impressed with Q1 results Can Shell
BP reported a better than expected underlying replacement cost of $2.6 billion up from $115 million in Q4. Shell is due to report on Thursday, can it follow in BP's footsteps?
Share this:
BP announced better than expected earnings thanks to a strong rebound in the price of oil and an exceptional Q1 for its gas trading unit following the Texas freeze. Oil prices have climbed around 25% since the start of the year.
BP reported underlying replacement cost (proxy for net profit) C of $2.6 billion up from $115 million in Q4 of 2020 and from $791 million in Q1 of 2020.
Net debt also fell by $5.6 billion to $33.3 billion, crucially falling below BP’s $35 billion line in the sand to restart the share buyback scheme. The share buyback will resume in the current quarter at a cost of $500 million.
BP had previously warned that Q1 could be challenging amid ongoing lockdown restrictions and travel restrictions. However, these numbers should serve to calm nerves. The covid vaccine rollout should help improve the outlook further, this was reflected in the International Energy Agency upgrading its oil demand forecast for 2021 by 6 million barrels a day. Market fundamentals are considerably stronger.
BP share price rallied 2% across the session and trades + 18% year to date.
What’s in store for Shell?
In the wake of BP’s strong numbers, sector peer Shell is due to report on Thursday 29th April.
Whilst rising oil prices bode well for Shell, the handling of the Texas freeze differs. As mentioned BP which has plenty of experience and a long history of handling disruption benefited from sky rocketing gas prices in the Texas freeze. Shell on the other hand has already warned that earnings will take a hit of about $200 million due to the freak weather conditions.
Whilst Shell is expected to return to profit for the first time since the start of the pandemic, guidance is likely to be underwhelming.
As with BP, Shell’s results come as it attempts to transition into a new cleaner energy giant, not an easy and certainly not a cheap task. Refocusing on cleaner energy is an expensive transition and one that must be paid for by traditional oil assets.
Shell has under-performed BP substantially rising by just 4% so far this year against BP’s 18%.
Learn more about trading equities
Where next for Royal Dutch Shell share price?
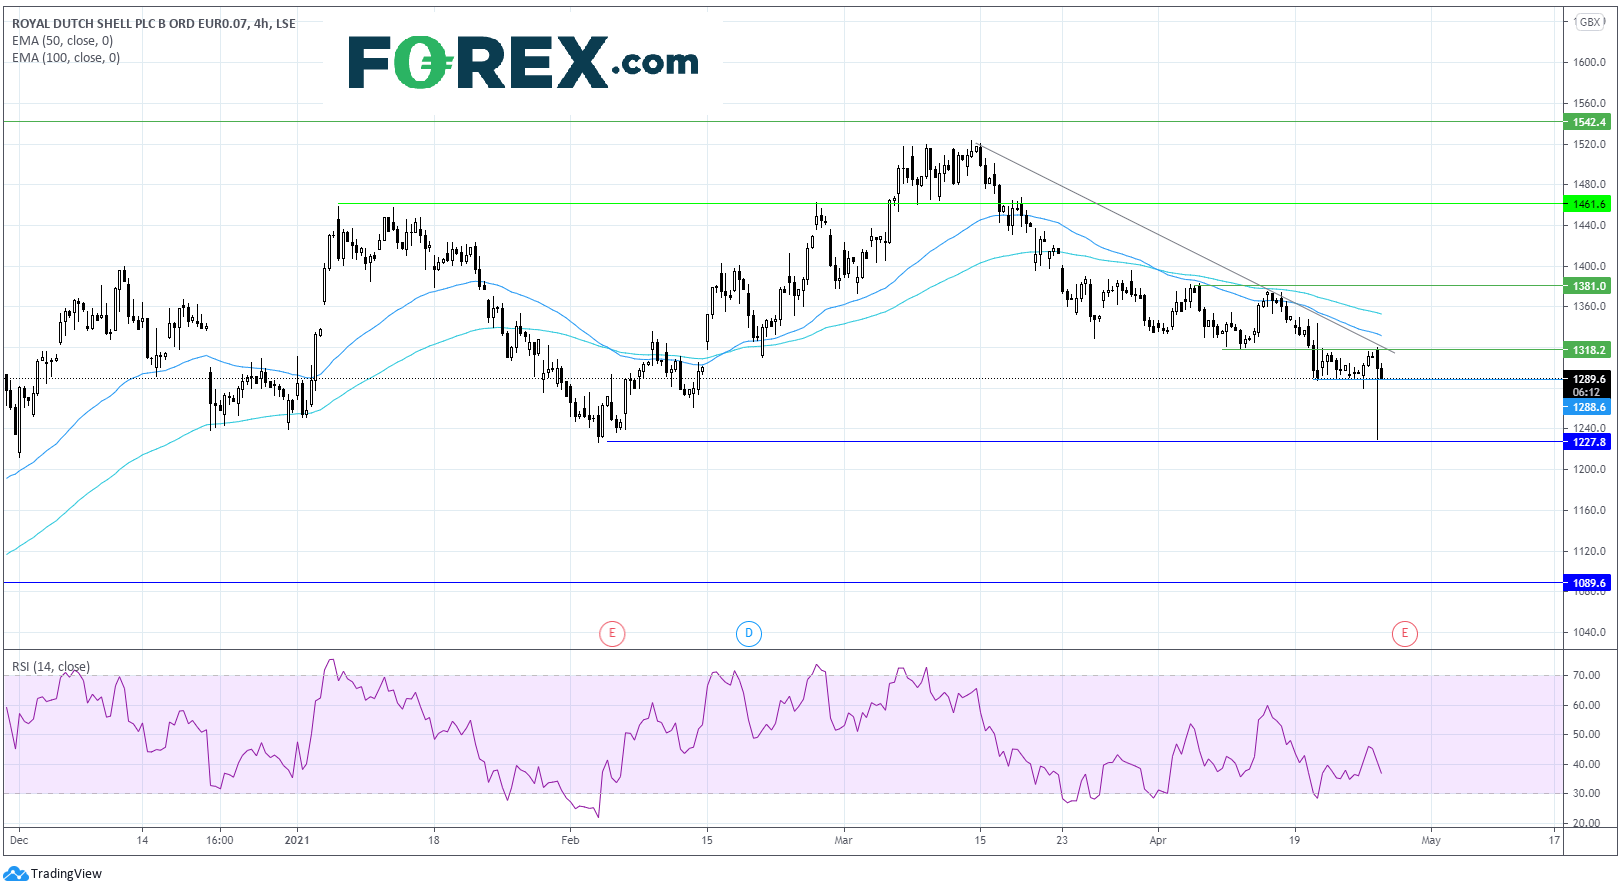
Shell trades below its descending trendline dating back to early March. It trades below its 50 & 100 EMA on the 4 hour chart in a bearish trend. The RSI is also supportive of further losses.
However, any move lower needs to clear support at 1290p a level which has support RDSB’s share price across the past week.
A break through this level could see the price look towards 1227p February & April’s low.
Should support at 1290p hold, buyers would need a move over 1320p, this week’s high and the descending trendline resistance to negate the current downtrend. Beyond here the 100 EMA at 1350p could offer some resistance.
BP announced better than expected earnings thanks to a strong rebound in the price of oil and an exceptional Q1 for its gas trading unit following the Texas freeze. Oil prices have climbed around 25% since the start of the year.
BP reported underlying replacement cost (proxy for net profit) C of $2.6 billion up from $115 million in Q4 of 2020 and from $791 million in Q1 of 2020.
Net debt also fell by $5.6 billion to $33.3 billion, crucially falling below BP’s $35 billion line in the sand to restart the share buyback scheme. The share buyback will resume in the current quarter at a cost of $500 million.
BP had previously warned that Q1 could be challenging amid ongoing lockdown restrictions and travel restrictions. However, these numbers should serve to calm nerves. The covid vaccine rollout should help improve the outlook further, this was reflected in the International Energy Agency upgrading its oil demand forecast for 2021 by 6 million barrels a day. Market fundamentals are considerably stronger.
BP share price rallied 2% across the session and trades + 18% year to date.
What’s in store for Shell?
In the wake of BP’s strong numbers, sector peer Shell is due to report on Thursday 29th April.
Whilst rising oil prices bode well for Shell, the handling of the Texas freeze differs. As mentioned BP which has plenty of experience and a long history of handling disruption benefited from sky rocketing gas prices in the Texas freeze. Shell on the other hand has already warned that earnings will take a hit of about $200 million due to the freak weather conditions.
Whilst Shell is expected to return to profit for the first time since the start of the pandemic, guidance is likely to be underwhelming.
As with BP, Shell’s results come as it attempts to transition into a new cleaner energy giant, not an easy and certainly not a cheap task. Refocusing on cleaner energy is an expensive transition and one that must be paid for by traditional oil assets.
Shell has under-performed BP substantially rising by just 4% so far this year against BP’s 18%.
Learn more about trading equities
Where next for Royal Dutch Shell share price?
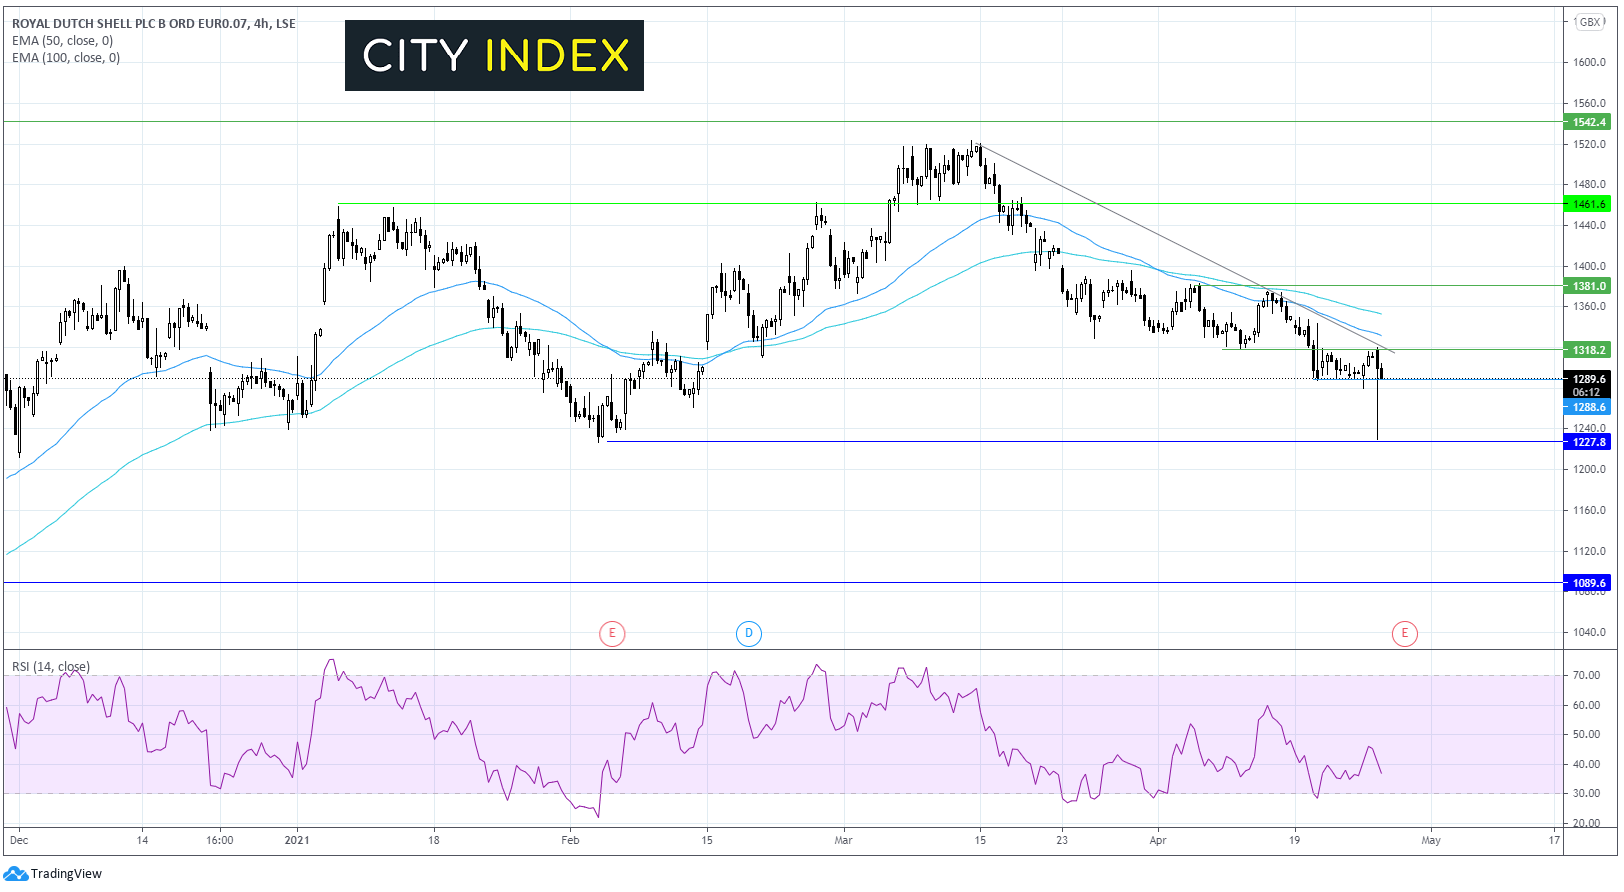
Shell trades below its descending trendline dating back to early March. It trades below its 50 & 100 EMA on the 4 hour chart in a bearish trend. The RSI is also supportive of further losses.
However, any move lower needs to clear support at 1290p a level which has support RDSB’s share price across the past week.
A break through this level could see the price look towards 1227p February & April’s low.
Should support at 1290p hold, buyers would need a move over 1320p, this week’s high and the descending trendline resistance to negate the current downtrend. Beyond here the 100 EMA at 1350p could offer some resistance.
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.