





Currency Pair of the Week USDNOK
With 2 central bank meetings this week, there are potential opportunities for a good deal of 2-way volatility in USD/NOK
Share this:

Its FOMC time! The biggest question traders will be looking for the FOMC to answer is: “Will the committee begin to talk about tapering?” Inflation has been stronger than expected since the last meeting, with a headline CPI print of 5% YoY in May. At the meeting in April, Jerome Powell continued to say that the inflation is transitory, however several board members have recently indicated that it may be time to take a closer look. In addition, Non-Farm Payrolls for April and May were weaker than expected and there are still roughly 7.4 million people who haven’t returned to jobs since the pandemic. With the Fed stating that they are willing to let inflation run hot as they focus on maximizing employment, was this NFP data enough for them to consider a tapering discussion? The Fed currently is buying $120 billion bonds per month under the quantitative easing program. If the FOMC indicates that they are talking about tapering, they need to tip-toe around their language as to not cause a “taper tantrum”. See our complete guide to the upcoming FOMC meeting HERE. The DXY went bid on Friday, presumably on position squaring and short squeezing ahead of the Fed. Separately, it appears a bi-partisan infrastructure spending plan has been agreed to worth $1.2 trillion and does not include social programs (recall Biden was looking for a $2 trillion plan.)
Everything you need to know about the Federal Reserve
The Norges Bank also meets this week to discuss interest rate policy. They are considered to be one of the front-runners to raise interest rates the earliest. At their previous meeting, Norway’s central bank said they will continue with the current monetary expansion however, they also noted that they will be ready to raise rates toward the latter half of 2021. Last week, Norway released inflation data. The headline YoY print was 2.7% vs 3.1% expected while the Core Inflation Rate was 1.5% YoY vs 2.1% expected. Will the committee consider this a “one time” miss, or will this affect their guidance and cause the central bank to push their rate hike forecast further out?
On a daily timeframe, USD/NOK hasn’t been much since mid-April when price fell below 8.3800. As a crude export led country, the value of the Norwegian Krone is often been correlated with the price of Crude Oil. However, currently, the correlation coefficient between WTI Crude Oil and USD/NOK is only -0.21, meaning there is almost no correlation between the 2 assets. If the Norges Bank is looking for inflation to come from crude oil, they aren’t getting it right now. USD/NOK has been moving lower in a descending wedge formation since putting in pandemic highs in March 2020. On May 21st, price drifted sideways outside the wedge. Expectations are that price will retrace the wedge, however thus far, price has yet to do so.
Source: Tradingview, City Index
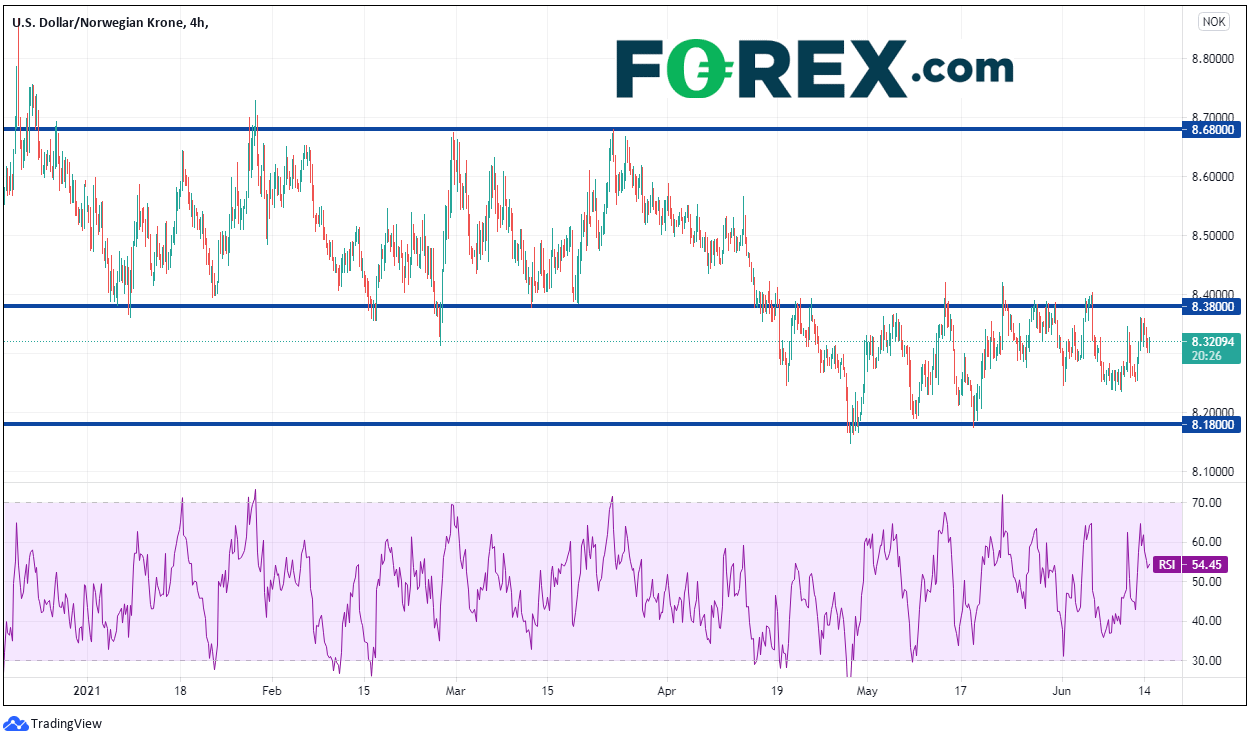
On a 240-minute timeframe, it’s easy to see that since the beginning of 2021, USD/NOK has been trading in 2 very well-defined ranges: between 8.38 and 8.68 prior to April 19th and between 8.18 and 8.38 from April 18th until today. The pair has tried multiple times to trade outside either end of those ranges, however, continues to fail. Will either of the central bank meetings his week be able to push USD/NOK above 8.38 or below 8.18. Resistance is at the prior trading range highs of 8.68. The 200 Day Moving Average sits just above that at 8.6880. If the Norges Bank remains hawkish than the FOMC, the pair can break down below 8.18, which also happens to confluence with the top downward sloping trendline of the wedge on the daily timeframe, the next support level is the bottom trendline of the wedge near 8.08.
Source: Tradingview, City Index
With 2 central bank meetings this week which could affect USD/NOK, there are potential opportunities for a good deal of 2-way volatility in this pair.
Learn more about forex trading opportunitiesIts FOMC time! The biggest question traders will be looking for the FOMC to answer is: “Will the committee begin to talk about tapering?” Inflation has been stronger than expected since the last meeting, with a headline CPI print of 5% YoY in May. At the meeting in April, Jerome Powell continued to say that the inflation is transitory, however several board members have recently indicated that it may be time to take a closer look. In addition, Non-Farm Payrolls for April and May were weaker than expected and there are still roughly 7.4 million people who haven’t returned to jobs since the pandemic. With the Fed stating that they are willing to let inflation run hot as they focus on maximizing employment, was this NFP data enough for them to consider a tapering discussion? The Fed currently is buying $120 billion bonds per month under the quantitative easing program. If the FOMC indicates that they are talking about tapering, they need to tip-toe around their language as to not cause a “taper tantrum”. See our complete guide to the upcoming FOMC meeting HERE. The DXY went bid on Friday, presumably on position squaring and short squeezing ahead of the Fed. Separately, it appears a bi-partisan infrastructure spending plan has been agreed to worth $1.2 trillion and does not include social programs (recall Biden was looking for a $2 trillion plan.)
Everything you need to know about the Federal Reserve
The Norges Bank also meets this week to discuss interest rate policy. They are considered to be one of the front-runners to raise interest rates the earliest. At their previous meeting, Norway’s central bank said they will continue with the current monetary expansion however, they also noted that they will be ready to raise rates toward the latter half of 2021. Last week, Norway released inflation data. The headline YoY print was 2.7% vs 3.1% expected while the Core Inflation Rate was 1.5% YoY vs 2.1% expected. Will the committee consider this a “one time” miss, or will this affect their guidance and cause the central bank to push their rate hike forecast further out?
On a daily timeframe, USD/NOK hasn’t been much since mid-April when price fell below 8.3800. As a crude export led country, the value of the Norwegian Krone is often been correlated with the price of Crude Oil. However, currently, the correlation coefficient between WTI Crude Oil and USD/NOK is only -0.21, meaning there is almost no correlation between the 2 assets. If the Norges Bank is looking for inflation to come from crude oil, they aren’t getting it right now. USD/NOK has been moving lower in a descending wedge formation since putting in pandemic highs in March 2020. On May 21st, price drifted sideways outside the wedge. Expectations are that price will retrace the wedge, however thus far, price has yet to do so.
Source: Tradingview, FOREX.com
On a 240-minute timeframe, it’s easy to see that since the beginning of 2021, USD/NOK has been trading in 2 very well-defined ranges: between 8.38 and 8.68 prior to April 19th and between 8.18 and 8.38 from April 18th until today. The pair has tried multiple times to trade outside either end of those ranges, however, continues to fail. Will either of the central bank meetings his week be able to push USD/NOK above 8.38 or below 8.18. Resistance is at the prior trading range highs of 8.68. The 200 Day Moving Average sits just above that at 8.6880. If the Norges Bank remains hawkish than the FOMC, the pair can break down below 8.18, which also happens to confluence with the top downward sloping trendline of the wedge on the daily timeframe, the next support level is the bottom trendline of the wedge near 8.08.
Source: Tradingview, FOREX.com
With 2 central bank meetings this week which could affect USD/NOK, there are potential opportunities for a good deal of 2-way volatility in this pair.
Learn more about forex trading opportunitiesRelated tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.