



DAX Stabilises as Trump teases 45 day ceasefire
Risk sentiment remains fragile, but underlying data continues to hold up better than market narratives suggest. With energy‑led disinflation potentially resuming if geopolitics cool, the Fed’s “higher for longer” stance remains intact. The DAX shows early signs of stabilisation after a corrective downtrend, though key resistance caps the move for now. Markets remain headline‑driven, not data‑driven — for the moment.
Share this:
Liquidity & Holiday Context
- Most of Europe remains on holiday (Easter / Ching Ming), including Germany, France, Italy, Spain, Switzerland and the UK
- Liquidity expected to be subdued across European assets
- Volatility likely driven by US data and geopolitical headlines
Geopolitics – Iran, Hormuz & Ceasefire Talk
- Trump’s ultimatum expires today, but rhetoric has softened materially
- Axios reports discussions underway for a 45‑day ceasefire (“Islamabad Accord”):
- Immediate ceasefire
- Strait of Hormuz reopened
- 15–20 days of negotiations toward permanent deal
- Framework includes nuclear restraints in exchange for sanctions relief & asset release
- Iran has not yet committed, despite backing from Pakistan, China and the US
- Over the weekend, Iran cleared Iraq to resume Hormuz shipping, reinforcing a country‑by‑country reopening strategy
- Near‑term market takeaway:
- Binary risk event avoided for now
- Energy risk premium vulnerable if ceasefire rhetoric gains traction
- Headlines remain the dominant driver
US Data – ISM Services (March)
US services data are estimated to show meaningful increases, contradicting current slowdown fears.
|
Component |
Expectation |
Prev |
|
ISM Services PMI |
56.1 |
54.0 |
|
Business Activity |
59.9 |
58.0 |
|
Employment |
51.8 |
51.7 |
|
New Orders |
58.6 |
57.6 |
|
Prices Paid |
63.0 |
70.0 |
Key Takeaways
- Services activity expected to reaccelerated
- Employment expected to remains expansionary
- Prices to ease sharply, suggesting no immediate second‑round inflation spiral due to energy cost increases.
- Together with:
- Strong job data
- Robust vehicle sales → The data depicts a resilient demand environment, not recession. However, we will need to wait for the actual numbers.
Macro Read‑Across
- The economy is appearing to be holding up better than sentiment suggests
- Disinflation via energy may resume if geopolitics cool
- Data vs narrative mismatch reflects headline‑driven risk aversion, not fundamentals
- Supports Fed “higher for longer, no rush” stance
Germany 40 (DAX) – Technical Outlook
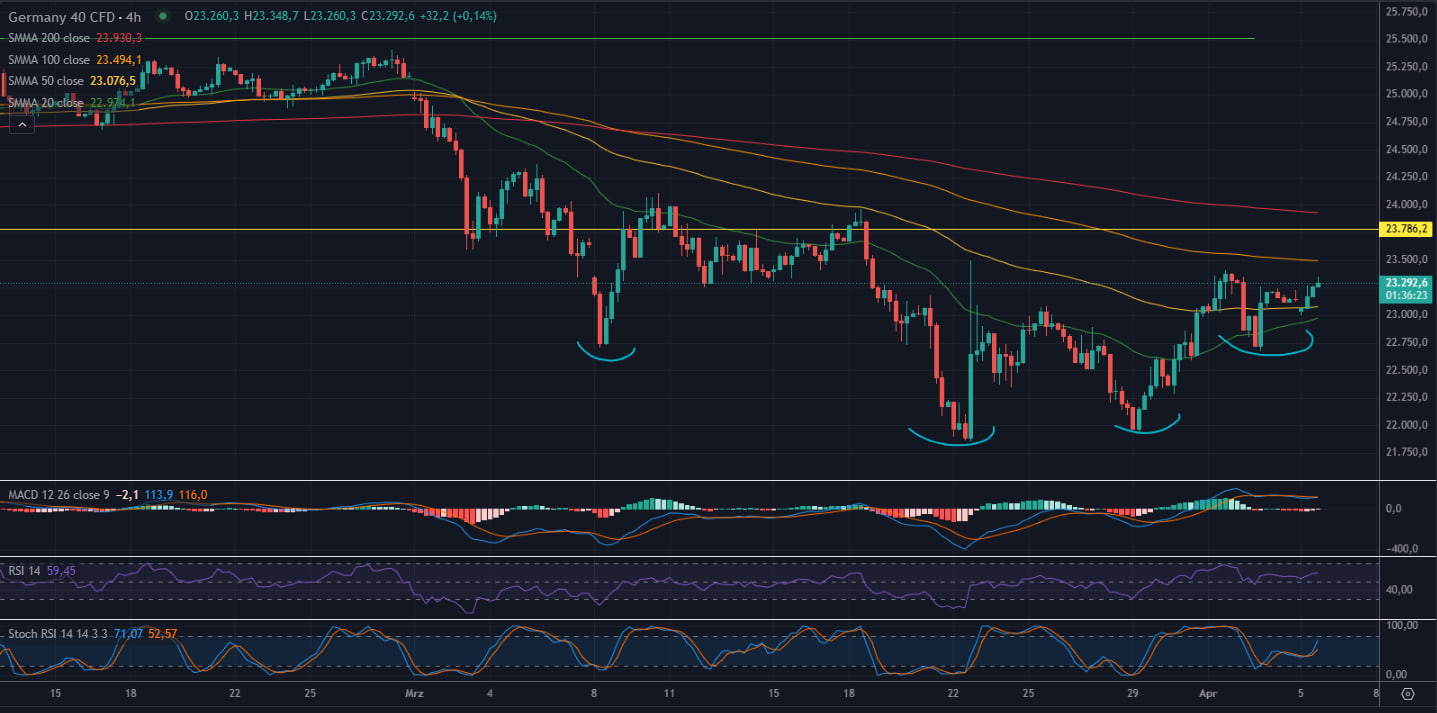
- The index remains in a broader corrective downtrend
- However, price action shows early stabilisation signals due to 3 consecutive higher highs
Structure
- Higher lows formed since late‑March low near 22,300
- Price attempting to grind higher back above the EMA 100 around 23,500
- Still capped by bearishly aligned 50, 100 and 200‑period SMAs
Momentum
- MACD: now positive → downside momentum fading
- RSI: mid‑50s → neutral‑to‑constructive
- Stochastics: elevated and increasing after flattening → upside gaining urgency
Key Levels
- Resistance: 23,500–23,900 (critical EMAs)
- Breakout zone: 23,900–24,000 (trend improvement signal)
- Support: 23,200, 22,900 & 22,000
Bias
- Stabilisation > reversal
- Failure at resistance keeps move corrective
- A catalyst (geopolitical or macro) is needed for confirmation
Bottom Line
- Holiday liquidity + headline risk = fragile price action
- Geopolitics are shifting from escalation to negotiation mode, but remain unresolved
- US data argues against recession, supporting risk selectively
- DAX stabilising, but trend reversal not confirmed
- Markets remain headline‑driven, not data‑driven — for now
Regards,
Philip Papageorgiou
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.