




ECB To Propel Dax Higher
Increase in PEPP in addition to macro projections to grab traders attention
Share this:

The main focus for the ECB meeting this Thursday will be the expected increase in the Pandemic Emergency Purchase Programme even as the region shows tentative signs of recovery. However, that won’t be all traders will be looking out for from Christine Lagarde and Co.
Latest macro projections
The newest set of staff forecasts will be closely eyed given that March projections are now so desperately out of date. In April the ECB set out three scenarios, GDP declining by 5%, 8% and 12% in 2020, depending on the severity of the coronavirus crisis.
The newest set of staff forecasts will be closely eyed given that March projections are now so desperately out of date. In April the ECB set out three scenarios, GDP declining by 5%, 8% and 12% in 2020, depending on the severity of the coronavirus crisis.
Realistically a mild hit to the economy can be ruled out and we can expect the forecast to fall between 8% -12% decline. The European Commission is forecasting -7.7% contraction.
Google mobility data shows that some eurozone countries have already returned to around 80% of their January activity levels, whilst others show just a 60% return to normality. Soft indicators point to a low point in April but with activity rebounding in May. Beyond Q2 GDP forecasts will involve a large element of guess work, depending largely on the course that the virus takes and the effectiveness of the containment measures.
Google mobility data shows that some eurozone countries have already returned to around 80% of their January activity levels, whilst others show just a 60% return to normality. Soft indicators point to a low point in April but with activity rebounding in May. Beyond Q2 GDP forecasts will involve a large element of guess work, depending largely on the course that the virus takes and the effectiveness of the containment measures.
Inflation forecasts
April’s scenario analysts lacked any inflation forecasts and March’s are as good as irrelevant given the complete change in circumstances. Falling energy prices, rising unemployment and business closures point to falling inflation. That said, some ECB council members believe that supply chain disruptions could offer some support to prices and inflation.
PEPP & scenario analysis
The ECB will have plenty more to discuss, namely the PEPP and the German constitutional court ruling. The ECB are expected to explore ways to continue its public sector purchase programme without including the Bundesbank.
As for the PEPP, the ECB are expected to decide on a significant increase to the programme which runs out in October. This programme keeps the Bundesbank on board despite the German court ruling.
The ECB will have plenty more to discuss, namely the PEPP and the German constitutional court ruling. The ECB are expected to explore ways to continue its public sector purchase programme without including the Bundesbank.
As for the PEPP, the ECB are expected to decide on a significant increase to the programme which runs out in October. This programme keeps the Bundesbank on board despite the German court ruling.
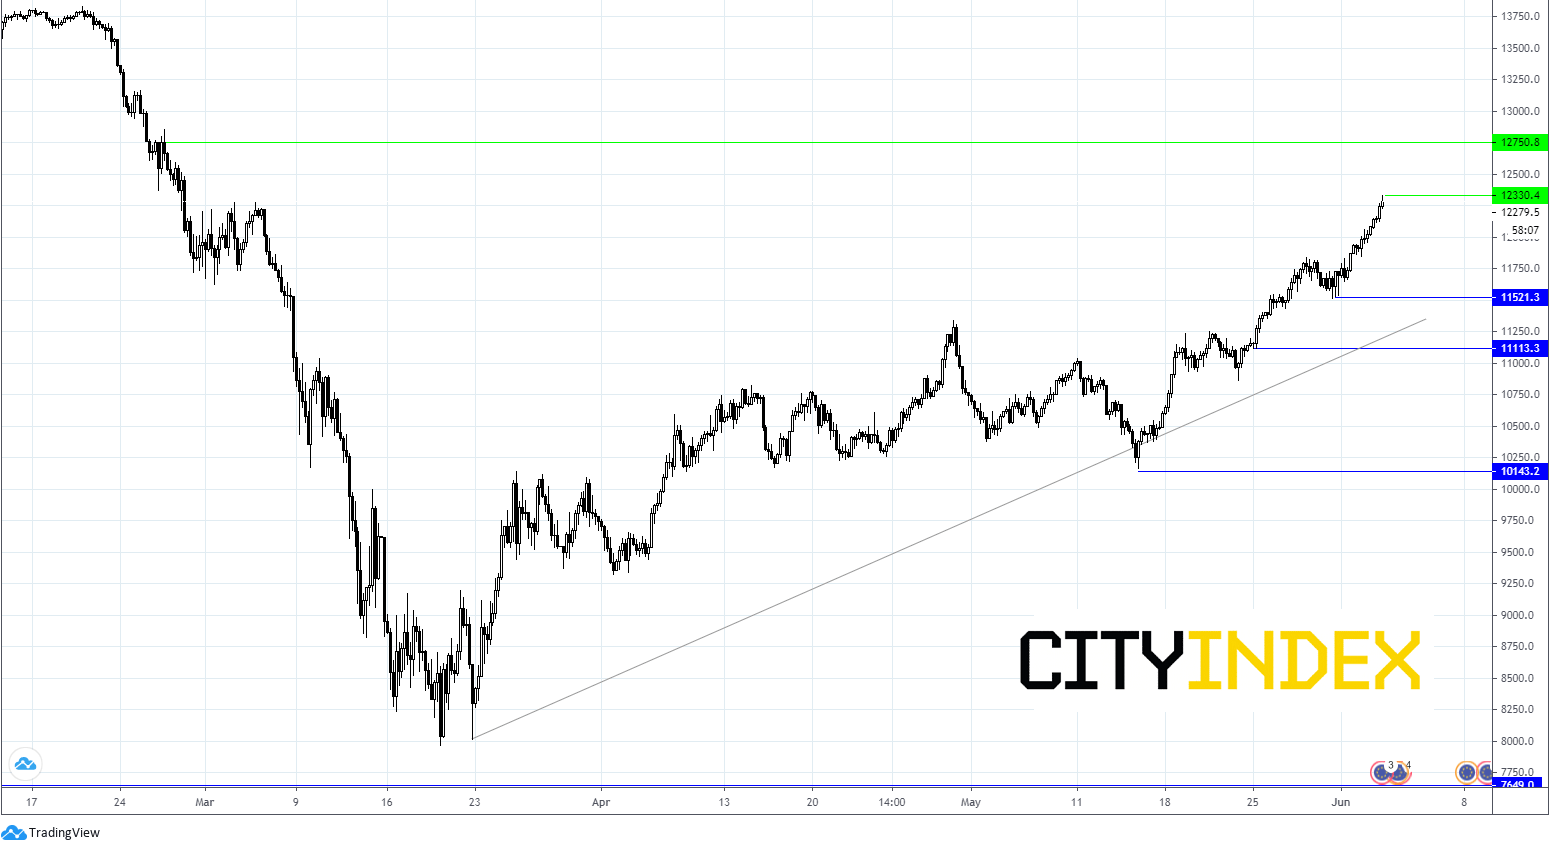
An increase in the region of €250 billion could be on the cards to top the programme up to €1 trillion and to send the message that the ECB is still supporting the economy. Under this scenario we would expect the euro to rally but remain within known ranges. The Dax could also push higher as extra stimulus would boost risk sentiment, emboldening investors to take on riskier assets.
An increase of €500 comes with a medium probability and would send EUR/USD surging higher towards $1.13 on the unequivocal message. Again, the Dax would be expected to advance thanks to more cheap money boosting businesses.
Any hints of negative rates or disappointment surrounding PEPP, such as no action, could drag the EUR/USD lower back towards €1.11, whilst the Dax could also underperform.
Any hints of negative rates or disappointment surrounding PEPP, such as no action, could drag the EUR/USD lower back towards €1.11, whilst the Dax could also underperform.
Dax chart
The main focus for the ECB meeting this Thursday will be the expected increase in the Pandemic Emergency Purchase Programme even as the region shows tentative signs of recovery. However, that won’t be all traders will be looking out for from Christine Lagarde and Co.
Latest macro projections
The newest set of staff forecasts will be closely eyed given that March projections are now so desperately out of date. In April the ECB set out three scenarios, GDP declining by 5%, 8% and 12% in 2020, depending on the severity of the coronavirus crisis.
The newest set of staff forecasts will be closely eyed given that March projections are now so desperately out of date. In April the ECB set out three scenarios, GDP declining by 5%, 8% and 12% in 2020, depending on the severity of the coronavirus crisis.
Realistically a mild hit to the economy can be ruled out and we can expect the forecast to fall between 8% -12% decline. The European Commission is forecasting -7.7% contraction.
Google mobility data shows that some eurozone countries have already returned to around 80% of their January activity levels, whilst others show just a 60% return to normality. Soft indicators point to a low point in April but with activity rebounding in May. Beyond Q2 GDP forecasts will involve a large element of guess work, depending largely on the course that the virus takes and the effectiveness of the containment measures.
Google mobility data shows that some eurozone countries have already returned to around 80% of their January activity levels, whilst others show just a 60% return to normality. Soft indicators point to a low point in April but with activity rebounding in May. Beyond Q2 GDP forecasts will involve a large element of guess work, depending largely on the course that the virus takes and the effectiveness of the containment measures.
Inflation forecasts
April’s scenario analysts lacked any inflation forecasts and March’s are as good as irrelevant given the complete change in circumstances. Falling energy prices, rising unemployment and business closures point to falling inflation. That said, some ECB council members believe that supply chain disruptions could offer some support to prices and inflation.
PEPP & Scenario analysis
The ECB will have plenty more to discuss, namely the PEPP and the German constitutional court ruling. The ECB are expected to explore ways to continue its public sector purchase programme without including the Bundesbank.
As for the PEPP, the ECB are expected to decide on a significant increase to the programme which runs out in October. This programme keeps the Bundesbank on board despite the German court ruling.
The ECB will have plenty more to discuss, namely the PEPP and the German constitutional court ruling. The ECB are expected to explore ways to continue its public sector purchase programme without including the Bundesbank.
As for the PEPP, the ECB are expected to decide on a significant increase to the programme which runs out in October. This programme keeps the Bundesbank on board despite the German court ruling.
An increase in the region of €250 billion could be on the cards to top the programme up to €1 trillion and to send the message that the ECB is still supporting the economy. Under this scenario we would expect the euro to rally but remain within known ranges. The Dax could also push higher as extra stimulus would boost risk sentiment, emboldening investors to take on riskier assets.
An increase of €500 comes with a medium probability and would send EUR/USD surging higher towards $1.13 on the unequivocal message. Again, the Dax would be expected to advance thanks to more cheap money boosting businesses.
Any hints of negative rates or disappointment surrounding PEPP, such as no action, could drag the EUR/USD lower back towards €1.11, whilst the Dax could also underperform.
Any hints of negative rates or disappointment surrounding PEPP, such as no action, could drag the EUR/USD lower back towards €1.11, whilst the Dax could also underperform.
Dax Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.