



EUR/USD holds 1.08 ahead of ECB, USD/JPY hits 7-month high ahead of BOJ
The US dollar regained strength overnight as investors absorbed the latest hawkish FOMC meeting, sending USD/JPY to a 7-month high. Meanwhile, EUR/USD holds 1.08 ahead of today's ECB meeting.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 18.6 points (0.26%) and currently trades at 7,180.30
- Japan's Nikkei 225 index has risen by 146.23 points (0.43%) and currently trades at 33,647.63
- Hong Kong's Hang Seng index has risen by 160.89 points (0.83%) and currently trades at 19,569.31
- China's A50 Index has risen by 69.22 points (0.54%) and currently trades at 12,791.61
UK and Europe:
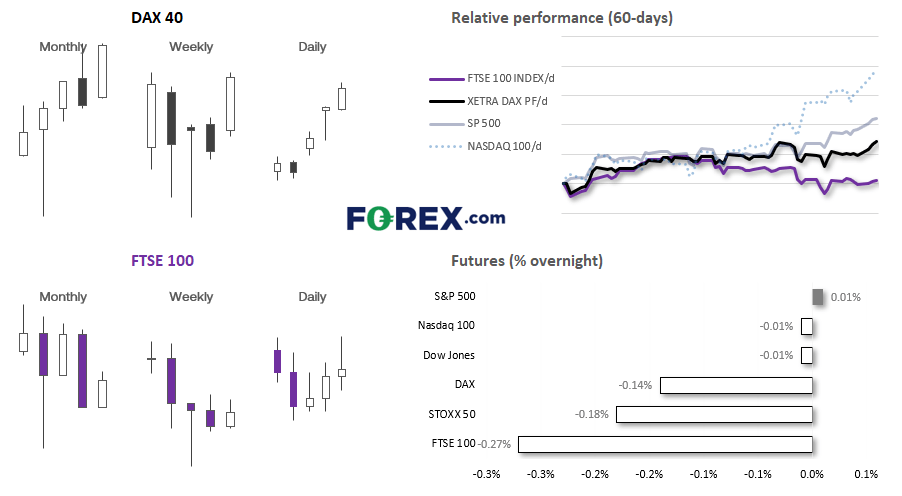
- UK's FTSE 100 futures are currently down -20.5 points (-0.27%), the cash market is currently estimated to open at 7,582.24
- Euro STOXX 50 futures are currently down -8 points (-0.18%), the cash market is currently estimated to open at 4,367.98
- Germany's DAX futures are currently down -23 points (-0.14%), the cash market is currently estimated to open at 16,287.79
US Futures:
- DJI futures are currently down -2 points (-0.01%)
- S&P 500 futures are currently up 0.25 points (0.01%)
- Nasdaq 100 futures are currently down -2.25 points (-0.01%)

- The Fed delivered a hawkish hike and upgraded their 2023 OCR forecast to include an additional 50bp of hikes, for a peak rate of 5.6%
- The USDwas the strongest major overnight, as traders across Asia seemingly took more notice of the potential for the Fed to hike two more times
- USD/JPY rose to a 7-month high with widening yield differentials ahead of tomorrow’s BOJ meeting, where no policy change is expected
- Another strong employment report for Australia kept the pressure on the RBA to hike rates, with over 79k jobs added, the participation rate hitting a record high and unemployment back at 3.6%
- New Zealand entered a technical recession with a second consecutive quarter of negative growth
- The PBOC eased interest rates for the first time in 10 months in response to weak economic data, sending USD/CNH to a fresh 7-month high
- Gold teased a break to a 3-month low as Fed pressures keep bulls on the ropes, and reminding traders that the lows around 1930 remain key
The ECB’s interest rate decision follows hot on the heels of the FOMC meeting. With signs of disinflation continuing to appear across Europe, the case for aggressive ECB hikes has receded. But, like the Fed, the ECB will have no appetite to make any hike sound less hawkish (and even less so, now that the Fed delivered a more hawkish message than expected). A 25bp hike seemed like a done deal, but there will be some pondering whether they’ll go for a 50 to close the gap with a Fed. Whilst I’m backing a 25bp hike today, I’m not expecting anything special from their forward guidance.
EUR/USD daily chart:

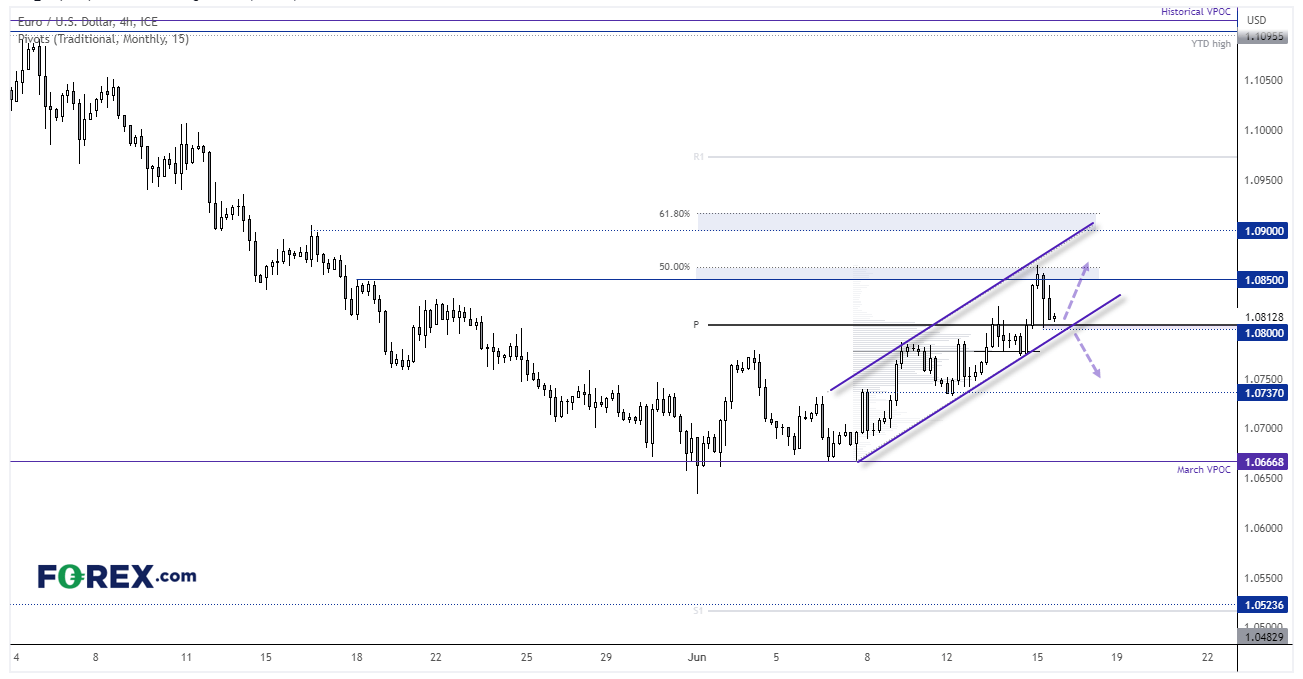
EUR/USD rose up to our second resistance zone mentioned in yesterday’s report, before pulling back towards 1.0800. It pair has remained within the top half of yesterday’s range overnight, holding above the lower trendline of its bullish channel and the 1.08 handle. Perhaps the ECB will surprise with a 50bp hike, in which case bulls could look for setups around the current day’s lows. But if we’re to get a 25bp with little in the way of clues for future meetings, perhaps traders will refocus on US dollar strength and bring the euro crashing back through 1.08000 / trend support.
USD/JPY chart:
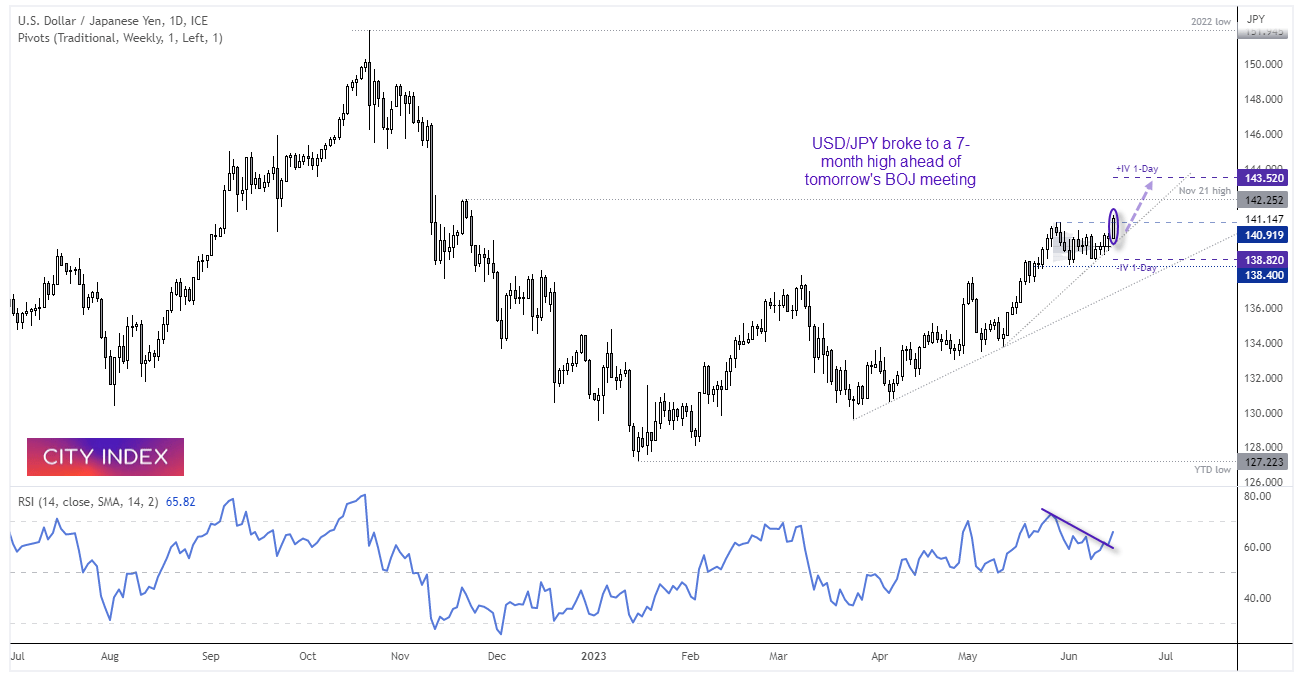

Whilst the US dollar pulled back following the Fed’s meeting, it wasted little time in the Asian session finding its feet again and becoming the strongest FX major overnight. And with expectations of yet another non-event at tomorrow’s BOJ meeting, yield differentials favour a higher USD/JPY – and that has helped it push to a 7-month high.
The daily trend remains in a bullish trend and momentum has turned higher from its recent consolidation. 1-week implied volatility implies ~68% chance of prices landing between 138.82 – 143.52 next week, so unless the BOJ stun markets with some sort of action (however small), we favour an initial run to the November high. A break above which brings the 144 handle into focus.
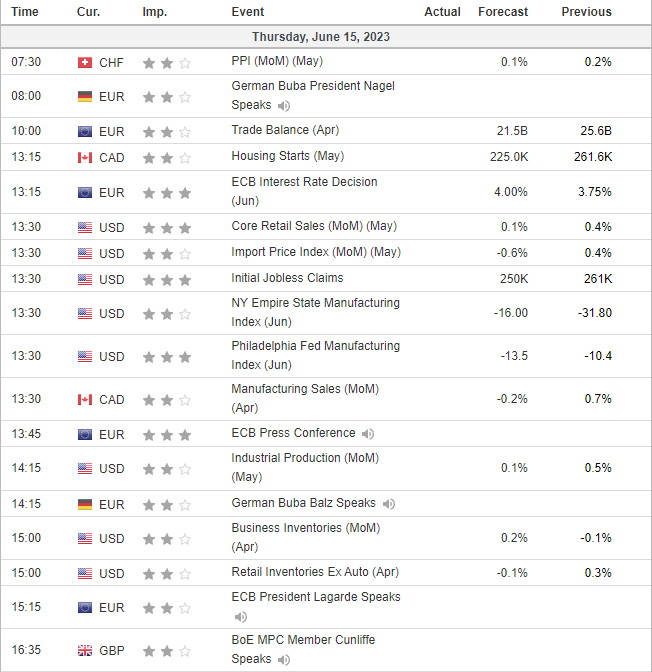
Economic events up next (Times in GMT+1)
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.