



DAX bulls eye a break of 16k: European open – 13th July 2023
Equity markets across Asia tracked Wall Street higher and index futures point to another strong start for European markets today, which leaves the potential for further gains on the DAX.
Share this:

Asian Indices:
- Australia's ASX 200 index rose by 113.9 points (1.6%) and currently trades at 7,249.60
- Japan's Nikkei 225 index has risen by 491.09 points (1.64%) and currently trades at 32,437.16
- Hong Kong's Hang Seng index has risen by 469.41 points (2.49%) and currently trades at 19,330.36
- China's A50 Index has risen by 195.73 points (1.56%) and currently trades at 12,757.43
UK and Europe:
- UK's FTSE 100 futures are currently up 4 points (0.05%), the cash market is currently estimated to open at 7,420.11
- Euro STOXX 50 futures are currently up 7 points (0.16%), the cash market is currently estimated to open at 4,367.46
- Germany's DAX futures are currently up 18 points (0.11%), the cash market is currently estimated to open at 16,041.00
US Futures:
- DJI futures are currently up 51 points (0.15%)
- S&P 500 futures are currently up 11.5 points (0.26%)
- Nasdaq 100 futures are currently up 66.5 points (0.43%)
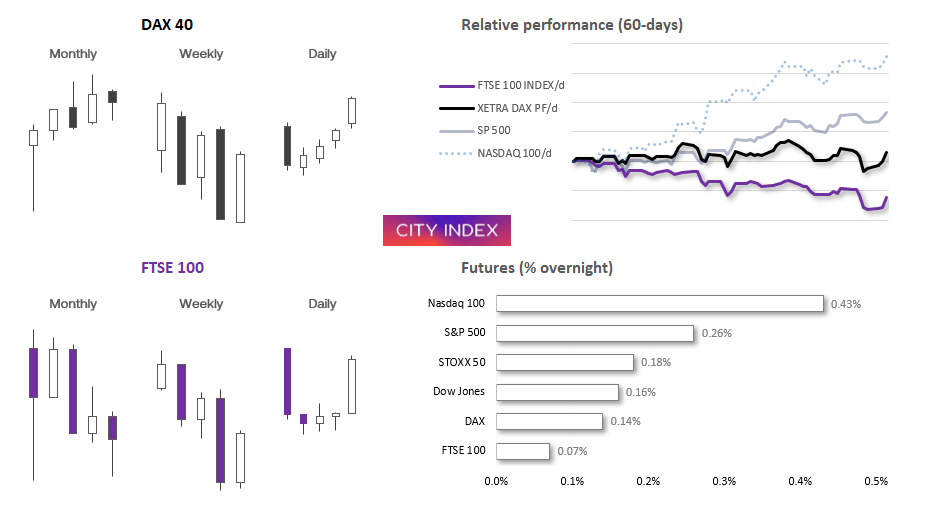

If you needed any reminding that inflation data remains a key driver for global sentiment, then yesterday’s US CPI report should have served you well. With annual, monthly CPI and core inflation prints all below expectations, it certainly stirred some excitement that the Fed may hike one last time in two weeks – with some even speculating whether they’ll pause in July. With money markets suggesting a 92% chance of a hike, I feel inclined to believe them and run with that hike. But any comments next week from Fed members will be scrutinised as strongly as ever, as we veer towards the Fed blackout period ahead of their next meeting.
Asian indices were broadly higher as they tracked the sentiment of Wall Street, looking past weak growth concerns from China’s trade data. Exports slumped -12.4% y/y, down from -7.5% prior and missing estimates of 0.5%. Imports also missed the mark at -6.8% y/y versus -6.1% expected, down from -4.5%.
US jobless claims, PPI in focus today
On today’s docket we have several key data points for the UK at 07:00 including GDP, trade balance and output data for construction, manufacturing and industry. It could take quite a series of misses to shake the pound-bullish tree, given all bets are on for a 50bp BOE hike (thanks to stronger wages data). French CPI is at 07:45, industrial production for the eurozone at 10:00, the OPEC monthly report is at 12:00 and then ECB monetary policy meeting minutes at 12:30.
Given the significance of yesterday’s CPI report, a soft set of US PPI data at 13:30 could further bolster bets of a less hawkish Fed. But a potential fly in the ointment is if we see jobless claims data recede further as it could shed some doubt over a less-hawkish Fed with such a tight labour market.
What immediately jumps out on the FX major dashboard is how most of the pairs have either traded higher or lower over the past five days. It brings into question how much juice is left in the tank to sustain these moves, and the fact that we have only seen a minor follow-through in Asia reiterates this point. Implied volatility is also relatively low to suggest the more exciting action for the week may be behind us for the week. And if there is a potential catalyst for some retracement, perhaps we might find it in stronger employment data for the US later.
DAX daily chart:
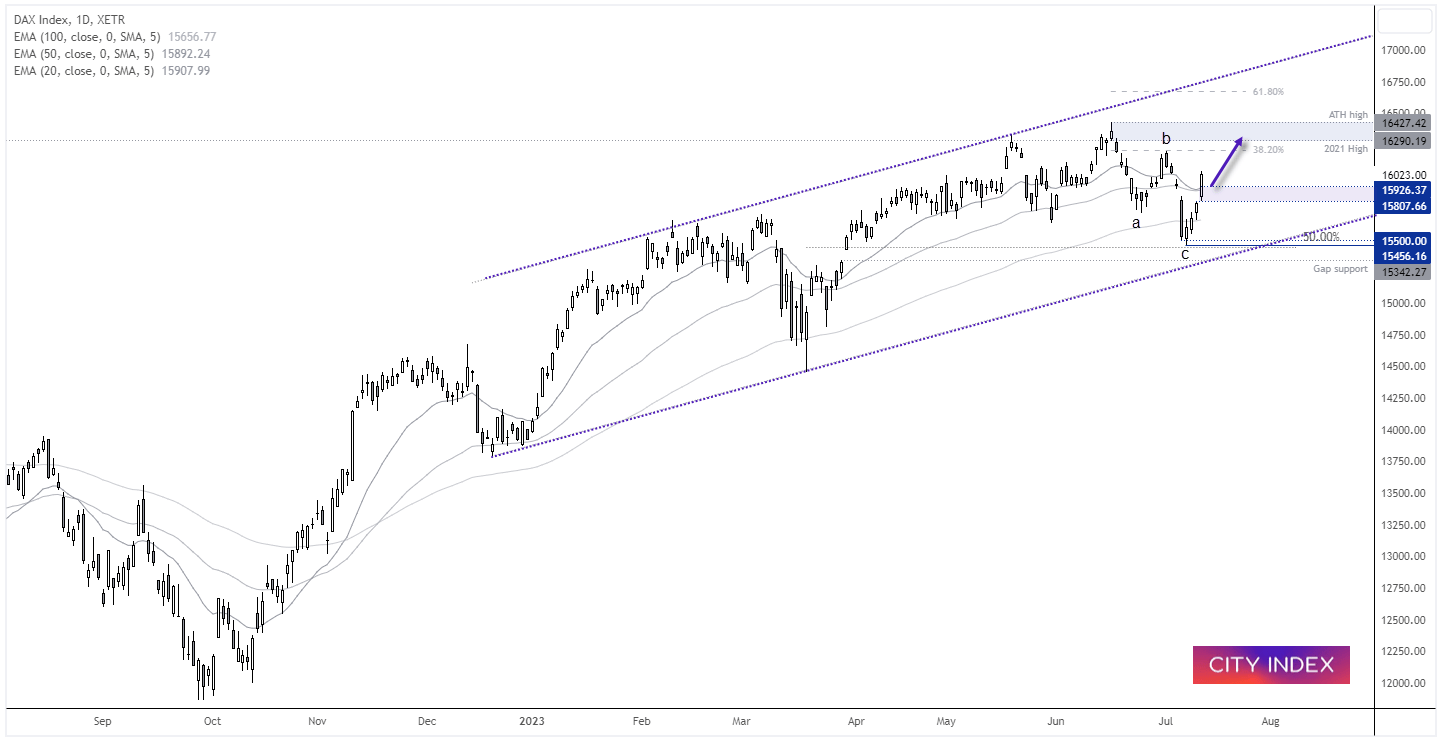
The DAX may have completed a classic 3-wave retracement (ABC) on the daily chart, having found support just below 15,500 at a 50% retracement level. The market has rallied for four consecutive days since that low, so perhaps upside could be limited over the near-term. But with index futures pointing higher ahead of the open, it looks like bulls are set for another crack at breaking 16,000 today. Should prices retrace (whether later today, tomorrow or next week), the look signs of support around the 20 and 50-day EMA around 15,925 or yesterday’s low around 15,800. But given the 3-wave retracement spanned most of the bullish channel and bullish momentum has turned sharply higher, we think a run to the 2021 and ATH (all-time high) is now on the card.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.


AUD/USD forecast: Currency Pair of the Week | September 28, 2026
The week has started with stocks, gold, silver and bitcoin all falling, as crude oil rebounded and bond yields pushed further higher. Trump refusing to agree to Tehran’s proposal to re-open the Strait of Hormuz has left the markets disappointed. Still, reports that mediators are expected to hold talks with the two sides on an amended version of the 7-day proposal that Iran presented, keeps hopes alive that we may see some progress.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.