



DAX Pushes Toward 24,400; Markets Await Fed Guidance
US equities slipped ahead of the Fed meeting, with Dow -0.45%, S&P 500 -0.35%, and Nasdaq -0.14%. Tech held firm on M&A headlines and AI optimism. Fed cut odds remain strong at 89%, but focus shifts to Powell’s guidance and the 2026 dot plot. Germany 40 trades at 24,126 after clearing 24,000, signaling bullish momentum toward 24,400. Commodities stayed muted as copper eased and crude held soft.
Share this:
US Equity Session
Indices drifted lower ahead of the Fed. Dow -0.45%, S&P 500 -0.35%, Nasdaq -0.14%. Technology was the only sector in the green; Communications and Consumer Discretionary lagged. Alphabet and Netflix weakened after a Paramount–Warner Bros development reshaped media sentiment. Tesla fell on valuation and EV-cycle concerns after a downgrade. A brief lift from reports of possible NVIDIA H200 export permissions to China faded quickly.
US Macro Backdrop
Recent data reinforces expectations of a December Fed rate cut. Headline PCE rose to 2.8% y/y; core eased to 2.8%. Inflation expectations in the Michigan survey declined to the lowest since January. Sentiment improved as expectations strengthened. The rate cut appears assured; uncertainty lies in the 2026 policy path.
Policy and Rates
Fed cut expectations remain firm: markets assign ~89% probability to a 25bp reduction. Market focus shifts to guidance and the 2026 dot plot.
M&A and Single-Stock Moves
Paramount Skydance jumped on its USD 108.4bn bid for Warner Bros Discovery. Confluent rallied on IBM’s USD 11bn takeover. Tech leadership reflected strength in Microsoft, Nvidia and Broadcom; communications services lagged.
AI Policy
The administration signalled a national AI regulatory framework via executive order, interpreted as supportive for AI-exposed firms.
Trade/Tariffs
The administration reported progress with China on agricultural purchases and semiconductor exports, with NVIDIA H200 shipments allowed for approved China customers under a fee structure. Simultaneously, threats were issued: a 5% tariff on Mexico over water-release disputes; possible fertiliser tariffs on Canada. Lawmakers urged easing Japan tariffs; an India trade effort is underway.
China’s leadership warned that tariff escalation is producing mutually damaging outcomes and highlighted AI’s growing relevance in trade policy.
Additional US Headlines
A USD 12bn farm-aid package was confirmed. Farmers view the relief as temporary. USD stayed rangebound ahead of the Fed. BlackRock filed for a staked ETH ETF.
Europe Equities Outlook
STOXX 600 faces a third year of stagnant earnings in 2025 due to geopolitical pressures, China softness, FX headwinds and US tariffs. Analysts expect a 12% earnings rebound in 2026 with 3.6% revenue growth. A margin surge implied by consensus appears optimistic; trend margins point instead to ~7% earnings growth. Stronger conditions in AI, defence and financials could add modest upside.
DAX Technical Analysis 1 Day
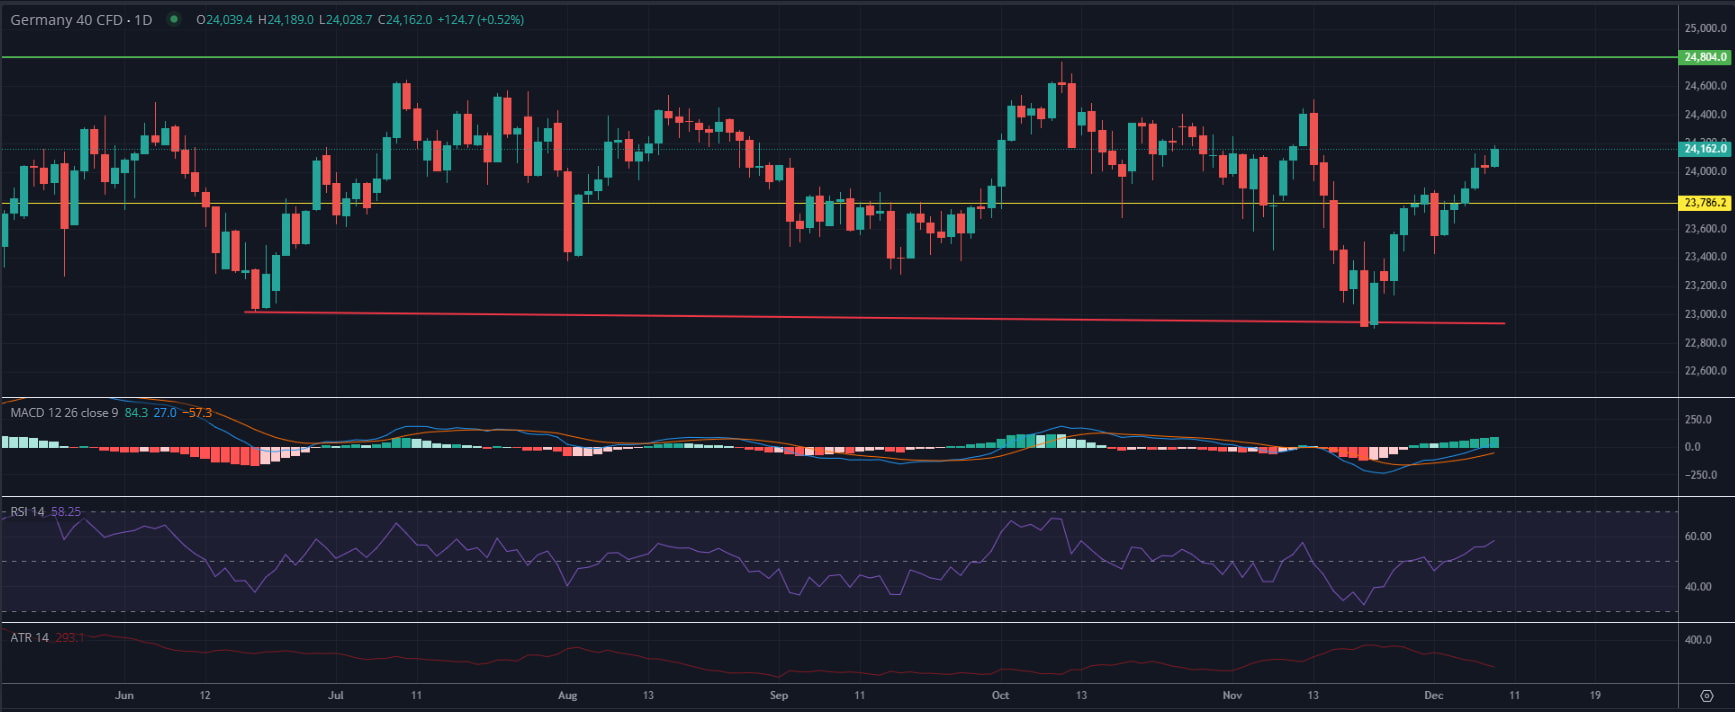
Germany 40 has advanced further, now trading at 24,126 after a strong continuation of the breakout above the 23,740 pivot level. Price action is approaching the upper half of the established range between 22,900 and 24,884, with the current structure showing bullish dominance in the short term. The breakout above 24,000 is technically significant, as it confirms buyers’ control and positions the index for a potential test of the next resistance zone at 24,400–24,884. Sustained closes above 24,000 would reinforce bullish sentiment, while any rejection near 24,200 could trigger consolidation or a pullback toward 23,740, which now acts as support.
Momentum indicators remain aligned with the bullish outlook. MACD is positive and widening, signaling strong upward momentum, while RSI at 58.25 is trending higher but still below overbought levels, leaving room for further upside. ATR at 301.1 indicates volatility remains elevated, consistent with the recent sharp move. The technical bias favors continuation toward 24,400 and possibly 24,884 if price holds above 24,000; failure to maintain this level would shift focus back to 23,740 as the key support zone.
Commodities
Crude held soft after geopolitical headlines and resumed Iraqi flows. Gold traded sideways. Copper eased with weak risk appetite.
Corporate Event
GameStop reports post-market with an implied move of USD 1.82.
Upcoming US Data (Dec 9)
NFIB Small Business Optimism expected at 98.3.
JOLTS openings expected at 7.2mn.
Philip Papageorgiou – Market Analyst
X ex Twitter: PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.
Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.


British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.