



FTSE 100 analysis: UK retail sales and consumer confidence improve
An improvement in retail sales and consumer confidence is not providing relief for markets following a torrid week.
Share this:

FTSE 100 hits fresh 3-week low
The FTSE 100 is down 0.3% this morning and at fresh three week lows.
That comes after the hawkish Bank of England meeting yesterday. Interest rates were hiked for a 13th consecutive time, accelerating the increase to 50bps in an effort to tame inflation as the central bank has a tougher time than its European and US counterparts. That has taken UK rates to 5%, their highest level in 15 years, and markets currently project they could rise above 6% before the end of the year.
That puts the index on course to lose ground for a fifth consecutive session, marking a torrid week for UK markets. It is clear the fight against inflation is far from over and that we are still far away from the end of this tightening cycle – which will also increase the risks of a recession the longer it goes on. All of this is testing risk appetite in the market and setting the stage for a more challenging backdrop for equities as we approach the midway point of 2023.
We have flash PMIs out from France, Germany and the wider euro area out this morning before UK figures come out at 0930 BST. US PMIs will follow this afternoon at 0245 BST. Markets will be hoping for soft readings, as strong data would only add more fuel to the fire and support further tightening by central banks!
UK retail sales and consumer confidence improve
There is some positive news for UK markets to digest this morning.
UK retail sales grew 0.3% month-on-month in May and increased 0.1% when fuel was stripped out. That will be welcome news considering analysts had forecast a 0.2% drop (or a 0.3% fall excluding fuel). Good weather and bank holidays, including an extra one for the Jubilee, helped provide a boost. Still, sales were down 2.1% from the year before.
That is failing to provide support to retailers like ASOS, Next, Currys, AO World, Frasers Group, B&M and JD Sports this morning, which are all down 0.1% to 0.6%.
We also discovered that consumer confidence has hit a 17-month high, according to a report from GfK. It said sentiment rose three points to come in at minus 24 in June, better than the minus 26 forecast by economists. That suggests consumers are coping with the cost-of-living crisis, driven by persistently high inflation and rising interest rates, better than expected.
FTSE 100 analysis: Where next for the UK 100?
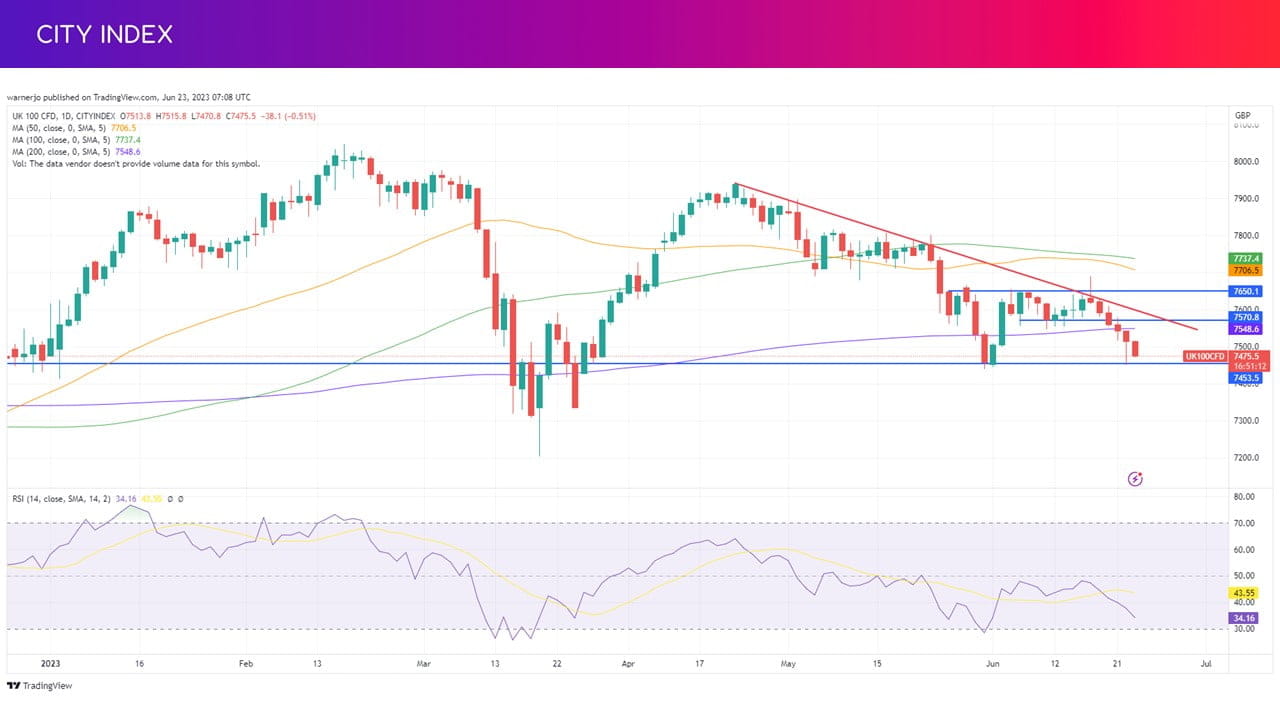
The UK 100, which tracks the FTSE 100, is at a fresh three-week low and continues to barrel toward the June-low of 7,452. Any slip below here brings the 2023-lows of 7,314 back into play. We can see the shorter-term moving averages are beginning to trend downward.
On the upside, the immediate job is to climb back above 7,573 after this failed to hold as a level of support alongside the 200-day moving average. It can then look to return back above the 7,650 ceiling that has held firm for the past month. The downtrend that can be traced back over the past two months remains in play and could limit upside potential.

Top UK stocks news
GSK is up 2.3% this morning after it said it has struck a confidential settlement with James Goetz without accepting any liability over litigation concerning Zantac. That means a trial that was due to start on July 24 will now be dismissed. ‘The settlement reflects the company's desire to avoid distraction related to protracted litigation in this case. GSK does not admit any liability in this settlement and will continue to vigorously defend itself based on the facts and the science in all other Zantac cases,’ said the pharmaceutical giant.
BP and Shell are both down 0.2% and following prices lower today, with Brent down 1.2%. We have seen the price of a barrel drop from over $76 at the start of the week to below $73.50 today, bruised by hawkish central bank commentary.
London-listed miners like Rio Tinto and Anglo American are down 0.4% and 1%, respectively, in reaction to lower prices today, with iron ore prices down over 2% this week. Jefferies warned the era of China driving demand for key metals like iron ore, copper and aluminium because of its urbanisation and industrialisation has ended as the world moves toward clean energy and decarbonisation. ‘China is more likely to be a headwind than a tailwind for demand over the next decade,’ Jefferies said.
Revolution Beauty Group released a surprise first quarter trading update this morning as it responded to efforts by major shareholder Boohoo, which owns a 26.6% stake, to change management at the company. Revolution Beauty shares have been suspended since last year and the company recently took action against its founder and former chief executive Adam Minto, alleging he broke his duties. But Boohoo wants to replace directors with its own nominees, which Revolution Beauty called ‘value-destructive, opportunistic and self-serving’ this morning. ‘The board of Revolution Beauty continues to be of the view that it ismuch better placed than the proposed boohoo candidates to deliver shareholder value,’ it said. Revolution Beauty said sales were up 60% and that margins improved in the first quarter, allowing it to deliver adjusted Ebitda of £3.5 million compared to a £7.4 million loss the year before. Boohoo is up 2.4% this morning.
Ocado shares are down 3.3% today at 549p, having popped over 30% yesterday following a report from The Times newspaper that said more than one Big Tech member, including Amazon, is interested in and considering bidding for the online grocer and automated warehouse maker. The report pointed toward a deal worth 800p per share, although this is not the first time Ocado has been linked with takeover news.
Bunzl has been downgraded to underperform at Jefferies, which has a 2,600p price target on the distributor. The stock is down 2.9% today at 2,943p.
HSBC downgraded several UK housebuilders following the latest interest rate rise, which will pressure demand as mortgage rates continue to climb. Persimmon, Barratt, Crest Nicholson and Taylor Wimpey were all downgraded to Hold and are trading 2.5% to 4% lower this morning while Berkeley Group was lowered to Reduce and is down 5.1%.
How to trade the FTSE 100
You can trade the FTSE 100 with City Index in just four easy steps:
- Open a City Index account, or log-in if you’re already a customer.
- Search for ‘UK 100’ you want in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Trading Account.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.

British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.