




Further Signs That The Dollar Could Be In For A Better Month
November has been off to a much better start for USD than October ended. Add seasonality to the Mix and DXY could be in for a positive close this month.
Share this:

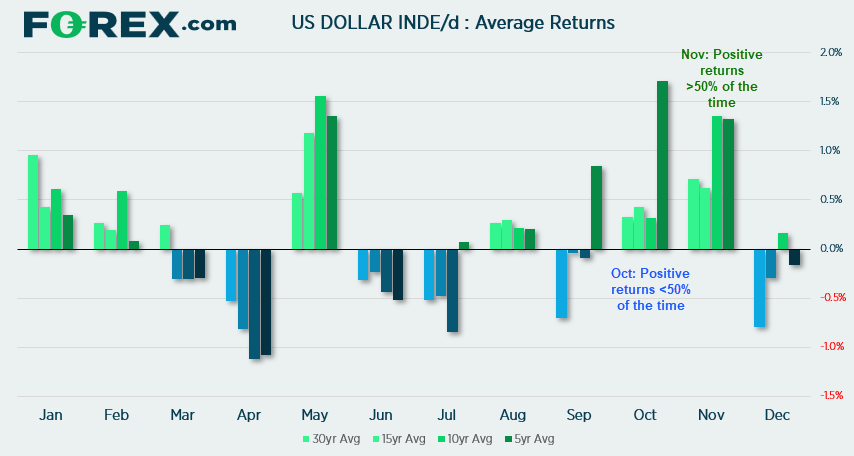
November has been off to a much better start for USD than October ended. Add seasonality to the Mix and DXY could be in for a positive close this month. This ties in nicely with Tuesday’s analysis, which showed bearish engulfing candles tend to provide bullish reactions on DXY. However, looking at seasonal data for DXY, things continue to look hopeful for the bull-camp in November.
- 63% of Novembers over the past 30 years have produced positive returns (highest of the 12 months)
- Average returns for 5, 10 and 15 years are also positive over 50% of the time (meaning average is not propped up by outliers)
- Variance of high-low volatility in November is the 3rd lowest of the year in November, whilst October is the 2nd highest (meaning the data set for November is more stable and less prone to outliers, unlike October).
What about October? If we were to focus on average returns, we could have expected October to perform well (which it clearly wasn’t, being the worst monthly close since January 2018). Yet it’s worth noting that DXY has closed lower nearly 57% of the time in October, and there’s no clear relationship between positive expectancy or positive returns over the past 5, 10 or 15 years sampled. This is unlike November, which has posted positive expectancy and positive returns on average over 5, 10, 15 and 30 years sampled.
With 17 trading days in the month left to go, it leaves plenty of time for markets to push DXY in either direction. Yet the stats appear promising for a bullish close none the less.
- DXY produced a small, bearish pinbar below 98 and around the 50 and 100-day eMA’s, leaving the potential for a pause in the move or a retracement.
- Bullish momentum leading up to 98 is strong, so an eventual break higher is anticipated.
- Bulls could look for a pullback / flag to form and enter on a potential dip or wait for a break above 98 to confirm trend resumption.
- Also keep an eye on AUD/USD and EUR/USD as they hover near key support levels (USD/CAD is also building a base above 1.3100).
What about December? We can see that average returns for DXY have been negative over the past 30, 15 and 5 years. But it’s also worth noting these periods are also bearish over 50% of the time. So, December doesn’t tend to fare so well as Santa’s rally gets underway.
November has been off to a much better start for USD than October ended. Add seasonality to the Mix and DXY could be in for a positive close this month. This ties in nicely with Tuesday’s analysis, which showed bearish engulfing candles tend to provide bullish reactions on DXY. However, looking at seasonal data for DXY, things continue to look hopeful for the bull-camp in November.
- 63% of Novembers over the past 30 years have produced positive returns (highest of the 12 months)
- Average returns for 5, 10 and 15 years are also positive over 50% of the time (meaning average is not propped up by outliers)
- Variance of high-low volatility in November is the 3rd lowest of the year in November, whilst October is the 2nd highest (meaning the data set for November is more stable and less prone to outliers, unlike October).
What about October? If we were to focus on average returns, we could have expected October to perform well (which it clearly wasn’t, being the worst monthly close since January 2018). Yet it’s worth noting that DXY has closed lower nearly 57% of the time in October, and there’s no clear relationship between positive expectancy or positive returns over the past 5, 10 or 15 years sampled. This is unlike November, which has posted positive expectancy and positive returns on average over 5, 10, 15 and 30 years sampled.
With 17 trading days in the month left to go, it leaves plenty of time for markets to push DXY in either direction. Yet the stats appear promising for a bullish close none the less.
- DXY produced a small, bearish pinbar below 98 and around the 50 and 100-day eMA’s, leaving the potential for a pause in the move or a retracement.
- Bullish momentum leading up to 98 is strong, so an eventual break higher is anticipated.
- Bulls could look for a pullback / flag to form and enter on a potential dip or wait for a break above 98 to confirm trend resumption.
- Also keep an eye on AUD/USD and EUR/USD as they hover near key support levels (USD/CAD is also building a base above 1.3100).
What about December? We can see that average returns for DXY have been negative over the past 30, 15 and 5 years. But it’s also worth noting these periods are also bearish over 50% of the time. So, December doesn’t tend to fare so well as Santa’s rally gets underway.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.