



GBPUSD continues to gain momentum
A summary of key U.S. eco data and an FX pair mover of the week.
Share this:

Increased economic uncertainty has brought added volatility into global forex markets. Here is a look at key U.S. economic data over the past week that helped move the majors.
Personal Income declined 1.1% on month in June (-0.6% expected), compared to a revised -4.4% in May. Personal Spending increased 5.6% on month in June (+5.2% expected), compared to a revised +8.5% in May.
Market News International's Chicago Purchasing Managers' Index jumped to 51.9 on month in July (44.0 expected), from 36.6 in June, a level last reached in mid-2019.
The University of Michigan's Consumer Sentiment Index slipped to 72.5 on month in the July final reading (72.9 expected), from 73.2 in the July preliminary reading.
U.S. GDP dropped 32.9% on quarter in the second quarter advanced reading (-34.5% expected), from -5.0% in the first quarter third reading, marking a record low.
Personal Consumption tumbled 34.6% on quarter in the second quarter advanced reading (-34.5% expected), from a revised -6.9% in the first quarter third reading, also marking an all-time low.
Initial Jobless Claims rose to 1,434K for the week ending July 25th (1,445K expected), from a revised 1,422K in the prior week.
Continuing Claims increased to 17,018K for the week ending July 18th (16,200K expected), from a revised 16,151K in the week before.
The Bloomberg Consumer Comfort Index slipped to 44.3 for the week ending July 26th, from 44.7 in the previous week.
The Mortgage Bankers Association's Mortgage Applications declined 0.8% for the week ending July 24th, from +4.1% in the previous week.
Wholesale Inventories fell 2.0% on month in the June preliminary reading (-0.5% expected), compared to -1.2% in the May final reading.
Pending Homes Sales rose 16.6% on month in June (+15.0% expected), compared to a record high of +44.3% in May.
The Federal Reserve kept the federal funds target rate at 0.00% to 0.25%, as expected.
The Conference Board's Consumer Confidence Index declined to 92.6 on month in July (95.0 expected), from a revised 98.3 in June. Durable Goods Orders increased 7.3% on month in the June preliminary readings (+6.9% expected), compared to a revised +15.1% in the May final reading.
Looking at the performance of forex major pairs over the last 5 trading days, the USD was under pressure against all its major pairs. The biggest gainers of the week were the GBP (+2.7%) and the EUR (+1.53%) while the CAD was the weakest against the USD. Here is a look at this weeks big gainer, the GBP/USD from a technical perspective.
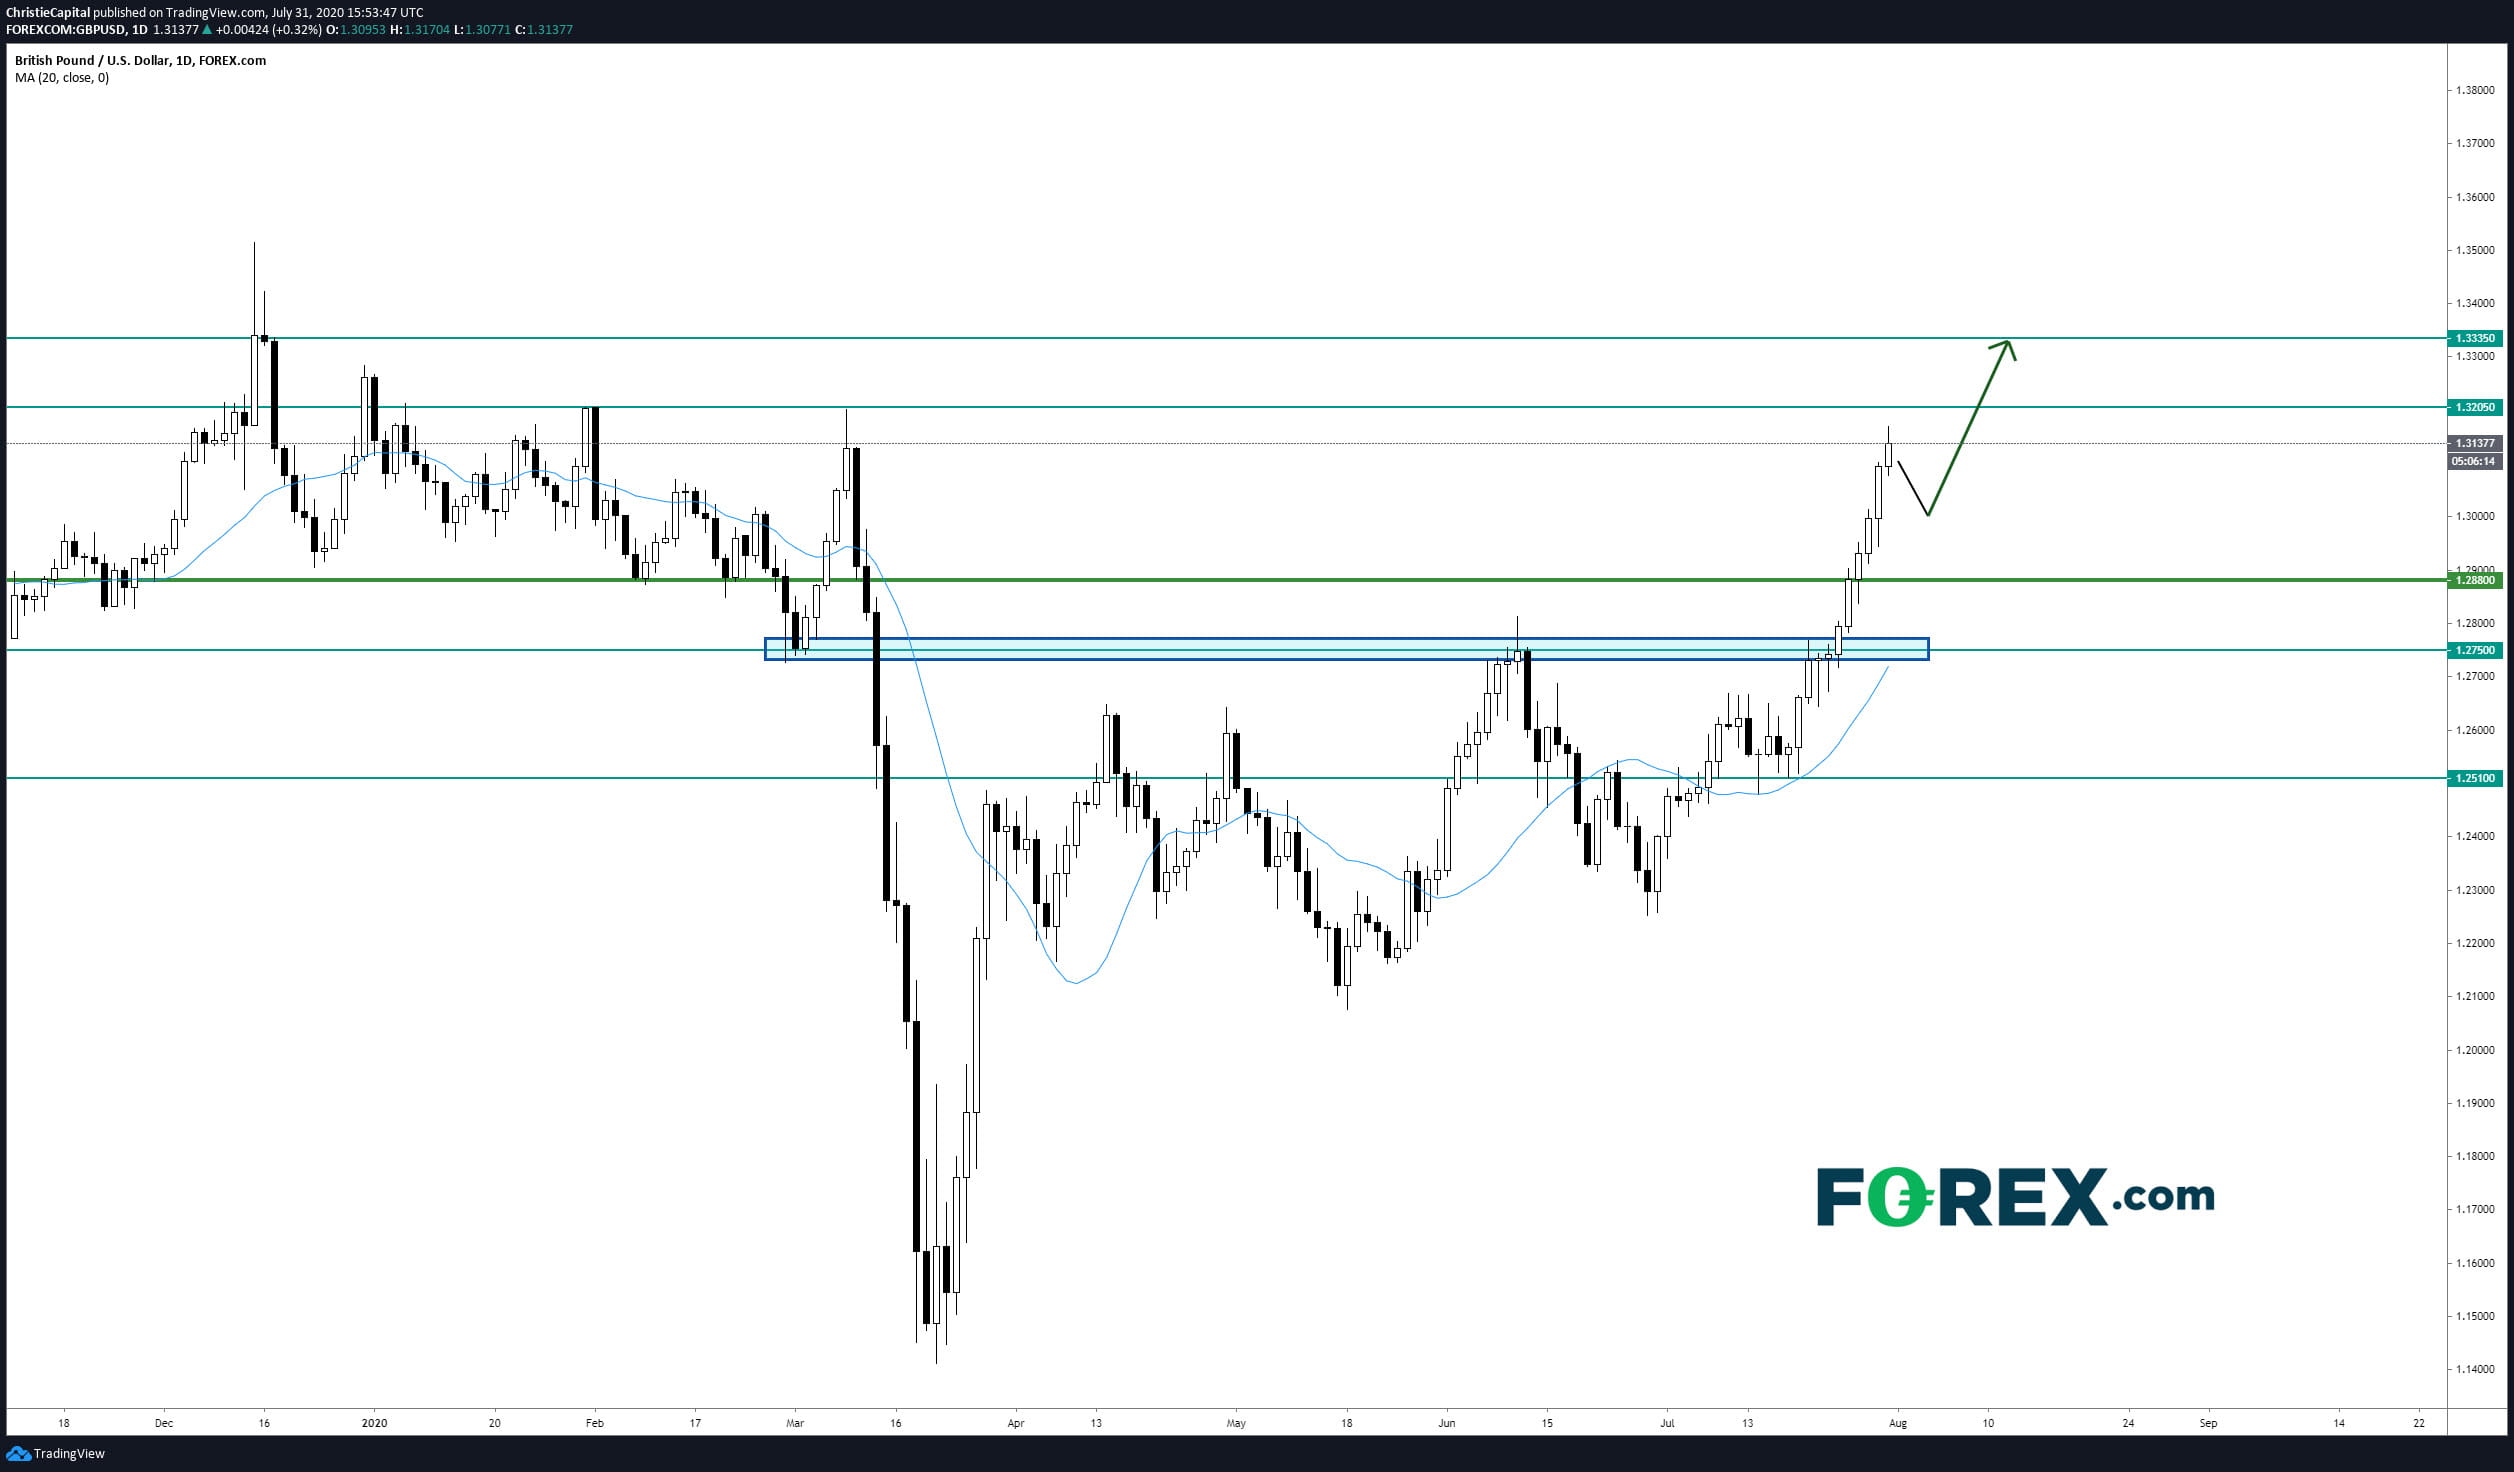
The GBP/USD continues to gain momentum after breaking above key resistance at the 1.275 level back on July 24th. The pair is approaching a new level of resistance near 1.3025. A pullback is warranted after the impressive move the pair has been on however a surge past 1.3205 without looking back is still possible. A break below 1.288 support would cal for a test of the 20-day moving average near the 1.27 area.
Source: GAIN Capital, TradingView
Have a great weekend.
Personal Income declined 1.1% on month in June (-0.6% expected), compared to a revised -4.4% in May. Personal Spending increased 5.6% on month in June (+5.2% expected), compared to a revised +8.5% in May.
Market News International's Chicago Purchasing Managers' Index jumped to 51.9 on month in July (44.0 expected), from 36.6 in June, a level last reached in mid-2019.
The University of Michigan's Consumer Sentiment Index slipped to 72.5 on month in the July final reading (72.9 expected), from 73.2 in the July preliminary reading.
U.S. GDP dropped 32.9% on quarter in the second quarter advanced reading (-34.5% expected), from -5.0% in the first quarter third reading, marking a record low.
Personal Consumption tumbled 34.6% on quarter in the second quarter advanced reading (-34.5% expected), from a revised -6.9% in the first quarter third reading, also marking an all-time low.
Initial Jobless Claims rose to 1,434K for the week ending July 25th (1,445K expected), from a revised 1,422K in the prior week.
Continuing Claims increased to 17,018K for the week ending July 18th (16,200K expected), from a revised 16,151K in the week before.
The Bloomberg Consumer Comfort Index slipped to 44.3 for the week ending July 26th, from 44.7 in the previous week.
The Mortgage Bankers Association's Mortgage Applications declined 0.8% for the week ending July 24th, from +4.1% in the previous week.
Wholesale Inventories fell 2.0% on month in the June preliminary reading (-0.5% expected), compared to -1.2% in the May final reading.
Pending Homes Sales rose 16.6% on month in June (+15.0% expected), compared to a record high of +44.3% in May.
The Federal Reserve kept the federal funds target rate at 0.00% to 0.25%, as expected.
The Conference Board's Consumer Confidence Index declined to 92.6 on month in July (95.0 expected), from a revised 98.3 in June. Durable Goods Orders increased 7.3% on month in the June preliminary readings (+6.9% expected), compared to a revised +15.1% in the May final reading.
Looking at the performance of forex major pairs over the last 5 trading days, the USD was under pressure against all its major pairs. The biggest gainers of the week were the GBP (+2.7%) and the EUR (+1.53%) while the CAD was the weakest against the USD. Here is a look at this weeks big gainer, the GBP/USD from a technical perspective.
The GBP/USD continues to gain momentum after breaking above key resistance at the 1.275 level back on July 24th. The pair is approaching a new level of resistance near 1.3025. A pullback is warranted after the impressive move the pair has been on however a surge past 1.3205 without looking back is still possible. A break below 1.288 support would cal for a test of the 20-day moving average near the 1.27 area.
Source: GAIN Capital, TradingView
Have a great weekend.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.
Canadian Dollar Technical Outlook: USD/CAD Seven-Day Rally Tests Major Resistance 9 29 2026
USD/CAD is pressing into a major technical barrier after an extended advance, raising the risk for price inflection as momentum stretches.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.