




Gold vulnerable as upside risks for US yields build
US benchmark bond yields look like they may have bottomed in the near-term, an outcome that may generate additional headwinds for gold at time when it’s already struggling.
Share this:

- The corrective move in US yields appears like it may run its course, according to recent price action
- Potential debt downgrades, soft longer-dated US Treasury auctions suggests risks for yields may be higher in the near-term
- Higher real and nominal bond yields would normally be negative for gold prices.
Have US benchmark bond yields bottomed?
US benchmark bond yields look like they may have bottomed in the near-term, an outcome that may generate additional headwinds for gold at time when it’s already struggling.
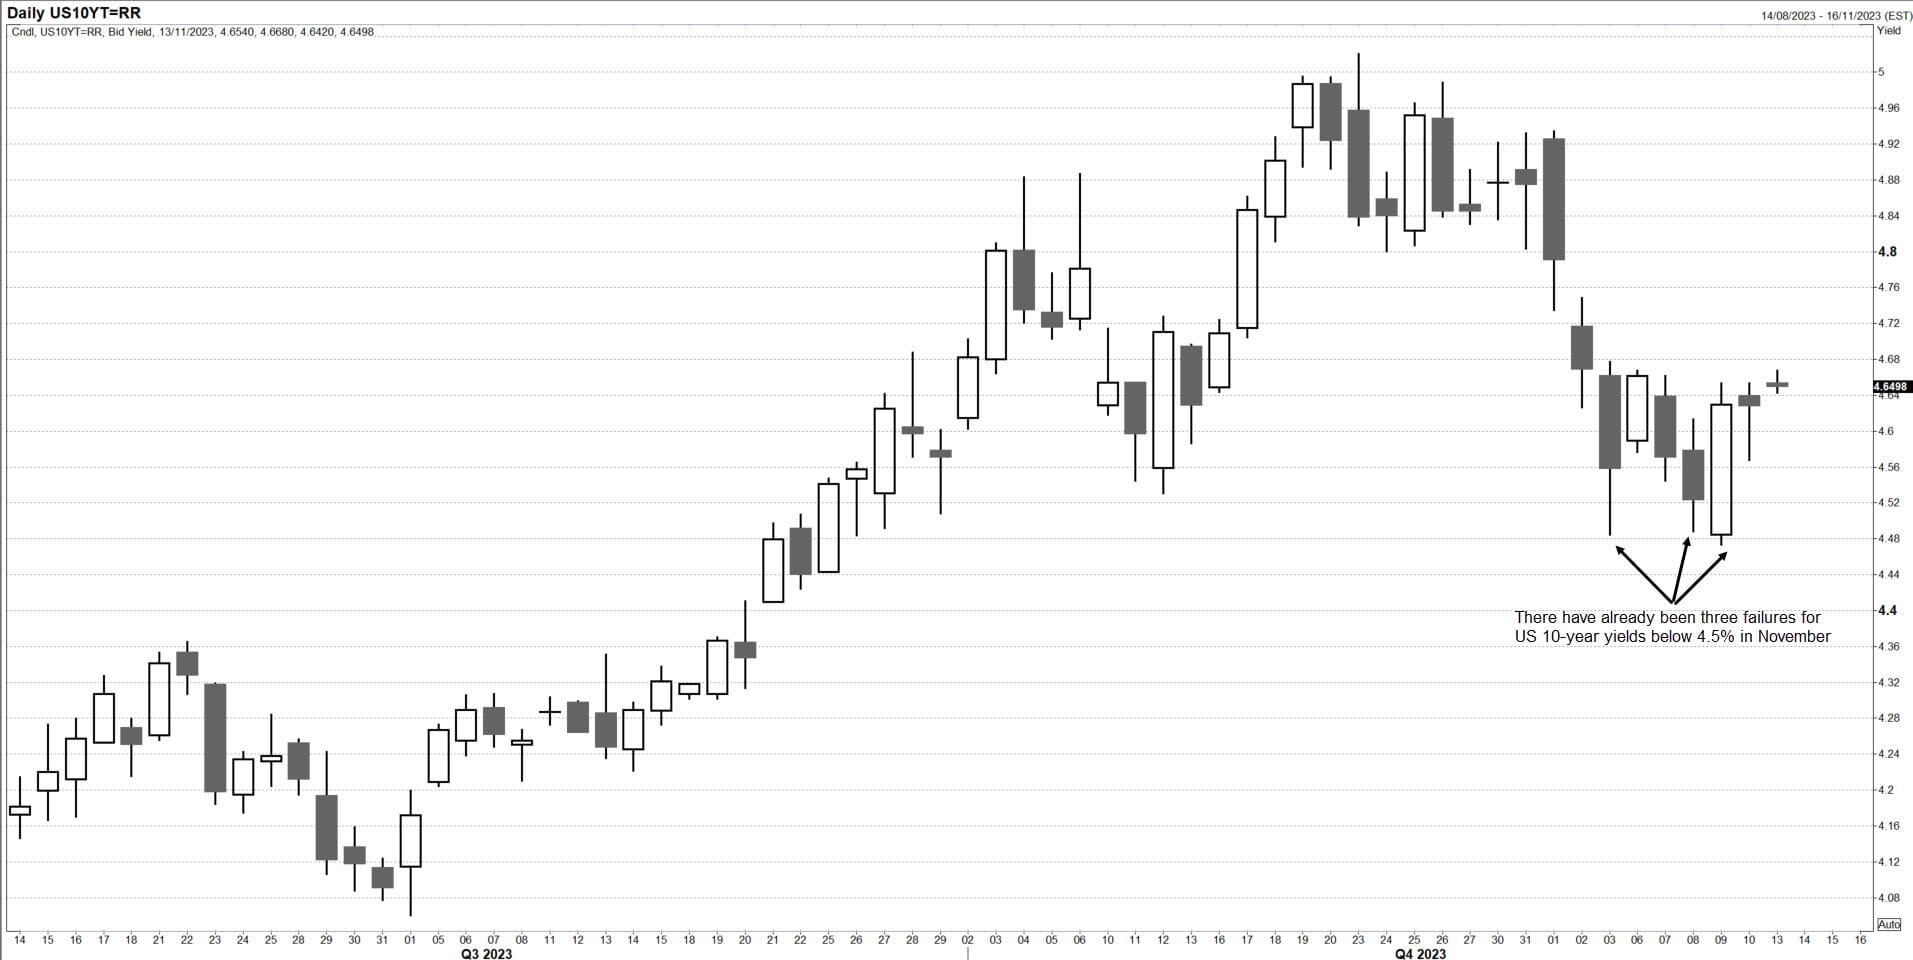
As can be seen on the daily candlestick chart below, after a precipitous drop in late September, US 10-year note yields have fallen below 4.5% on three separate occasions in November but have never managed to stay there, snapping higher on each occasion.
While technical analysis on yields is not widely accepted, it’s hard not to notice the bullish engulfing candle that occurred last Thursday, corresponding with what was widely regarded as being one of the weakest 30-year Treasury auctions on record. The 10-year note auction earlier in the week wasn’t much better. Moody’s decided to rub salt into the wounds on Friday, putting the US sovereign credit on watch for a potential downgrade.
When you combine the price action and fundamentals together, it suggests yields may need to increase further to satisfactorily compensate buyers for the additional risk they are taking on during this delicate moment for the US fiscal trajectory.
Gold vulnerable to higher yields
For a non-yielding asset such as gold, the prospect of higher yields may amplify near-term downside risks at time when it’s already struggling on the shorter timeframe charts. Having failed to hold above $2000 in the early stages of the conflict between Israel and Hamas, gold has been grinding lower over recent weeks, leaving it sandwiched between downtrend resistance and horizontal support.
In the advent that US yields do push meaningfully higher, it will likely drag real, inflation-adjusted benchmark US yields higher with it, creating the kind of conditions that could easily see gold break to the downside, opening the door for a potential push back towards support located just above $1900. If the downside break does occur, it would allow for a tight stop to be placed above $1933 for protection against a false break/reversal.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.