



Market Brief BoE Dovish Drags Pound Lower
A summary of news and snapshot of moves ahead of the US session.
Share this:

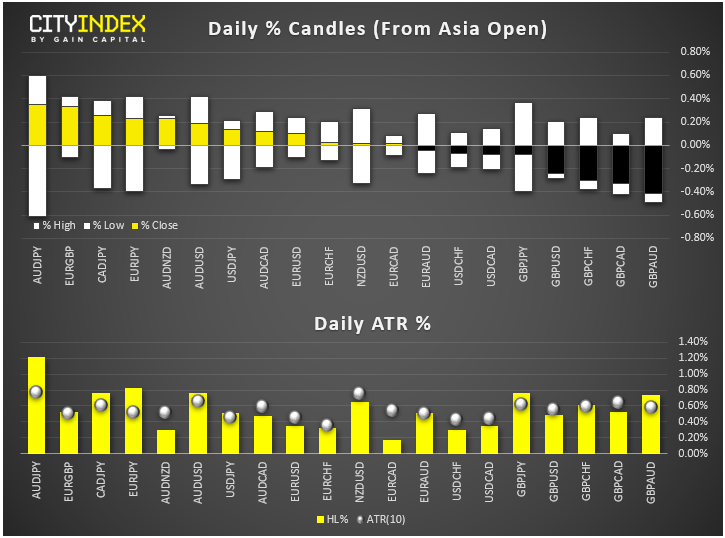
- At midday in London, the GBP was the weakest and AUD was the strongest.
View our guide on how to interpret the FX Dashboard
- The Bank of England decided to keep policy unchanged on both QE and rates fronts, but the fact there were two dissenters (SAUNDERS and HASKEL) who unexpectedly voted for 0.25% rate cut, this caused the pound to wobble a little. These MPC members argued that stimulus was needed now because recent data suggests labour market is turning and they see raised downside risks from global economy. The BoE’s inflation forecasts for the next three years have all been revised lower, with prices in one years’ time now seen at 1.51% compared with 1.90% in the August estimate. The Bank has also revised its growth forecasts lower, with GDP likely to be 1% lower by the end of 2022 than its August forecasts.
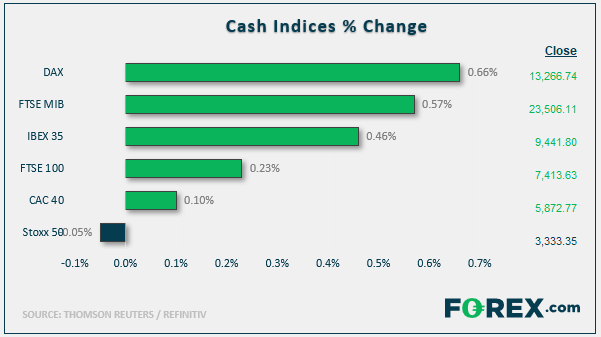
- Stocks in Europe and risk-sensitive currency pairs (USD/JPY and AUD/USD etc) all rose, while US index futures suggested we will see new record highs today. Sentiment was once again boosted by growing optimism over a US-China trade deal. This time, Reuters reported that China says it has agreed with the US to cancel existing tariffs in different phases.
- In today’s macro news:
- Italian Retail Sales +0.7% m/m vs. +0.3% expected
- German Industrial Production -0.6% m/m vs. -0.3% expected
- US unemployment claims only newsworthy data expected from North America

- Stock highlights by colleague Ken Odeluga:
- Sainsbury shares trade flattish though have dropped a fair amount off the day’s highs. The grocer’s adjusted profits missed forecasts.
- Tate & Lyle surged 7% following a beat on food & beverage products.
- Marks & Spencer bounces back hard after a weak showing on Wednesday’s poor H1 report. It rose 7% after an upgrade by SocGen showed some investors still see fair chances of a turnaround
- Virgin Money also rose strongly, lifting a clutch of rival challenger banks in its wake as consolidation talk continues to sweep the sector
- Qualcomm beat quarterly earnings forecasts, leading the stock to outperform overnight and ahead of Thursday's Wall Street open. The global semiconductor sector is also seeing a lift.
- At midday in London, the GBP was the weakest and AUD was the strongest.
View our guide on how to interpret the FX Dashboard
- The Bank of England decided to keep policy unchanged on both QE and rates fronts, but the fact there were two dissenters (SAUNDERS and HASKEL) who unexpectedly voted for 0.25% rate cut, this caused the pound to wobble a little. These MPC members argued that stimulus was needed now because recent data suggests labour market is turning and they see raised downside risks from global economy. The BoE’s inflation forecasts for the next three years have all been revised lower, with prices in one years’ time now seen at 1.51% compared with 1.90% in the August estimate. The Bank has also revised its growth forecasts lower, with GDP likely to be 1% lower by the end of 2022 than its August forecasts.
- Stocks in Europe and risk-sensitive currency pairs (USD/JPY and AUD/USD etc) all rose, while US index futures suggested we will see new record highs today. Sentiment was once again boosted by growing optimism over a US-China trade deal. This time, Reuters reported that China says it has agreed with the US to cancel existing tariffs in different phases.
- In today’s macro news:
- Italian Retail Sales +0.7% m/m vs. +0.3% expected
- German Industrial Production -0.6% m/m vs. -0.3% expected
- US unemployment claims only newsworthy data expected from North America
- Stock highlights by colleague Ken Odeluga:
- Sainsbury shares trade flattish though have dropped a fair amount off the day’s highs. The grocer’s adjusted profits missed forecasts.
- Tate & Lyle surged 7% following a beat on food & beverage products.
- Marks & Spencer bounces back hard after a weak showing on Wednesday’s poor H1 report. It rose 7% after an upgrade by SocGen showed some investors still see fair chances of a turnaround
- Virgin Money also rose strongly, lifting a clutch of rival challenger banks in its wake as consolidation talk continues to sweep the sector
- Qualcomm beat quarterly earnings forecasts, leading the stock to outperform overnight and ahead of Thursday's Wall Street open. The global semiconductor sector is also seeing a lift.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.