



Market Brief China wants US tariffs removed before further farm goods purchases
A summary of news and snapshot of moves ahead of the US session.
Share this:

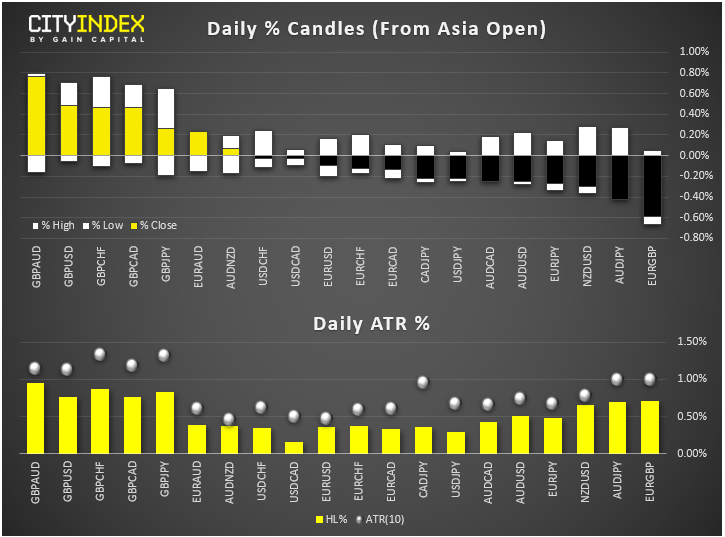
- At midday in London, GBP was the strongest and AUD among the weakest. Gold was trading higher, copper and oil lower. Stocks were coming off their best levels after futures rose earlier in the day.
- GBP was holding steady following recent sharp gains, undermining the FTSE. The EU's chief negotiator Michel Barnier, who had previously said "big gaps" remained between the UK and EU, has now said a Brexit deal could be struck as early as this week. However, he has warned it was "time to turn good intentions into legal text". The UK and EU officials are set to meet at a summit on Thursday and Friday. This meeting could determine whether UK is headed for a no-deal Brexit at the end of this month.
- European stocks were sharply higher earlier but gave up some of those gains after Bloomberg reported, citing people familiar with the matter, that China will struggle to buy $50 billion of US farm goods annually unless Washington removes retaliatory tariffs so they can afford it. The focus will turn to US Q3 earnings reporting session, which kickstarts this week. Lots of bank earnings will come in over the next few days, including Citigroup, JP Morgan, Goldman Sachs and Wells Fargo today and Bank of American tomorrow. HERE is my colleague Ken Odeluga’s bank earnings preview.
- Data highlights
- The German ZEW Survey revealed the “Current Situation” index deteriorated more than expected (to -25.3 vs. -19.9 in September and -23.6 expected), while the “Expectations” index deteriorated less than expected (-22.8 vs -22.5 last and -26.4 expected).
- Supported by raised Brexit optimism, the GBP barely reacted to news UK wages grew less than forecast at 3.8% 3m/y vs. 4.0% eyed or the fact the unemployment rate ticked higher to 3.9% y/y from 3.8% last. Sterling did ease off the highs but was still retaining most of its gains.
- Overnight, Chinese CPI inflation came in at +3.0% y/y, above 2.9% expected and 2.8% last. However, PPI measure of inflation declined 1.2% y/y as expected (vs. -0.8% prior). In other news, US President Donald Trump imposed steel tariffs on Turkey Monday night and threatened there could be more to come. This comes after Turkey’s military movement into Syria. The USD/TRY exchange rate was relatively stable at around 5.900

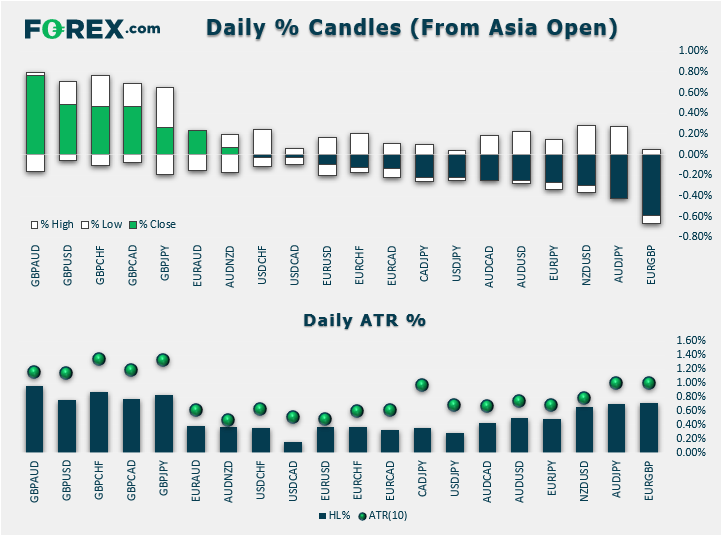
- At midday in London, GBP was the strongest and AUD among the weakest. Gold was trading higher, copper and oil lower. Stocks were coming off their best levels after futures rose earlier in the day.
- GBP was holding steady following recent sharp gains, undermining the FTSE. The EU's chief negotiator Michel Barnier, who had previously said "big gaps" remained between the UK and EU, has now said a Brexit deal could be struck as early as this week. However, he has warned it was "time to turn good intentions into legal text". The UK and EU officials are set to meet at a summit on Thursday and Friday. This meeting could determine whether UK is headed for a no-deal Brexit at the end of this month.
- European stocks were sharply higher earlier but gave up some of those gains after Bloomberg reported, citing people familiar with the matter, that China will struggle to buy $50 billion of US farm goods annually unless Washington removes retaliatory tariffs so they can afford it. The focus will turn to US Q3 earnings reporting session, which kickstarts this week. Lots of bank earnings will come in over the next few days, including Citigroup, JP Morgan, Goldman Sachs and Wells Fargo today and Bank of American tomorrow.
- Data highlights
- The German ZEW Survey revealed the “Current Situation” index deteriorated more than expected (to -25.3 vs. -19.9 in September and -23.6 expected), while the “Expectations” index deteriorated less than expected (-22.8 vs -22.5 last and -26.4 expected).
- Supported by raised Brexit optimism, the GBP barely reacted to news UK wages grew less than forecast at 3.8% 3m/y vs. 4.0% eyed or the fact the unemployment rate ticked higher to 3.9% y/y from 3.8% last. Sterling did ease off the highs but was still retaining most of its gains.
- Overnight, Chinese CPI inflation came in at +3.0% y/y, above 2.9% expected and 2.8% last. However, PPI measure of inflation declined 1.2% y/y as expected (vs. -0.8% prior). In other news, US President Donald Trump imposed steel tariffs on Turkey Monday night and threatened there could be more to come. This comes after Turkey’s military movement into Syria. The USD/TRY exchange rate was relatively stable at around 5.900
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

US Dollar Price Action Setups: USD/JPY, USD/CAD, EUR/USD, GBP/USD, Gold
The US Dollar has rallied since last week’s rate hike and USD/JPY remains a massive driver across the USD complex.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.