



Market Brief Dollar Extends Post Fed Slide
A summary of news and snapshot of moves ahead of the US session.
Share this:

- At midday in London, the GBP and JPY were among the strongest while the AUD and USD were among the weakest.

View our guide on how to interpret the FX Dashboard
- The US dollar continued to sell-off following the Fed’s rate cut last night. Although the central bank signalled a pause in the cutting cycle, Chairman Jay Powell suggested the Fed is nowhere near hiking: “We've just touched 2% core inflation to pick one measure, and then we've fallen back. So I think we would need to see a really significant move up in inflation that's persistent before we would even consider raising rates to address inflation concerns."
- Bank of Japan decided to keep monetary policy unchanged and the yen strengthened as some had expected it to ease policy. But Governor Kuroda said Japan had more room than Europe to lower the already negative interest rates if it needed to.
- China’s manufacturing sector shrank for the sixth successive month in October, according to the latest PMI figures. Activity slowed down on weaker output and new orders, suggesting lingering challenges as growth in the world’s second-largest economy slowed to a 30-year low in the third quarter. The PMI dropped to 49.3 from 49.8 below 49.8 expected. What’s more, the Non-manufacturing PMI also tumbled sharply to 52.8 from 53.6 previously.
- Hong Kong’s economy plunged into a recession after months of violent protests took its toll on growth.
- Eurozone data was mixed: third quarter GDP came in at +0.2% vs. +0.1% q/q expected, but on a year-over-year basis GDP was in line at 1.1%, down from 1.2% previously. Eurozone CPI printed +0.7% in October as expected, down from +0.9% previously, but core CPI was a touch higher at +1.1% vs. 1.0% expected and last. German Retail Sales rose just 0.1% m/m vs. 0.3% expected.

- Stocks fell sharply in Europe this morning despite the S&P 500 rallying to a new record yesterday. Sentiment was hurt here by generally weaker European earnings, news of a recession in Hong Kong, soft Chinese data and as fresh doubts emerged over a long-term US-China trade, according to a Bloomberg report. However, the major indices were at or near key support levels. Could they rebound?
- Among commodities, Gold rallied as it was supported by the weakness in stocks and the US dollar, while crude oil continued to slide amid ongoing concerns over weaker demand.

- At midday in London, the GBP and JPY were among the strongest while the AUD and USD were among the weakest.

View our guide on how to interpret the FX Dashboard
- The US dollar continued to sell-off following the Fed’s rate cut last night. Although the central bank signalled a pause in the cutting cycle, Chairman Jay Powell suggested the Fed is nowhere near hiking: “We've just touched 2% core inflation to pick one measure, and then we've fallen back. So I think we would need to see a really significant move up in inflation that's persistent before we would even consider raising rates to address inflation concerns."
- Bank of Japan decided to keep monetary policy unchanged and the yen strengthened as some had expected it to ease policy. But Governor Kuroda said Japan had more room than Europe to lower the already negative interest rates if it needed to.
- China’s manufacturing sector shrank for the sixth successive month in October, according to the latest PMI figures. Activity slowed down on weaker output and new orders, suggesting lingering challenges as growth in the world’s second-largest economy slowed to a 30-year low in the third quarter. The PMI dropped to 49.3 from 49.8 below 49.8 expected. What’s more, the Non-manufacturing PMI also tumbled sharply to 52.8 from 53.6 previously.
- Hong Kong’s economy plunged into a recession after months of violent protests took its toll on growth.
- Eurozone data was mixed: third quarter GDP came in at +0.2% vs. +0.1% q/q expected, but on a year-over-year basis GDP was in line at 1.1%, down from 1.2% previously. Eurozone CPI printed +0.7% in October as expected, down from +0.9% previously, but core CPI was a touch higher at +1.1% vs. 1.0% expected and last. German Retail Sales rose just 0.1% m/m vs. 0.3% expected.
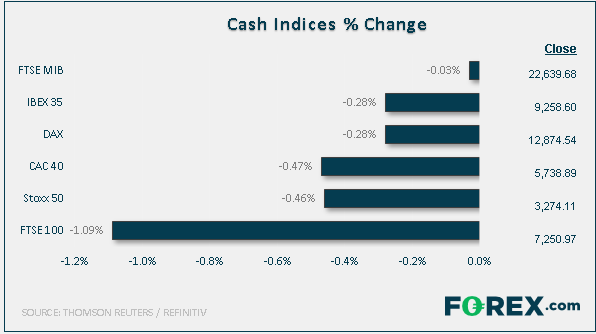
- Stocks fell sharply in Europe this morning despite the S&P 500 rallying to a new record yesterday. Sentiment was hurt here by generally weaker European earnings, news of a recession in Hong Kong, soft Chinese data and as fresh doubts emerged over a long-term US-China trade, according to a Bloomberg report. However, the major indices were at or near key support levels. Could they rebound?
- Among commodities, Gold rallied as it was supported by the weakness in stocks and the US dollar, while crude oil continued to slide amid ongoing concerns over weaker demand.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.