





Market Brief Pound extends drop despite CPI beat
A summary of news and snapshot of moves ahead of the US session.
Share this:

- Market update at 10:45 GMT: In FX, GBP remained the weakest major currency for the second straight day, while AUD and CHF were among the top risers. Stocks ended mixed in Asia, but were higher in Europe following Tuesday’s hiccup – expect the German DAX index. Gold and silver rose while copper and oil prices fell.

- UK inflation was slightly ahead of expectations but this failed to provide an immediate boost for the pound, which remained under pressure following heavy losses the day before amid renewed concerns over a hard Brexit, after Prime Minister Boris Johnson ruled out an extension for the Brexit transition period beyond end 2020. This gives the UK and EU 11 months to try and get a trade deal sorted out, which looks like tall order. Anyway headline UK CPI in Nov: 0.2% m/m as expected while on a y/y/ basis CPI beat at 1.5% vs. 1.4%. Core CPU was 0.2% m/m and 1.7% y/y, both in line with forecasts.
- USD failed to respond to President Donald Trump urging the Fed to use expansionary monetary policy to boost exports.
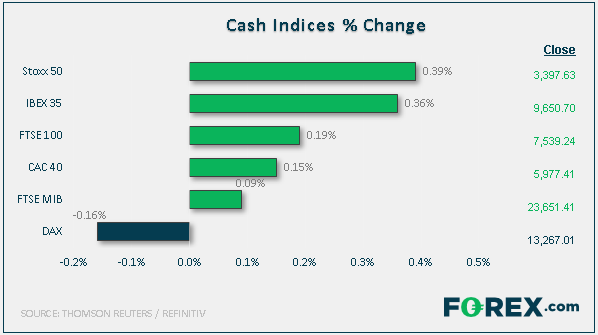
- Stocks rose after Tuesday’s slight falls in Europe. People’s Bank of China injected $29 billion into the financial system. Ratings agencies S&P and Fitch both revised upward their assessment of the UK’s credit outlook following Boris Johnson’s majority win last week. German IFO improved from 95.1 to 96.3, rising to a six-month high. Ifo economist Klaus Wohlrabe said Germany’s industrial sector is still in recession and will take a while to get out of it. But the German economy is heading into 2020 with more confidence.
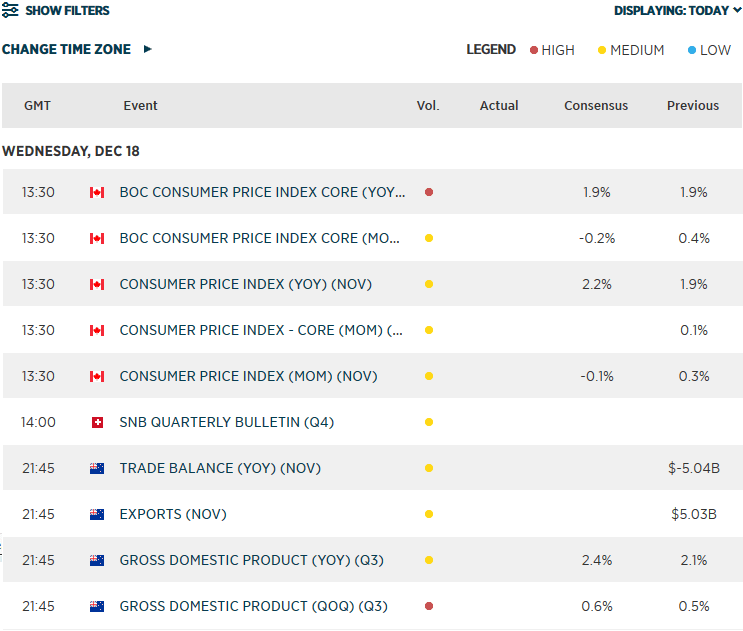
- Coming up:
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
- Market update at 10:45 GMT: In FX, GBP remained the weakest major currency for the second straight day, while AUD and CHF were among the top risers. Stocks ended mixed in Asia, but were higher in Europe following Tuesday’s hiccup – expect the German DAX index. Gold and silver rose while copper and oil prices fell.
- UK inflation was slightly ahead of expectations but this failed to provide an immediate boost for the pound, which remained under pressure following heavy losses the day before amid renewed concerns over a hard Brexit, after Prime Minister Boris Johnson ruled out an extension for the Brexit transition period beyond end 2020. This gives the UK and EU 11 months to try and get a trade deal sorted out, which looks like tall order. Anyway headline UK CPI in Nov: 0.2% m/m as expected while on a y/y/ basis CPI beat at 1.5% vs. 1.4%. Core CPU was 0.2% m/m and 1.7% y/y, both in line with forecasts.
- USD failed to respond to President Donald Trump urging the Fed to use expansionary monetary policy to boost exports.
- Stocks rose after Tuesday’s slight falls in Europe. People’s Bank of China injected $29 billion into the financial system. Ratings agencies S&P and Fitch both revised upward their assessment of the UK’s credit outlook following Boris Johnson’s majority win last week. German IFO improved from 95.1 to 96.3, rising to a six-month high. Ifo economist Klaus Wohlrabe said Germany’s industrial sector is still in recession and will take a while to get out of it. But the German economy is heading into 2020 with more confidence.
- Coming up:
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
View our guide on how to interpret the FX Dashboard
(CI) View our guide on how to interpret the FX Dashboard
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.