





Market Brief Risk Aversion Prevails
A summary of news and snapshot of moves ahead of the US session.
Share this:

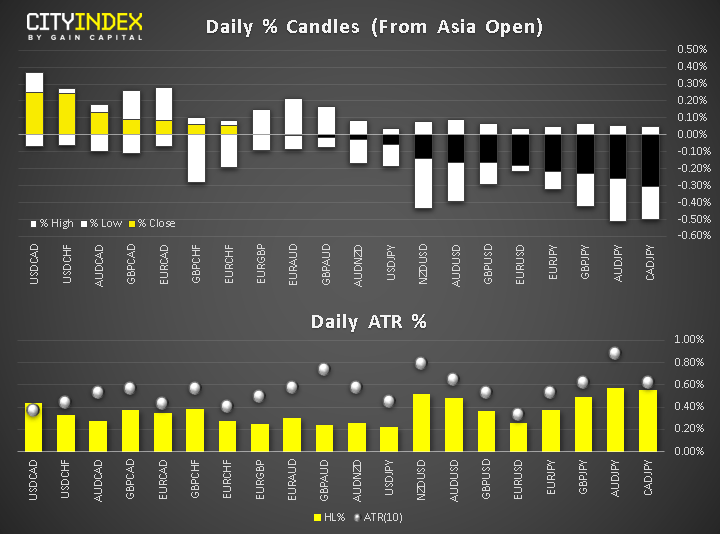
- Risk aversion has crept up, weighing on all yen crosses except the USD/JPY. This means that the US dollar is the strongest currency today with all other majors also being down against the buck. The weakest currency was the Canadian dollar:
View our guide on how to interpret the FX Dashboard
- Doubts continue to grow over the ability of the US and China to agree a phase one trade deal. The latest concern is that the decision by the US Senate to pass a bill supporting the pro-Democracy protesters in Hong Kong will only aggravate an already fragile US–China relationship. Indeed, China has voiced displeasure and raised warning of retaliation. Separately, a couple of days ago, Trump had threatened of further tariff if no deal is done.
- FX market participants are looking forward to Canadian CPI (13:30 GMT) and FOMC meeting minutes (19:00 GMT).
- Canada CPI expected at 1.9% y/y and 0.3% y/y for core CPI. If the data disappoints, this could very well increase the pressure on the CAD as speculation grows over a possible rate cut by the Bank of Canada.
- FOMC minutes may not contain much in the way of new information. Fed Chair and several officials have guided market participants towards a “wait and see” approach in terms of monetary policy after three rounds of interest rate cuts.
- In commodities, gold and silver turned lower as earlier gains evaporated with an appreciating US dollar. Meanwhile crude oil rebounded after an extended drop in the previous session. Official EIA crude oil inventories data at due at 15:30 today.
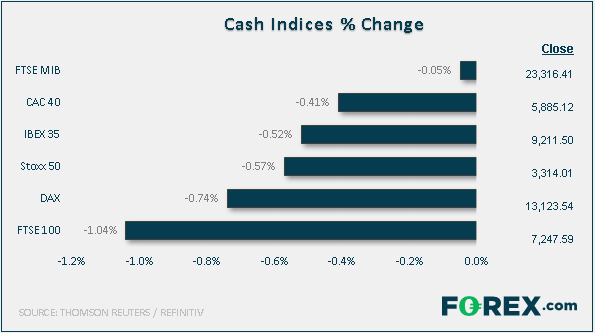
- European stocks were lower with all European sectors in the red though energy fell the most, led by a 3.2% tumble by Equinor. US index futures pointed to a subdued start on Wall Street.
- Stocks on the move, courtesy of my colleague Ken Odeluga:
- Swedbank drops 3.5% as it becomes the latest Nordic lender to come unstuck due to Russia-related corruption allegations
- Shell, BP and Total dragged European indices lower, thanks to yesterday’s sizeable drop in oil prices. Equinor, formerly known as Statoil, said current output from a key North Sea field exceeded 300,000bbl/day, but that's lower than expected.
- HSBC, the Hong Kong-exposed bank, fell 0.9%, dragging the FTSE 100, on which the stock is the heaviest single weight.
- Kingfisher also weighing the FTSE down with a big drop on shares after a quarterly sales miss
- Target, the American retailer, may lift this week's gloom in the sector after reporting higher than forecast Q3 earnings, key sales and Q4 guidance, lifting the stock 8% in pre-market trade. Victoria's Secret operator L Brands reports after tonight's U.S. close.
- Risk aversion has crept up, weighing on all yen crosses except the USD/JPY. This means that the US dollar is the strongest currency today with all other majors also being down against the buck. The weakest currency was the Canadian dollar:
View our guide on how to interpret the FX Dashboard
- Doubts continue to grow over the ability of the US and China to agree a phase one trade deal. The latest concern is that the decision by the US Senate to pass a bill supporting the pro-Democracy protesters in Hong Kong will only aggravate an already fragile US–China relationship. Indeed, China has voiced displeasure and raised warning of retaliation. Separately, a couple of days ago, Trump had threatened of further tariff if no deal is done.
- FX market participants are looking forward to Canadian CPI (13:30 GMT) and FOMC meeting minutes (19:00 GMT).
- Canada CPI expected at 1.9% y/y and 0.3% y/y for core CPI. If the data disappoints, this could very well increase the pressure on the CAD as speculation grows over a possible rate cut by the Bank of Canada.
- FOMC minutes may not contain much in the way of new information. Fed Chair and several officials have guided market participants towards a “wait and see” approach in terms of monetary policy after three rounds of interest rate cuts.
- In commodities, gold and silver turned lower as earlier gains evaporated with an appreciating US dollar. Meanwhile crude oil rebounded after an extended drop in the previous session. Official EIA crude oil inventories data at due at 15:30 today.
- European stocks were lower with all European sectors in the red though energy fell the most, led by a 3.2% tumble by Equinor. US index futures pointed to a subdued start on Wall Street.
- Stocks on the move, courtesy of my colleague Ken Odeluga:
- Swedbank drops 3.5% as it becomes the latest Nordic lender to come unstuck due to Russia-related corruption allegations
- Shell, BP and Total dragged European indices lower, thanks to yesterday’s sizeable drop in oil prices. Equinor, formerly known as Statoil, said current output from a key North Sea field exceeded 300,000bbl/day, but that's lower than expected.
- HSBC, the Hong Kong-exposed bank, fell 0.9%, dragging the FTSE 100, on which the stock is the heaviest single weight.
- Kingfisher also weighing the FTSE down with a big drop on shares after a quarterly sales miss
- Target, the American retailer, may lift this week's gloom in the sector after reporting higher than forecast Q3 earnings, key sales and Q4 guidance, lifting the stock 8% in pre-market trade. Victoria's Secret operator L Brands reports after tonight's U.S. close.
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.